Why Most Resolutions Fail (And How to Succeed with Your Finances This Year)

Why Most Resolutions Fail (And How to Succeed with Your Finances This Year)

Every January, millions of people make resolutions, vowing to lose weight, save money, or finally organise their lives. Yet, by February, most of those resolutions are a distant memory. When it comes to finances, the stakes are even higher, failed resolutions can lead to continued debt, stress, and a lack of progress toward your goals. But why do so many resolutions fail? More importantly, how can you set yourself up for success, especially with your financial goals?

This year, let’s break the cycle. Here’s why most resolutions don’t stick and how you can set realistic, actionable financial goals that actually work.
New Year's Resolutions and Goals

The Problem with Resolutions

1. They’re Too Vague
A resolution like “save more money” or “spend less” sounds great in theory, but without specifics, it’s destined to fail. What does “save more” mean? How much? By when? Without clarity, it’s easy to lose focus.

2. No Plan, Just Hope
Many resolutions rely on sheer willpower. While motivation can get you started, it won’t sustain you for the long haul. A solid plan is essential for turning intentions into results.

3. All-or-Nothing Thinking
Ever decided to “cut all unnecessary spending” and then given up after one unplanned purchase? All-or-nothing approaches set you up for failure because they don’t allow for flexibility.

4. No Accountability
When no one knows about your goals, it’s easy to let them slide. Having someone to cheer you on, or nudge you when you’re slipping makes a huge difference.

Why Financial Intentions Are Different

Financial goals often come with emotional baggage. Many of us have habits or mindsets about money that were shaped long before we started earning. Whether it’s fear of budgeting, guilt about past mistakes, or simply feeling overwhelmed, these emotions can sabotage even the best intentions.

The good news? Financial habits are learnable. With the right mindset, tools, and support, you can rewrite your financial story.

How to Succeed with Your Financial Goals This Year

1. Get Specific About Your Goals
Instead of “save more money,” try something like:

        • “Save $1,000 for an emergency fund by March 31.”
        • “Pay an extra $200 per month toward my credit card debt.”
        • “Spend no more than $400 a month on dining out.”

Specific goals give you a clear target to aim for. Break them down into smaller, actionable steps, and you’ll feel a sense of accomplishment with every milestone.

2. Create a 90-Day Action Plan
While it’s tempting to set year-long goals, short-term plans are more effective. That’s why 90 days is the perfect timeframe—it’s long enough to make meaningful progress but short enough to stay motivated.
For example:

        • Month 1: Assess your financial situation. Track all your expenses and create a realistic budget.
        • Month 2: Implement your budget and identify areas to cut back. Start small, like reducing subscription services or packing lunches for work.
        • Month 3: Focus on building momentum. Add any savings or debt reduction progress to your plan.
While it’s tempting to set year-long goals, short-term plans are more effective.

3. Reframe Your Money Mindset
Your mindset plays a massive role in your financial success. If you believe “I’m just bad with money” or “I’ll never get out of debt,” those beliefs will hold you back. Instead, practice positive affirmations like:

        • “I am capable of learning new money skills.”
        • “Every small step I take brings me closer to financial freedom.”

Even better, pair these affirmations with concrete actions. Every time you stick to your budget or save a little extra, you’re proving to yourself that change is possible.

4. Start Small But Stay Consistent
Big changes often fail because they’re overwhelming. Start with small, manageable habits that build over time.

        • Save $5 a day by skipping a coffee run.
        • Commit to a weekly money check-in where you review your budget and spending.
        • Set up automatic transfers to your savings account—even if it’s just $10 a week.

These small wins add up and help build confidence and momentum.

5. Track Your Progress
It’s easy to lose motivation when you don’t see results. That’s why tracking is so important. Whether it’s a spreadsheet, an app, or even a notebook, record every step of your financial journey.

        • Watch your savings grow each week.
        • Celebrate when you pay off a credit card.
        • Note the changes in your spending habits.

Seeing progress, no matter how small, reinforces your commitment to your goals.

6. Find Your Why
Why do you want to improve your finances? Maybe it’s to take your family on a dream vacation, eliminate the stress of living paycheck to paycheck, or finally buy a home.

Your “why” is your motivation. Write it down, visualize it, and keep it front and center. When the going gets tough, reminding yourself of your deeper purpose will help you stay on track.

7. Get Support
Accountability is a game-changer. Whether it’s a friend, partner, or coach, having someone to share your goals with can make all the difference. Programs like the 90-Day Money Makeover offer a built-in support system, with resources, community, and guidance to keep you on track.

Common Pitfalls and How to Avoid Them

1. Expecting Perfection
You will slip up and that’s okay. What matters is how you recover. Instead of giving up after a mistake, ask yourself: “What can I learn from this?”

2. Overloading Yourself
Don’t try to tackle everything at once. Focus on one or two key goals at a time. Once you’ve mastered them, move on to the next.

3. Comparing Yourself to Others
Your financial journey is unique. Comparing your progress to others will only discourage you. Stay focused on your own goals and celebrate your wins.

Conclusion

This year, break the cycle of failed resolutions and make 2025 the year you take control of your finances. By setting clear goals, creating a plan, and staying consistent, you’ll build habits that last a lifetime.

Remember: small steps lead to big changes. Start with one goal today, and by next January, you’ll be amazed at how far you’ve come. If you’re ready to supercharge your progress, join the LEARNING HUB and get immediate access to all courses and books including ongoing financial and mindset monthly coaching now.
Financial Resolutions

Your financial future is in your hands — let’s make it a great one! Click the button below to join the LEARNING HUB at FINANCIAL MANAGEMENT 101. It promotes long-term financial stability, provides insights into wealth-building strategies, and equips you with the skills to adapt to economic changes.
The 90 Day Money Makeover
Year-End Financial Check-Up: 7 Key Steps to Close 2024 with Confidence

Year-End Financial Check-Up: 7 Key Steps to Close 2024 with Confidence

As the year wraps up, it’s time to give your finances a little TLC and prepare to start the new year strong! Think of this as your yearly financial check-up, a simple routine that sets you up for a financially fit future. Here are seven straightforward steps to help you close out 2024 with confidence.

1. Review Your Budget with Fresh Eyes

December is perfect for giving your budget a quick health check. Ask yourself:

    • Did you stick to your budget most months?
    • Are there categories where you regularly overspent?

If you find that certain areas of your budget were tough to stick to, don’t worry; you’re not alone! Make notes on what worked and what didn’t, and consider if those categories need adjusting. Next year’s budget will feel easier to manage if it aligns more closely with your actual spending patterns.

2. Evaluate Your Financial Goals for 2024

Reflect on the goals you set at the beginning of 2024. Did you aim to build an emergency fund, pay off a certain amount of debt, or save for a big purchase? Take a moment to celebrate any wins, big or small, you’ve earned it! If there were goals you couldn’t reach, try to pinpoint what might have held you back. Life happens, and sometimes, adjustments are necessary. Use these reflections to set realistic goals for 2025 that build on the progress you’ve made.

Audit Your Subscriptions and Recurring Expenses

3. Audit Your Subscriptions and Recurring Expenses

Subscriptions can sneak up on you! Take a look at all the services you’re subscribed to, streaming platforms, gym memberships, software, meal kits and decide if they’re still worth the monthly or annual fee. Ask yourself:

    • Do you use each service enough to justify the cost?
    • Are there better deals or bundles that could help you save?

Canceling or downgrading services you no longer use can free up cash you can redirect toward your savings or debt goals.

4. Set a Holiday Spending Plan

The holiday season can be a big budget-buster if you’re not careful. This December, approach holiday spending with a clear plan:

    • Set a total holiday budget and stick to it.
    • Focus on meaningful gifts within your budget and avoid last-minute splurges.
    • Consider experiences instead of material items, they often make more memorable gifts and can be cost-effective.

You’ll thank yourself in January when your credit card bills aren’t sky-high!

5. Check-in On Your Emergency Fund


Your emergency fund is your financial safety net, and December is a great time to assess its status. Ideally, you want enough to cover three to six months’ worth of essential expenses.

If your fund has been depleted due to unexpected expenses this year, make a plan to rebuild it. If it’s in good shape, well done!

Consider adding a little extra, even if it’s just a small amount each month, it’s always better to be prepared.

You want enough to cover three to six months’ worth of essential expenses on your emergency fund

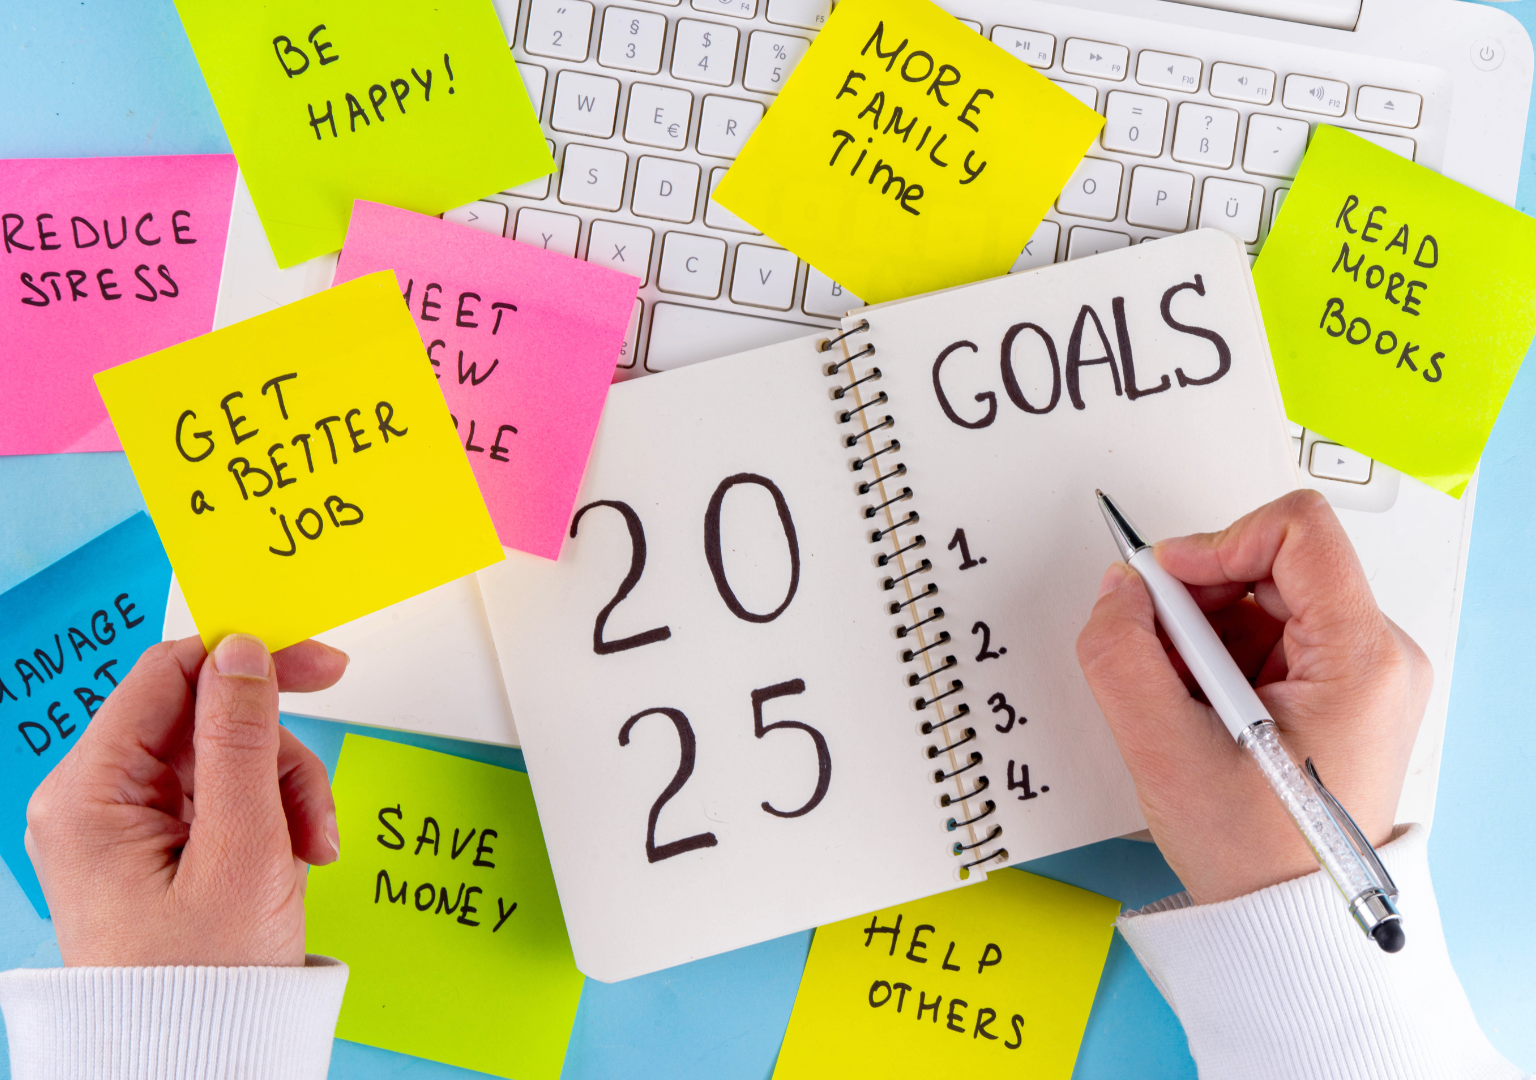
5. Update Your Financial Goals for 2025

End the year by setting some intentional goals for 2025. These don’t have to be massive changes; small, achievable goals can have a big impact on your financial future. A few ideas:

    • Set a target for increasing your savings rate, even if it’s by a modest amount.
    • Commit to paying down a certain percentage of your debt.
    • Plan to invest in education or skills that could lead to higher income opportunities.

Whatever your financial goals, write them down and keep them visible. By starting now, you’ll be well-prepared to tackle them come January.

End the year by setting some intentional goals for 2025.

Final Thoughts

Closing out the year with a financial check-up is a powerful way to put yourself in the driver’s seat for 2025. These six steps are simple but effective and give you a clear view of your financial health. Here’s to closing out 2024 strong and stepping into 2025 with confidence!

Are you ready to make 2025 your breakthrough year?

MASTER YOUR MONEY is for YOU if you are tired of financial stress and ready to transform your relationship with money. Whether you’re managing a family, building your career, or chasing your dreams, this is your chance to gain the clarity, confidence, and habits you need to thrive.

This is more than a mindset shift—it’s a transformational program that puts you on the path to lasting financial success! ? Click the button below to book a call with Karen to see if this program is right for you!

Mastering Budget and Saving Techniques
Debt Detox: Tips for Paying Down Holiday Debt and Starting the New Year Strong

Debt Detox: Tips for Paying Down Holiday Debt and Starting the New Year Strong

The holidays are a season of joy, but they can also come with a hefty price tag. If you’ve spent a bit more than planned, don’t stress! January is the perfect time to tackle that holiday debt and set yourself up for a fresh financial start. Here’s a simple guide to help you detox your debt and enter the new year feeling financially strong.

1. Assess Your Total Holiday Debt

Start by getting a clear picture of what you owe. List all your holiday-related expenses, from credit card balances to any financing or store credit used for gifts, travel, or holiday activities. Knowing your total debt helps you avoid surprises and gives you a clear starting point.

Jot down each debt’s balance, interest rate, and minimum payment. This way, you’ll be prepared to choose the best strategy for paying it off efficiently.

Assess Your Total Holiday Debt

2. Choose a Debt Repayment Strategy

Once you know what you’re dealing with, pick a strategy that works for you. Here are two popular options:

      • The Snowball Method: Start by paying off your smallest debt first. Once it’s cleared, add that amount to the next smallest debt. This method builds momentum, as paying off smaller debts quickly can feel motivating.
      • The Avalanche Method: Start with the debt that has the highest interest rate, saving you more money in the long run. Once you clear it, move to the next highest interest rate.

Both methods work well; it just depends on what motivates you more – quick wins or long-term savings.

3. Cut Back (Temporarily) to Boost Repayments

To pay down holiday debt faster, look for small, temporary cutbacks in your budget. This could be as simple as cutting down on dining out, skipping a few subscription services, or holding off on new purchases for a month or two. Every bit you save can go toward chipping away at your debt.

Even a few small changes can make a big difference over time. For example, redirecting $50 a week toward debt could mean paying off $200 extra per month, speeding up your progress considerably.

4. Avoid Adding New Debt

While you’re focusing on paying down holiday debt, try to avoid taking on new debt. This might mean holding off on big purchases or saying no to smaller “treat yourself” items for now. The goal is to keep your focus on reducing what you owe so that you’re starting the new year in a stronger financial position.

It’s all about setting boundaries. Give yourself permission to pause on non-essential spending, knowing you’ll get back to it once you’re in a more comfortable spot with your debt.

Avoid Adding New Debt

5. Consider a Balance Transfer or Consolidation Loan

If your holiday debt is spread across multiple high-interest credit cards, look into options for consolidating or transferring the balance. A balance transfer card with a 0% introductory offer can give you a breather, allowing you to pay down the principal without additional interest for a limited time.

Alternatively, a low-interest personal loan can help you consolidate multiple debts into one manageable monthly payment. Just be sure to read the fine print and choose an option with favorable terms that genuinely help your situation.

6. Look for Extra Income Opportunities

Bringing in a little extra cash can speed up your debt payoff. You might consider picking up a side hustle, selling unused items around the house, or offering freelance services if you have skills others can use. Even a small boost in income can help you make extra payments and reduce your debt faster.

Use any additional income exclusively for debt payments until you’re in a more comfortable place financially. It’s a short-term effort with long-term benefits!

7. Set New Financial Goals to Stay Motivated

While paying down holiday debt is the priority, it’s important to stay focused on your broader financial goals. Once your debt is more manageable, shift your efforts toward building savings, contributing to your emergency fund, or working on other long-term goals.

Set one or two financial goals for the year, like “Build a $1,000 emergency fund by June” or “Pay down $2,000 in debt by year-end.” Having these goals can keep you motivated and give you something to look forward to once the holiday debt is under control.

Start Today for a Better Tomorrow!

Holiday debt doesn’t have to weigh you down for long. With a focused approach and small adjustments, you can knock out that debt and start the new year with confidence. Remember, every little effort counts, and you’ll feel empowered as you watch your debt shrink. Here’s to a fresh financial start and a strong, debt-free 2025!

Are you ready to take control of your finances and start your debt-free journey? In this empowering 30-day course, we’ll guide you through actionable steps to help you break free from debt and achieve financial stability. Join the Debt-Free Journey Challenge today!

Mastering Budget and Saving Techniques
The Financial Squeeze: Why 93% of Your Income is Gone Before You Know It and How to Take Back Control

The Financial Squeeze: Why 93% of Your Income is Gone Before You Know It and How to Take Back Control

In today’s economic landscape, many families, particularly in cities like Perth, are finding it harder to get ahead. With the cost of living rising, mortgage repayments climbing, and essential expenses consuming most of the household income, it’s no surprise that families feel financially stuck. In fact, for the average family earning around $100,000 a year in Perth, up to 93% of their income is being spent on basic living expenses and mortgage repayments. That leaves a mere 7% for everything else, whether it’s saving for an emergency, investing for the future, or even enjoying life.

So, what’s driving this financial squeeze? And more importantly, how can you start taking back control of your money, reduce financial stress, and build a path toward a more secure future? Let’s dive in.

THE BREAKDOWN — Where Does The Money Go?

If you feel like your income disappears before you even have the chance to save or plan, you’re not imagining things. For the average Perth family, a substantial portion of their income is consumed by just a few major categories.

1. MORTGAGE PAYMENTS (39.7%)

With the average house price in Perth sitting at around $690,000, a family making regular mortgage repayments is typically spending about 40% of their income just to keep a roof over their head. That’s a huge chunk of money tied up in home ownership, leaving little flexibility for other financial priorities.

2. LIVING EXPENSES (52.8%)

Next comes everyday living expenses: utilities, groceries, transportation, insurance, and other necessities. For the average family, these costs take up more than half of their monthly income. With rising prices in everything from food to fuel, these essential expenses are only getting harder to manage.

3. WHAT’S LEFT? (7.5%)

After paying for housing and general living expenses, families are left with just 7.5% of their income to cover everything else. This includes savings, emergencies, vacations, entertainment, education, and more. It’s no wonder that many people feel overwhelmed by the prospect of building an emergency fund, paying off debt, or even saving for the future.

For the average family, the costs of living expenses take up more than half of their monthly income.

Inflation directly drives up the prices of essential goods and services, from food to housing to what it costs to fill your tank so you can drive to work or put clothes on your back.

THE IMPACT — Stress, Debt, and Delayed Life Goals

This financial squeeze has significant consequences for families. When most of your income is tied up in living expenses, it’s incredibly difficult to make progress on long-term financial goals, like saving for retirement, paying off debt, or even taking that well-deserved vacation.

1. INCREASED FINANCIAL STRESS

With such a small buffer between income and expenses, any unexpected cost—a car repair, medical bill, or household emergency—can throw your entire budget off course. The constant worry about money takes a toll on mental health, relationships, and overall well-being.

2. MOUNTING DEBT

When you don’t have enough income left over for emergencies, you’re more likely to rely on credit cards or loans to cover the gaps. This can lead to a vicious cycle of debt, where interest payments eat into what little income is left, making it harder to get ahead.

Financial Stress - The constant worry about money takes a toll on mental health, relationships, and overall well-being.

3. DELAYED LIFE GOALS

Many families are forced to delay or forgo important life goals, such as buying a home, starting a family, or even saving for their children’s education. The focus is on surviving month-to-month, leaving little room for long-term planning.

HOW TO TAKE BACK CONTROL OF YOUR FINANCES

So, how can families break free from this cycle? While it may seem overwhelming, the good news is that there are concrete steps you can take to regain control of your financial situation. By being proactive and strategic, you can start to reduce financial stress, create breathing room in your budget, and move toward financial security.

1. CREATE A DETAILED BUDGET AND TRACK EVERY DOLLAR

The first step to taking control of your finances is understanding exactly where your money is going. Start by creating a detailed budget that accounts for all your expenses—both fixed (like your mortgage and utilities) and variable (like groceries and entertainment). Track every dollar to see where you might be overspending or where small changes can make a big impact.

Use budgeting apps or even a simple spreadsheet to keep track of income and expenses. Once you have a clear picture of your finances, you can start making informed decisions about where to cut back or redirect funds.

Create a Detailed Budget and Track Every Dollar

2. CUT BACK ON NON-ESSENTIALS

In today’s consumer-driven world, it’s easy to get caught up in unnecessary spending. Start by evaluating your discretionary expenses—things like dining out, streaming subscriptions, and impulse purchases. While it’s important to enjoy life, small sacrifices in these areas can free up extra cash for savings or debt repayment.

Even cutting back on small expenses, like making coffee at home instead of buying it, can add up over time and create more room in your budget for the essentials.

3. REFINANCE OR RENEGOTIATE YOUR MORTGAGE

If a significant portion of your income is going toward mortgage repayments, refinancing your home loan could be a game-changer. Interest rates fluctuate, and even a small reduction in your mortgage rate can lead to significant savings over the life of the loan. Talk to your lender about refinancing options or shop around for better rates.

4. BUILD AN EMERGENCY FUND

While saving may seem impossible when so much of your income is tied up in expenses, building an emergency fund is crucial to financial security. Start small aim to save at least three to six months’ worth of living expenses. This will help you avoid relying on credit cards or loans when unexpected costs arise.

Even putting aside a small amount each month can add up over time and provide a much-needed safety net in case of emergencies.

5. INCREASE YOUR INCOME

If your current income isn’t enough to cover your expenses, it might be time to look for ways to increase it. This could mean asking for a raise at your current job, taking on a side hustle, or even exploring part-time work in a field that aligns with your skills. There are many opportunities today to monetise your talents online, whether through freelance work, selling products, or offering services.

6. PRIORITISE DEBT REPAYMENT

High-interest debt can be a major drain on your income. Focus on paying off debts with the highest interest rates first, this will save you money in the long run and free up more of your income for savings or other goals. Consider using the debt avalanche or debt snowball method to stay motivated and track your progress.

READY TO TAKE CONTROL OF YOUR FINANCES?

If you’re feeling the financial pressure, now is the time to take action. Don’t let another month go by where you feel stuck, stressed, and overwhelmed by your finances. I’m here to help you create a clear, actionable plan to take control of your money and start building a better financial future.

Join my Monthly Coaching Program, where I work one-on-one with clients to help them develop personalised budgeting strategies, eliminate debt, and build sustainable savings plans. Plus, check out my course Mastering Budgeting and Saving Techniques where I’ll teach you how to create a realistic budget that works for your family, find savings opportunities, and finally achieve financial peace of mind.
You don’t have to go through this alone together, we can turn your financial situation around. Click here to sign up for the coaching program or learn more about the course, and let’s get started on your path to financial freedom today!

By following these steps, you can start making meaningful changes in your financial life and work towards a future where you have more control, less stress, and more opportunities to get ahead. Let’s take this journey together!

Mastering Budget and Saving Techniques

Mastering Budgeting and Saving Techniques is a program designed to empower you to understand the importance of both budgeting and saving.

In this program, you will learn the fundamental concepts of how budgeting and saving is important for your financial well being.

We will explore and work through mindset shifts to empower and equip you with the tools necessary for a stress free life.

This is a hands-on program with me guiding you on how to budget, track and look at managing your money like a pro.

Which Budgeting Method is Right for You? Exploring 3 Proven Strategies

Which Budgeting Method is Right for You? Exploring 3 Proven Strategies

If you have ever wondered how to work a budget and which method is best for you, this blog post will go over three of the most popular budgeting methods that you can implement and make work for you today, allowing you to get ahead and see where your money is going.

There are three popular and proven budgeting strategies you should consider:

  1. The 50/30/20 Rule
  2. Zero Based Budgeting, and
  3. The Envelope Method

I will walk you through each of them so you can see which one is best for you and your specific financial situation.

BUDGETING METHOD – 50/30/20 RULE

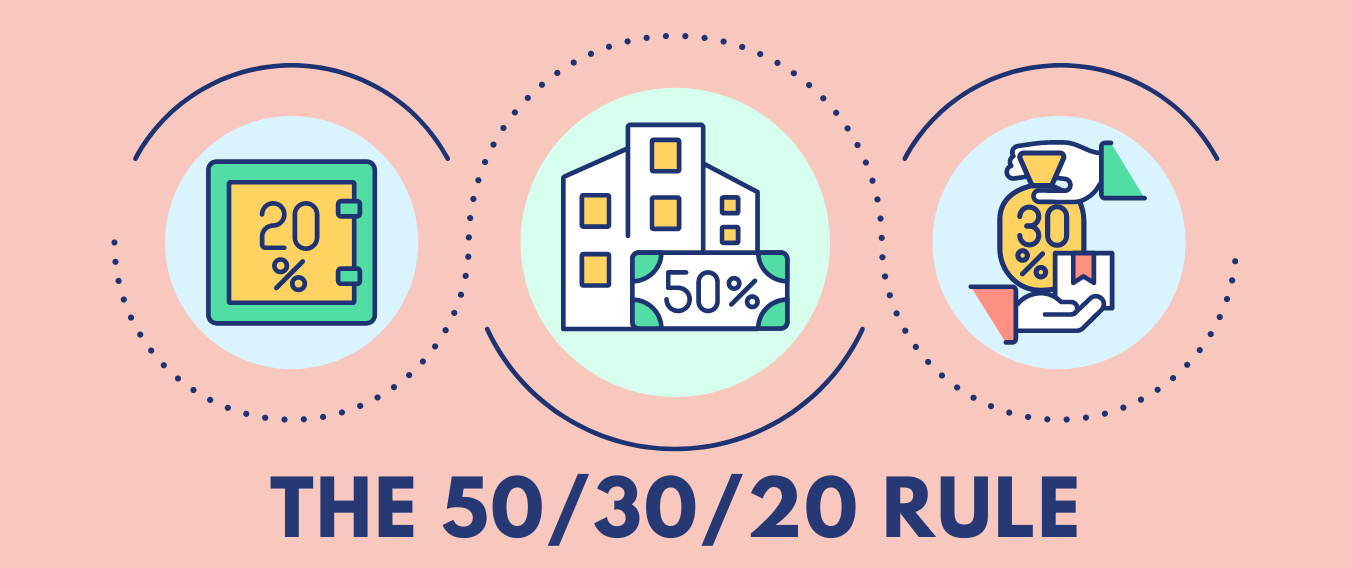
The 50/30/20 rule is a popular budgeting method that can help you allocate your income to various spending categories. It’s a straightforward and flexible guideline for managing your finances. Here’s how it works:

The 50/30/20 rule is a popular budgeting method that can help you allocate your income to various spending categories. It’s a straightforward and flexible guideline for managing your finances. Here’s how it works:

50% FOR NEEDS:

This category includes essential expenses that you must pay regularly. It covers things like housing (rent or mortgage payments), utilities (electricity, water, gas, etc.), groceries, transportation (such as car payments, insurance, and gas), minimum debt payments (like credit card minimums or student loan payments), and healthcare.

The “Needs” category should encompass no more than 50% of your after-tax income. These are the expenses that are necessary for daily living and financial stability.

30% FOR WANTS:

This category is for non-essential or discretionary spending. It includes things like dining out, entertainment, hobbies, travel, and other items or experiences that enhance your quality of life but aren’t mandatory.

The “Wants” category gives you some flexibility to enjoy life and spend on things you desire. However, it’s crucial to stay within this 30% limit to avoid overspending and maintain control over your finances.

20% FOR SAVINGS AND DEBT REPAYMENT:

The remaining 20% of your income is allocated to savings and debt repayment. This category includes savings for various financial goals like an emergency fund, retirement, a down payment on a home, or other long-term objectives. It also covers extra debt payments beyond the minimum required.

Savings are a vital part of this budgeting method. Allocating 20% of your income to savings helps you build financial security and work towards your future goals. If you have high-interest debts, consider allocating a significant portion of this 20% to debt repayment until those debts are under control.

Remember, the 50/30/20 rule is a guideline. Your actual percentages might vary depending on your unique financial situation, goals, and priorities. The key is to ensure that your spending aligns with your financial objectives and that you have a balance between covering essential expenses, enjoying life, and saving for the future.

BUDGETING METHOD – ZERO BASED BUDGETING

Zero-based budgeting is a budgeting method where you allocate your income down to zero, giving every dollar a specific purpose within your budget. In other words, you start from scratch with each budgeting period and assign every dollar you earn to an expense, savings, or debt repayment category. The goal is to ensure that your income minus your expenses equals zero. Here’s how zero-based budgeting works:

DETERMINE YOUR INCOME:

Begin by calculating your total monthly income. This includes your salary, side income, and any other sources of revenue.

LIST ALL EXPENSES:

Make a comprehensive list of all your monthly expenses. This includes both fixed expenses (like rent or mortgage, utilities, insurance, and loan payments) and variable expenses (such as groceries, transportation, dining out, and entertainment).

ALLOCATE YOUR INCOME:

Now, allocate your entire income to cover these expenses. Start with the most critical expenses, like housing, utilities, and groceries. Gradually move down the list, allocating money to each category until you’ve assigned every dollar.

TRACK YOUR SPENDING:

Throughout the month, diligently track your spending to ensure that you’re sticking to your budget. Use budgeting tools or apps to help you stay on top of your expenditures.

ADJUST AS NECESSARY:

If you find that you’ve overspent in a particular category, you’ll need to adjust your budget to cover the overage. To maintain a zero balance, you may need to reduce spending in another category.

Zero-based budgeting has several advantages:

EVERY DOLLAR HAS A PURPOSE:

This method ensures that you’re using your income efficiently and purposefully, directing your money where it matters most.

REDUCE IMPULSE BUYING:

Because every dollar must be allocated, you’re less likely to spend impulsively or frivolously.

ENCOURAGES SAVINGS AND DEBT REPAYMENT:

By including savings and debt repayment as budget categories, ZBB reinforces the importance of these financial goals.

FINANCIAL CLARITY:

It provides a clear, organised overview of your finances, making it easier to see where your money is going.

However, Zero based budgeting may not be suitable for everyone. It requires careful tracking and frequent adjustments, which can be time-consuming. Some people might prefer less detailed budgeting methods. Ultimately, the best budgeting method is the one that works for your unique financial situation and helps you reach your financial goals. Zero-based budgeting is a particularly useful tool if you want to maintain strict control over your spending and ensure that your income is allocated efficiently.

BUDGETING METHOD – THE ENVELOPE BUDGETING

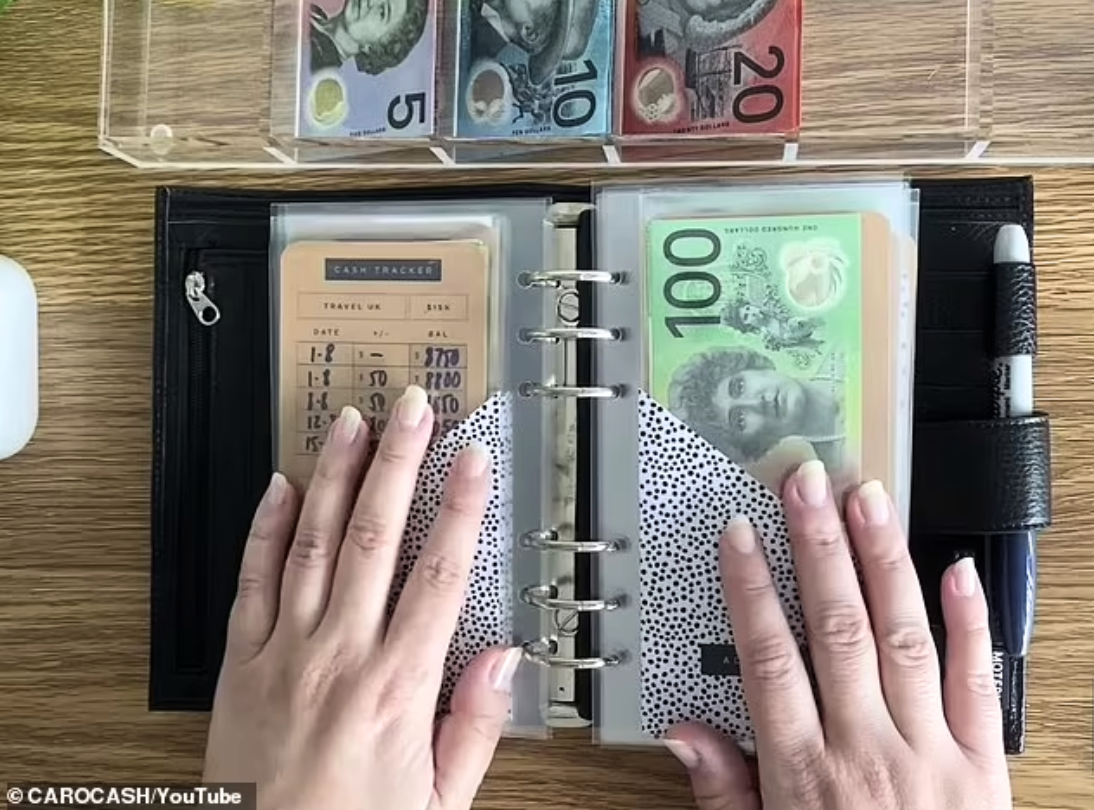
The envelope budgeting method is a cash-based budgeting system that helps you control your spending by allocating physical cash to specific categories or “envelopes” for various expenses. It’s a highly effective way to manage your finances and stay on track with your budgeting goals. However, as we’re becoming more and more a cashless society, there are ways you can still use this method via online banking and I am going to share how if you’re struggling to use cash today. Here’s how it works:

IDENTIFY YOUR SPENDING CATEGORIES:

To begin, identify the main spending categories in your budget. These categories could include groceries, dining out, entertainment, transportation, utilities, and more. Each category will have its own envelope.

DETERMINE YOUR BUDGET LIMITS:

Set a budget limit for each spending category. This is the maximum amount of cash you’ll allow yourself to spend on that category for the month. Be realistic when setting these limits to ensure they align with your overall financial goals.

CREATE PHYSICAL ENVELOPES OR USE ONLINE BANKING 

Get envelopes for each spending category. You can use actual envelopes, small pouches, or even create digital envelopes if you prefer to manage this system electronically. Label each envelope with the category name and the budgeted amount.

If you are going to use online banking, then consider using accounts like ubank or other banks that offer free transactions and multiple savings accounts that link up with a visa debit card. How this works is that the envelope category now becomes the savings account and is named as per what your paper envelope would be. Then when you need to pay for bills, you transfer the amount you need to pay into your visa debit and pay for your groceries or bills that you’ve allocated towards the envelope category. There is a video on this, so head over YouTube to see how this method is explained more clearly. Click here to WATCH THE VIDEO.

ALLOCATE CASH:

At the start of the budgeting period (usually a month), take the budgeted amount in cash for each category and place it in the respective envelope. For example, if you’ve budgeted $200 for dining out, put $200 in cash into the “Dining Out” envelope.

SPEND ONLY FROM ENVELOPES:

Throughout the month, spend only the cash from the designated envelopes for each expense category. When the cash in an envelope is depleted, that’s your signal to stop spending in that category until the next budgeting period. This physical limitation helps you avoid overspending.

RECORD YOUR TRANSACTIONS:

Keep track of your spending. Each time you spend from an envelope, make a note of the amount and the transaction in a ledger or on the envelope itself. This helps you stay accountable and provides a record of your spending. If you’re using your online banking for this, then you can clearly see and track your spending.

ROLLOVER OR ADJUST AS NEEDED:

If you have cash left in an envelope at the end of the month, you can choose to either roll it over to the next month’s budget (for that category) or use it for other financial goals, like savings or debt repayment. If you consistently have cash left over in a category, you might consider adjusting the budgeted amount for the following month.

Envelope budgeting can be particularly useful if you’re trying to curb overspending in specific categories or if you find it challenging to stick to a budget. It forces you to live within your means and prioritise your spending.

Next Step:

Choose the best budgeting method for your needs from the three options listed above.

Creating and sticking to a personal budget is an important step in effectively managing your finances. Budgeting requires discipline and commitment. Stick to your budget as closely as possible, and remember that it is a tool to help you achieve your financial goals and financial independence.

Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

Mastering Budget and Saving Techniques

Mastering Budgeting and Saving Techniques is a program designed to empower you to understand the importance of both budgeting and saving.

In this program, you will learn the fundamental concepts of how budgeting and saving is important for your financial well being.

We will explore and work through mindset shifts to empower and equip you with the tools necessary for a stress free life.

This is a hands-on program with me guiding you on how to budget, track and look at managing your money like a pro.

Are you ready to take control of your finances and start your debt-free journey?

In this empowering 30-day course, we’ll guide you through actionable steps to help you break free from debt and achieve financial stability.