Financial Resilience: Planning for Setbacks on Your Path to Debt Freedom

Financial Resilience: Planning for Setbacks on Your Path to Debt Freedom

Achieving a debt free life is a journey filled with highs and lows. While it’s great to stay optimistic, it’s equally important to be prepared for setbacks that might knock you off your progress. Unexpected expenses, job loss, medical bills, or even just plain old burnout can throw a spanner in your plans. The key to overcoming these challenges lies in building financial resilience. In this post, we’ll explore strategies to prepare for and bounce back from setbacks, ensuring you stay on track to becoming debt-free.

1. IDENTIFY YOUR MARKETABLE SKILLS

I bang on about this one all the time, why because an emergency fund is your financial safety net. It’s the cushion that helps absorb the shock of unexpected expenses without relying on credit cards or loans. A common rule of thumb is to have three to six months’ worth of living expenses saved.

Action Step:
Start by setting aside a small, manageable amount each week or month. Even $10 a week can add up. Automate your savings to ensure consistency and resist the temptation to dip into this fund for non-emergencies.

7. OFFER VIRTUAL SERVICES OR COACHING

Relying solely on one source of income can be risky. If you lose your job or face a reduction in hours, your finances can take a significant hit. Diversifying your income through side hustles, freelance work, or passive income streams can provide a buffer against such setbacks. I mentioned in a recent blog post tips and strategies on how “Using Your Talents to Accelerate Debt Repayment”. Go check this post out HERE.

Action Step:
Identify a side hustle or freelance opportunity that aligns with your skills. Set aside dedicated time each week to develop this secondary income stream.
3. CREATE A FINANCIAL CONTINGENCY PLAN

A contingency plan outlines what you’ll do in the face of financial setbacks. It could include steps like cutting back on non-essential expenses, using savings, or temporarily taking on additional work.

Action Step:
List potential setbacks and corresponding actions you would take to mitigate their impact. Keep this plan accessible and review it regularly.

4. PRACTICE CONSCIOUS SPENDING

Conscious spending involves being aware of where your money goes and making intentional choices. By being mindful of your spending, you’re better equipped to adjust your budget when faced with financial challenges.

Action Step:
Track all your spending for a month to identify where your money is going. Create a budget that prioritises essential expenses and allocates funds towards debt repayment and savings.

5. INVEST IN INSURANCE

Insurance is a vital component of financial resilience. Health insurance, home insurance, car insurance, and even disability insurance can protect you from significant financial setbacks. While it’s an added expense, the cost of not having adequate insurance can be much higher.

Action Step:
Review your current insurance policies and assess if you have adequate coverage. If not, consider adjusting your policies or shopping around for better rates.

6. PREPARE FOR IRREGULAR EXPENSES

Irregular expenses – like car repairs, home maintenance, or annual subscriptions can disrupt your debt repayment plan if not anticipated. Preparing for these expenses can prevent the need to rely on credit.

Action Step:
Review past expenses to identify irregular costs and create a separate savings fund for them. Allocate a small amount each month to this fund.

7. DEVELOP A DEBT REPAYMENT BUFFER

Instead of putting every last dollar towards debt, consider building a small buffer in your savings or checking account. This buffer can help cover unexpected expenses without halting your debt repayment plan.

Action Step:
Determine a comfortable buffer amount (e.g., $500) and gradually build it up by allocating a portion of your income each month.

8. KEEP YOUR CREDIT IN GOOD STANDING

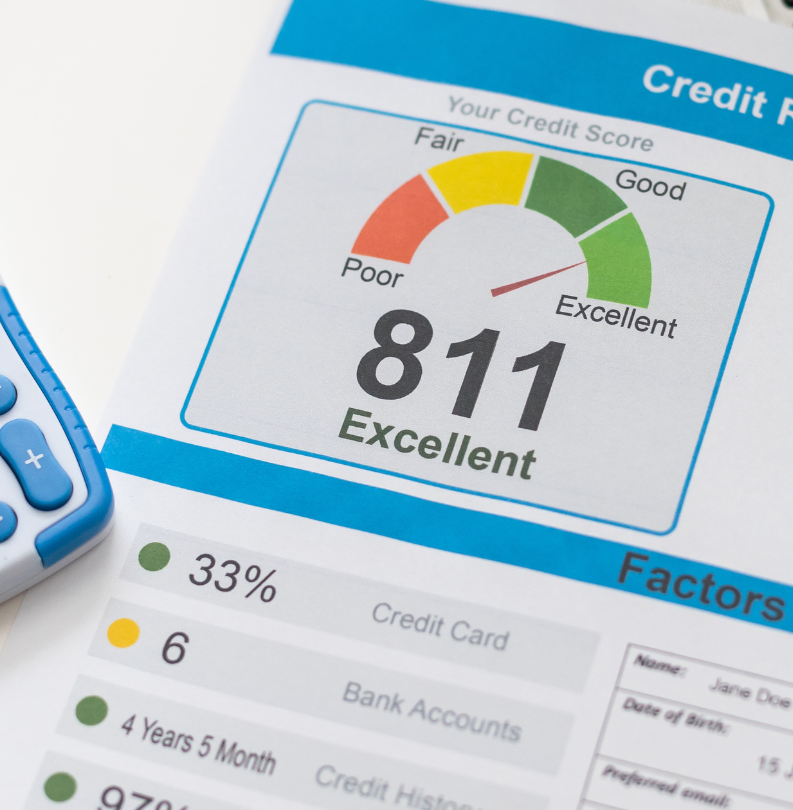
Maintaining a good credit score is crucial, even when you’re working to pay off debt. In the event of a financial emergency, having access to credit can provide a temporary solution without resorting to high-interest loans.

Action Step:
Regularly check your credit report for errors and keep credit card balances low. Make all payments on time, even if it’s just the minimum amount.
9. EMBRACE THE POWER OF NEGOTIATION

Unexpected expenses can often be negotiated or spread out. Medical bills, for instance, are notorious for being negotiable. Don’t hesitate to ask for a payment plan, a reduction in interest rates, or even a discount.

Action Step:
If faced with a large, unexpected bill, contact the service provider and enquire about payment options, discounts, or financial assistance programs.

10. FOSTER A RESILIENT MINDSET

Building financial resilience isn’t just about money—it’s also about mindset. Understand that setbacks are a part of life, and maintaining a positive outlook will help you navigate them more effectively.

Action Step:
Practice stress-management techniques such as mindfulness, meditation, or journaling. Develop a routine that helps you stay focused and calm during financial challenges.

11. BUILD A SUPPORT NETWORK

Having a support network of friends, family, or a financial advisor can provide emotional and practical support during challenging times. Surround yourself with people who understand your goals and can offer advice or encouragement.

Action Step:
Identify three people who can be part of your financial support network. Share your goals with them and ask for their support in staying accountable. 
12. PLAN FOR FUTURE SETBACKS

While it’s impossible to predict every setback, planning for potential scenarios can make them less overwhelming. Think about what could go wrong in your financial journey and devise strategies to deal with them.

Action Step:
Conduct a “financial fire drill.” Write down potential setbacks (e.g., job loss, major car repair) and create a response plan for each scenario.

13. REGULARLY REVIEW AND ADJUST YOUR FINANCIAL PLAN

Your financial situation and priorities can change over time. Regularly reviewing and adjusting your debt repayment plan ensures you stay on track and adapt to new circumstances.

Action Step:
Set a reminder to review your financial plan every quarter. Adjust your budget, debt repayment, and savings strategies based on your current situation.

CONCLUSION

Setbacks are inevitable on the path to becoming debt-free, but with the right preparation, they don’t have to derail your progress. By building financial resilience through strategic planning, conscious spending, and a positive mindset, you can bounce back stronger from any challenge. Remember, becoming debt-free is not a sprint; it’s a marathon. Stay focused, stay prepared, and keep moving forward. 
Take Control of Your Finances Today!

Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.

As your financial coach, Karen will teach you how to build financial muscle, so that you have money working to your advantage and not to your bank or financial institution’s benefit. Click here to enrol!
Mastering Budget and Saving Techniques

Are you ready to take control of your finances and start your debt-free journey?

In this empowering 30-day course, we’ll guide you through actionable steps to help you break free from debt and achieve financial stability.
The Debt-Free Mindset: How to Train Your Brain for Financial Freedom

The Debt-Free Mindset: How to Train Your Brain for Financial Freedom

Becoming debt-free isn’t just about paying off balances; it’s about reshaping your mindset to align with financial freedom. Many people get trapped in a cycle of debt because their mindset is stuck in a place of scarcity or fear. Let us look at some actionable steps for developing a debt-free mindset.

1. UNDERSTAND YOUR DEBT SITUATION

Every financial decision you make is influenced by your beliefs about money, often shaped by your experiences. Reflect on your “debt story”—the events, habits, and emotions that led you to where you are now. Write it down. Understanding your history with money is the first step to rewriting your financial future.

ACTION STEP:
Journal about your first memory of money, your feelings towards debt, and how that might have shaped your current situation.

2. REFRAME YOUR THOUGHTS ABOUT MONEY

Instead of viewing debt as a burden, see it as a challenge to overcome. Change your language from “I’m in debt” to “I am working towards financial freedom.” Positive affirmations can help you stay motivated and focused on your goal.

ACTION STEP:
Create a list of positive money affirmations, such as “I am capable of managing my finances,” and repeat them daily.

3. VISUALISE DEBT FREEDOM

Visualisation is a powerful tool. Imagine how your life will look and feel once you’re debt-free. Picture the freedom, the opportunities, and the peace of mind that comes with it. The more vivid your vision, the more motivated you’ll be to achieve it.

ACTION STEP:
Spend 5 minutes every morning visualising your debt-free life. Write down what you see and feel.

4. SURROUND YOURSELF WITH FINANCIAL POSITIVITY 

Your environment influences your mindset. If you’re surrounded by people who are also striving to be debt-free, or who have achieved it, their energy can motivate you. Join a debt-free community or follow influencers who share your financial goals.

ACTION STEP:
Join my monthly coaching program where you will feel supported and be part of a community all working towards helping you achieve your financial independence and goals. CLICK HERE for more information.

5. CHALLENGE YOUR LIMITING BELIEFS

Many of us have limiting beliefs about money—like thinking we’ll always be in debt or that financial freedom is only for the wealthy. Challenge these beliefs by seeking evidence to the contrary and reprogramming your mind with empowering thoughts.

ACTION STEP:
Write down three limiting beliefs you have about money and challenge them with factual statements or examples.

6. PRACTICE GRATITUDE FOR WHAT YOU HAVE

Shifting your focus from what you lack to what you have can create a more abundant mindset. When you’re grateful for your current resources, you’re more likely to use them wisely and attract more.

ACTION STEP:
Start a gratitude journal and list three things you’re grateful for each day, focusing on non-material aspects of your life.

7. SET REALISTIC AND ACHIEVABLE GOALS

Setting small, achievable goals can help build momentum. Instead of focusing solely on the end goal of being debt-free, set smaller milestones. Celebrate each win, no matter how small.

ACTION STEP:
Break down your debt into smaller, manageable chunks and create a reward system for achieving each milestone.

Only purchase essentials and document the impact on your finances and mindset.

8. EMBRACE MINIMALISM IN SPENDING

Adopting a minimalist approach to spending helps shift the focus from consuming to saving and investing in experiences rather than things. This mindset shift can significantly contribute to becoming debt-free.

ACTION STEP:
For one month, only purchase essentials and document the impact on your finances and mindset.

9. LEARN FROM YOUR MISTAKES WITHOUT GUILT

Everyone makes financial mistakes, but dwelling on them with guilt can keep you stuck. Instead, view them as learning opportunities. Reflect on what went wrong and how you can prevent it from happening again.

ACTION STEP:
List past financial mistakes and write down the lessons you’ve learned from each. 

10. COMMIT TO LIFELONG LEARNING ABOUT MONEY

Developing a debt-free mindset is an ongoing process. Make a commitment to continue learning about money management, investing, and wealth-building. This growth mindset will keep you motivated and informed.

ACTION STEP:
Choose one financial book or one of my online courses and programs to complete each month.

CONCLUSION

Becoming debt-free starts with transforming your mindset. By understanding your debt story, reframing your thoughts about money, and setting realistic goals, you can begin the journey towards financial freedom with a clear and positive outlook. Remember, the path to being debt-free is not just about the numbers but also about your mindset.

Take Control of Your Finances Today!

Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.

Mastering Budget and Saving Techniques
Free Budgeting Spreadsheet

GRAB YOUR OWN COPY FOR FREE

YOUR MONEY eMagazine

Are you ready to take control of your finances and secure a brighter future?

Dive into “Your Money,” the premier e-magazine by Karen G Adams, the Founder of Financial Management 101.

Subscribe for FREE!

What Happens When You Miss a Loan Payment: Avoiding the Financial Pitfalls

What Happens When You Miss a Loan Payment: Avoiding the Financial Pitfalls

Hey there, my savvy money managers!

Today, we are going over a topic that is about as fun as stepping on a Lego in the middle of the night: missing loan payments. Missing a payment on a credit card, mortgage, or personal loan can have serious consequences for your financial health. But do not worry, we will navigate these rough waters together, so by the end of this post, you will understand why you should not miss payments and how to stay on track like a financial ninja. Let’s get started!

The Domino Effect of Missing a Payment

1. CREDIT SCORE TAKES A HIT

Consider your credit score to be a report card for your finances. Missing a payment is similar to failing a big test; it hurts. When you miss a payment, your lender reports it to the credit bureaus (Experian, Equifax, Veda and TransUnion), and your credit score may suffer significantly. A lower credit score means higher interest rates on future loans and credit cards, and it may even limit your ability to rent an apartment or find work. Yikes!

    2. LATE FEES AND PENALTIES

    Lenders love late fees because it is their way of saying, “We told you so!” These fees can range from mildly annoying to extremely painful. Late fees on credit cards can be up to $40. Mortgages and personal loans may have even steeper penalties. These additional costs can quickly accumulate, making it difficult to catch up.

    3. HIGHER INTEREST RATES

    If you fail to pay your credit card bill on time, you may face the dreaded annual penalty rate. This is a higher interest rate that can apply to your existing balance and future purchases. Penalty rates can soar up to 29.99%, turning your manageable debt into a mountain of despair.

    4. COLLECTION AGENCIES COME CALLING

    If you continue to miss payments, your debt may be sent to a collection agency. These people are persistent; they will call, email, and possibly even write you a letter or two. Having a debt in collections can harm your credit score even more and cause a lot of stress.

    5. FORECLOSURE AND REPOSSESSION

    Missing multiple mortgage payments can result in foreclosure, in which the lender takes back your home. Similarly, if you default on a car loan, the lender may seize your vehicle. Losing your home or car is a life-changing event that you should definitely avoid.

    The Ripple Effect on Your Life

    1. EMOTIONAL AND MENTAL STRESS

    Financial issues can be extremely stressful. Worrying about missed payments, mounting debt, and the potential loss of assets can have a negative impact on your mental health. Anxiety, depression, and insomnia are common side effects.

    2. RELATIONSHIP STRAIN

    Money problems are one of the most common causes of relationship stress. Arguments about money can strain relationships with your partner, family, and friends. Being open and working together on a plan can help mitigate these issues. 

    3. LIMITED FINANCIAL FLEXIBILITY 

    When you fall behind on your payments, you lose financial flexibility. You may have to forego saving for emergencies, retirement, and other goals. Living paycheck to paycheck becomes a harsh reality.

    How To Avoid Missing Payments Like a Pro

    1. MAKE A BUDGET AND STICK TO IT

    Yes, the B-word – budget. It might not sound glamorous, but creating a budget is the foundation of good financial health. Keep track of your income and expenses to ensure that you have enough money set aside for loan payments. There are numerous budgeting apps available that can make this process easier and even more enjoyable.

    2. SET UP AUTOMATIC PAYMENTS

    Automated payments are your best friend. They ensure that you never miss a due date, and many lenders provide this feature. Just make sure you have enough money in your account to cover the payments – you don’t want to incur overdraft fees!

    3. CREATE AN EMERGENCY FUND

    Life is unpredictable. An emergency fund serves as a financial cushion for unforeseen expenses that can disrupt your payment schedule. Aim to save three to six months’ worth of living expenses in a separate, easily accessible account.

    4. COMMUNICATE WITH YOUR LENDER

    If you think you are going to miss a payment, do not hide under the rock. Contact your lender as soon as possible. Many lenders are willing to work with you if you take proactive steps. They might offer temporary relief options like payment deferrals, reduced interest rates, or a modified payment plan.

    5. PRIORITISE YOUR DEBTS

    Not all debts are equal. High-interest debts, such as credit cards, should be your primary focus because they can quickly spiral out of control. Use the snowball or avalanche method to tackle your debts systematically.

    6. REVIEW YOUR STATEMENTS REGULARLY

    Keep track of your loan statements and bank accounts. This allows you to catch any errors or unauthorised charges early and keeps you informed of your payment due dates.

    7. IF IT SEEMS LIKE THERE’S NOT ENOUGH MONEY

    You may need to look for some extra money, like a side hustle or additional part time work— anything that you can fit into your already busy schedule to help ease the stress and pay down those debts quicker.  There are many ways you can earn a few extra dollars, so look at your creative talents and see if you can earn extra income from areas like tutoring, arts and crafts to name a few.

    Look at your creative talents and see if you can earn extra income from areas like tutoring, arts and crafts to name a few.

    A Fun Challenge: The No-Spend Week

    Here’s a fun little challenge to help you stay on track – try a no-spend week. For one week, don’t spend money on anything that isn’t a necessity. Use up what you have in the pantry, avoid eating out, and avoid online shopping. This can help you save a significant amount of money, which you can put towards your loan payments.

    Conclusion: Stay Ahead of the Game

    Missing a loan payment may feel like the end of the world, but it does not have to be. Understanding the consequences and taking proactive steps will help you avoid pitfalls and stay financially healthy. Remember, it is all about staying informed, being organised, and making sound decisions.

    So buckle up, set up those automatic payments, and keep an eye on your finances. With a little discipline and planning, you will be able to navigate your financial journey with ease in no time. And hey, if you ever need a pep talk or some financial coaching, you know where to find me. Enjoy managing your money!

    By following these suggestions, you will be well on your way to avoiding late payments and maintaining a healthy financial future. Now get out there and conquer those loan payments like the financial superstar you are!

    Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

    Mastering Budget and Saving Techniques
    Free Budgeting Spreadsheet

    GRAB YOUR OWN COPY FOR FREE

    YOUR MONEY eMagazine

    Are you ready to take control of your finances and secure a brighter future?

    Dive into “Your Money,” the premier e-magazine by Karen G Adams, the Founder of Financial Management 101.

    Subscribe for FREE!

    How to Become Debt-Free: A Step-by-Step Guide to Financial Freedom

    How to Become Debt-Free: A Step-by-Step Guide to Financial Freedom

    Are you tired of feeling trapped by debt? You’re not alone. Debt can feel like a heavy burden, but the good news is that it doesn’t have to be a lifelong sentence. With the right mindset and strategies, you can break free from debt and start building a more secure financial future. Let’s dive into the steps to becoming debt-free and reclaiming control over your finances!

    1. UNDERSTAND YOUR DEBT SITUATION

    Before you can tackle your debt, you need to have a clear understanding of what you’re dealing with. Start by making a list of all your debts, including:

    • Credit cards
    • Student loans
    • Personal loans
    • Car loans
    • Mortgage

    For each debt, write down the total amount owed, the interest rate, and the minimum monthly payment. This will give you a comprehensive view of your debt landscape and help you prioritise which debts to focus on first.  If you need a little hand with getting this down, you can download my FREE debt repayment spreadsheet by clicking HERE.

    2. CREATE A BUDGET AND STICK TO IT

    Creating a budget is an important step towards debt freedom. A budget helps you track your income and expenses, ensuring you’re not spending more than you earn. Here’s how to create an effective budget:

    • Calculate your monthly income: Include all sources of income, such as your salary, side gigs, and any other earnings.
    • List your monthly expenses: Categorise your expenses into essentials (like rent, utilities, groceries) and non-essentials (like dining out, entertainment).
    • Allocate funds for debt repayment: After covering your essentials, allocate a portion of your income specifically for debt repayment.

    Sticking to your budget requires discipline, but it’s essential if you want to make significant progress towards becoming debt-free.

    Want some help creating your budget then download my FREE budget spreadsheet where I make it easier to workout what’s happening with your money. Click HERE.

    3. CUT UNNECESSARY EXPENSES

    One of the quickest ways to free up money for debt repayment is by cutting unnecessary expenses. Review your budget and identify areas where you can reduce spending. Here are some common areas where people tend to overspend:

    • Dining out: Try cooking at home more often.
    • Subscription services: Cancel subscriptions you don’t use regularly.
    • Impulse purchases: Avoid buying items you don’t need by implementing a 24-hour rule before making non-essential purchases.

    Remember, every dollar saved is a dollar that can go towards paying off your debt faster!

    4. CHOOSE A DEBT REPAYMENT STRATEGY

    There are several strategies for repaying debt, but two of the most popular are the Debt Snowball and Debt Avalanche methods:

    • Debt Snowball Method: Focus on paying off your smallest debt first while making minimum payments on all others. Once the smallest debt is paid off, move on to the next smallest. This method gives you quick wins and boosts motivation.
    • Debt Avalanche Method: Focus on paying off the debt with the highest interest rate first while making minimum payments on all others. This method saves you the most money in interest over time.

    Choose the method that resonates most with you and start chipping away at your debt!

    5. INCREASE YOUR INCOME

    If cutting expenses isn’t enough, consider ways to increase your income. This additional income can be used entirely for debt repayment. Here are a few ideas to boost your income:

    • Take on a side hustle: Consider freelancing, tutoring, or driving for a ride-share service.
    • Sell unused items: Declutter your home and sell items you no longer need.
    • Ask for a raise or promotion: If you’ve been excelling at work, now might be the time to ask for a raise.

    Every bit of extra income helps in accelerating your journey to becoming debt-free.

    6. BUILD AN EMERGENCY FUND 

    While it might seem counterintuitive to save money when you’re trying to pay off debt, having an emergency fund is crucial. An emergency fund acts as a financial safety net, preventing you from going deeper into debt when unexpected expenses arise. Aim to save at least $1,000 initially and gradually build it to cover 3-6 months’ worth of expenses.

    7. NEGOTIATE LOWER INTEREST RATES

    High-interest rates can significantly increase the amount you owe over time. Don’t be afraid to negotiate with your creditors to lower your interest rates. Here’s how:

    • Call your creditors: Explain your financial situation and request a lower interest rate.
    • Consider transferring your balance: Some credit cards offer 0% interest on balance transfers for a limited period. This can help reduce interest costs and pay off debt faster.
    • Refinance loans: Refinancing can lower your interest rate and reduce monthly payments.

    Lowering your interest rates means more of your payments go towards reducing the principal amount, helping you get out of debt faster.

    8. AVOID NEW DEBT

    While you’re working to become debt-free, it’s essential to avoid accumulating new debt. Resist the temptation to use credit cards or take out new loans. If necessary, consider freezing your credit to prevent taking on new debt until you’re back on solid financial footing.

    9. TRACK YOUR PROGRESS AND CELEBRATE MILESTONES

    Tracking your progress is vital to staying motivated. Use a debt repayment tracker or app to monitor your journey. Celebrate each milestone you reach, whether it’s paying off a specific amount or clearing a particular debt. Celebrating these wins keeps you motivated and committed to your goal.

    10. SEEK PROFESSIONAL HELP IF NEEDED

    If your debt feels overwhelming, or if you’re struggling to create a repayment plan, consider seeking help from me as your financial coach. As a financial coach, I can provide personalised advice and strategies tailored to your situation, helping you navigate your way out of debt more effectively.

    11. STAY COMMITTED TO THE JOURNEY

    Becoming debt-free is a marathon, not a sprint. It requires time, effort, and unwavering commitment. There will be challenges along the way, but staying focused on your goal will make the journey worth it. Remember, the freedom and peace of mind that come with being debt-free are invaluable.


    CONCLUSION: EMBRACE YOUR FINANCIAL FREEDOM

    Becoming debt-free is one of the most empowering steps you can take for your financial future. It opens up a world of possibilities, from building wealth to achieving your financial dreams. By understanding your debt, creating a budget, cutting expenses, increasing your income, and sticking to a debt repayment strategy, you’re well on your way to financial freedom.

    Start today—your debt-free future awaits!

    By following these steps and staying committed, you’ll not only become debt-free but also build a strong foundation for a financially secure future. Remember, every step you take towards eliminating debt brings you closer to the life you desire.

    Are you feeling overwhelmed by debt? Do you want a clear, actionable plan to help you pay off your debts and achieve financial freedom? This Debt Repayment Strategy Worksheet is here to guide you every step of the way.

    Mastering Budget and Saving Techniques
    Free Budgeting Spreadsheet

    GRAB YOUR OWN COPY FOR FREE

    YOUR MONEY eMagazine

    Are you ready to take control of your finances and secure a brighter future?

    Dive into “Your Money,” the premier e-magazine by Karen G Adams, the Founder of Financial Management 101.

    Subscribe for FREE!

    Midlife Crisis or Opportunity? Finding Financial Zen in Your 40s and 50s

    Midlife Crisis or Opportunity? Finding Financial Zen in Your 40s and 50s

    So, if you listened to and read my previous blog and podcast, you would have heard some advice for those in the financial sandwich age 35 to 50.
    So, let us talk about people in their mid-40s and 50s. This is the stage where you are old enough to have gained some wisdom but young enough to wonder if you have made all the right financial decisions. If you feel like you are on the verge of a midlife financial crisis, take a deep breath. Your trusted financial coach is here to turn that crisis into an opportunity, with a dash of humour to keep things light.

    1. THE MIDLIFE FINANCIAL CHECK-UP

    Do not skip your financial checkup any more than you would your annual physical. Take a hard look at your finances. Review your budget, debt, savings, and investments. Are you on track to achieve your goals? If not, it is time to make adjustments. Think of it as a financial tune-up. You would not drive your car with the check engine light on indefinitely, so do not neglect your finances.

    2. DEBT DETOX: TIME TO CLEAN THE HOUSE

    Debt is like that guest who overstays their welcome. It’s time to show it the door. Start by listing all your debts: credit cards, student loans, car loans, and any other liabilities. Tackle high-interest de bt first using the avalanche method or start small with the snowball method. Whatever strategy you choose, the key is to be consistent in your payments. Celebrate small victories along the way—each paid-off debt is a step closer to financial freedom.

    3. REVIEW YOUR RETIREMENT GOALS

    By now, you probably have some retirement savings, but is it enough? Use retirement calculators to estimate how much you’ll need. Adjust your contributions if necessary. Do not be concerned if you are falling behind. If you are over 50, consider maxing out your retirement accounts or looking into catch-up contributions. And remember that every little bit helps. Even small increases in your contributions can make a big difference over time.

    4. HEALTH SAVINGS ACCOUNT (HSA): THE TRIPLE TAX BENEFIT

    If you have a high-deductible health plan, an HSA is your new best friend. Contributions are tax deductible, funds grow tax-free, and withdrawals for qualified medical expenses are tax-free. It’s like a financial hat trick. Plus, after age 65, you can use HSA funds for non-medical expenses without a penalty (though you’ll pay regular income tax). It’s a win-win.

    5. SIDE HUSTLES: NOT JUST FOR MILLENIALS

    Who says side hustles are only for the younger generation? Your 40s and 50s are ideal times to investigate new income streams. A side hustle, whether it is freelancing, consulting, or turning a hobby into a business, can help you earn more money while also providing you with creative opportunities. It is also an excellent way to test the waters if you are thinking about changing careers or staying active in retirement.

    6. PROTECT YOUR ASSETS: INSURANCE AND ESTATE PLANNING

    Life insurance, disability insurance, and long-term care insurance may not be the most exciting topics, but they are critical for safeguarding your assets and ensuring your family’s financial stability. Review your policies and make sure they align with your current needs. And don’t forget estate planning. A will, power of attorney, and healthcare directive are all important documents that can save your loved ones a lot of stress and heartache.

    Estate Planning ensures that your assets are distributed according to your wishes. Without a plan, state laws will dictate the distribution, which may not align with your desires.

    7. INVEST IN EXPERIENCES, NOT JUST THINGS

    As you get older, you realise that memories are worth more than material possessions. Prioritise spending on experiences that will improve your life. Travel, hobbies, and quality time with loved ones all contribute to your happiness and well-being. Plus, they don’t depreciate like that fancy car or gadget.

    8. KEEP LEARNING: FINANCIAL EDUCATION NEVER STOPS

    The financial world is constantly changing, and staying informed is essential. Keep your financial knowledge up to date by reading books, attending seminars, or taking online courses. Consider working with a financial advisor to help you navigate complex decisions and stay on track. Remember: knowledge is power, and it is never too late to learn something new.

    Take these suggestions with a sense of humour and an open mind. Your 40s and 50s can be a time of financial growth and opportunity. So, dust off those financial cobwebs, make a plan, and move forward with confidence. You’ve got this!

    Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

    Mastering Budget and Saving Techniques
    Free Budgeting Spreadsheet

    MONTHLY COACHING

    Take Control of Your Finances Today!

    Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.