Busy Is Not Profitable: 7 Financial Foundations Every Business Owner Needs

Busy Is Not Profitable: 7 Financial Foundations Every Business Owner Needs

There’s a big myth in small business that if you just work hard enough, everything will eventually click into place.

Spoiler alert: hard work matters, but hard work without financial foundations can leave you exhausted, underpaid, and wondering why your business still feels so heavy.

I see this all the time with small business owners, tradies, franchisees, coaches, and self-employed professionals.

They are flat out. Clients are coming in. Invoices are going out. The calendar is packed.

And yet… There is still stress. Still pressure. Still that sinking feeling of, “Why does it feel like I’m doing all this work and not getting ahead?”

Here’s why:

Because busy is not profitable. And being great at your trade or profession is not the same as having strong money systems.

The good news? You do not need a finance degree to fix this. You just need the right foundations.

Here are seven of the most important ones.

1. A cashflow system that tells the truth

Cashflow is not something you check when you are already in trouble.
It is something you build so you can stay out of trouble.

A good cashflow system shows you:

  • what is coming in
  • what is going out
  • what bills are approaching
  • what is available to spend
  • what needs to be set aside for tax, super, wages, and future costs

Cashflow gives you visibility. Visibility gives you control.

2. Clear separation between personal and business money

Using your personal account like a business overdraft creates confusion fast.

It becomes harder to track spending, harder to know what the business is really earning, and harder to make clean decisions.

Separating business and personal finances is one of the fastest ways to reduce chaos.
It is not about being fancy. It is about being clear.

3. Pricing that actually protects your profit

So many business owners price from fear.

Fear of losing the sale.
Fear of seeming too expensive.
Fear of being judged.

But underpricing does not make you more professional. It makes your business more fragile.

Your pricing needs to cover more than the job in front of you. It needs to reflect overheads, admin time, tax obligations, profit goals, and the actual value you deliver.

Pricing with confidence is not greedy.
It is responsible.

4. A plan to pay yourself properly

Using your personal account like a business overdraft creates confusion fast.

It becomes harder to track spending, harder to know what the business is really earning, and harder to make clean decisions.

Separating business and personal finances is one of the fastest ways to reduce chaos.
It is not about being fancy. It is about being clear.

5. Weekly and monthly money rhythms

You do not need to stare at your numbers every day.
But you do need a rhythm.

That might include:

  • checking cashflow weekly
  • reviewing key reports monthly
  • monitoring expenses and margins
  • tracking unpaid invoices
  • spotting small issues before they turn into big ones

Confidence with numbers is built through repetition, not perfection.

6. Knowing your numbers without drowning in them

You do not need to obsess over every metric.
You do need to know the numbers that matter.

Think:

  • revenue
  • gross profit
  • operating expenses
  • net profit
  • cash position
  • debt levels
  • wage costs
  • tax set-asides

The goal is not more complexity.
The goal is better decisions.

When you know what your numbers are saying, you stop making emotional decisions and start making strategic ones.

7. A business structure that can handle growth

Growth is exciting, but if your systems are messy, it can magnify every weakness.

That is why foundations matter before scaling.

You want business systems that support:

  • clear accounts setup
  • simple automations
  • better reporting
  • cleaner budgeting
  • stronger decision-making
  • less burnout

Strong structure makes growth feel possible instead of painful.
Business foundations create freedom

Why this matters right now

The business landscape is not getting easier.
Costs are rising. Margins can be tight. Pressure builds quickly when you do not have clarity.

That is exactly why now is the time to stop relying on memory, hope, and hustle alone.

The strongest business owners are not always the loudest or busiest.
They are the ones who know their numbers, trust their systems, and make decisions early.

Foundations Create freedom

Let’s make this simple. When your financial foundations are solid, you get:

  • less panic
  • less avoidance
  • less confusion
  • better decisions
  • stronger profit
  • more confidence
  • more breathing room

And honestly? More enjoyment.

Because business should not feel like one long financial mystery.
    A business structure will help you handle growth

    Your invitation to stop winging it

    If you know your foundations need work, you are not alone.
    And you do not have to figure it all out the hard way.

    That is exactly what The Edge Bootcamp is designed to help you do.

    Over two practical, high-impact days, we dig into the real foundations of profitable business: money systems, CEO mindset, cashflow, paying yourself, pricing, budgets, business setup, reading your numbers, leadership, growth stages, and more.

    This is for business owners who want results, not just motivation.

    Join The Edge Bootcamp in May and give your business the foundations it needs to make money, keep money, and enjoy the ride.

    Because being flat out is not the goal.
    Building a business that works for you is.
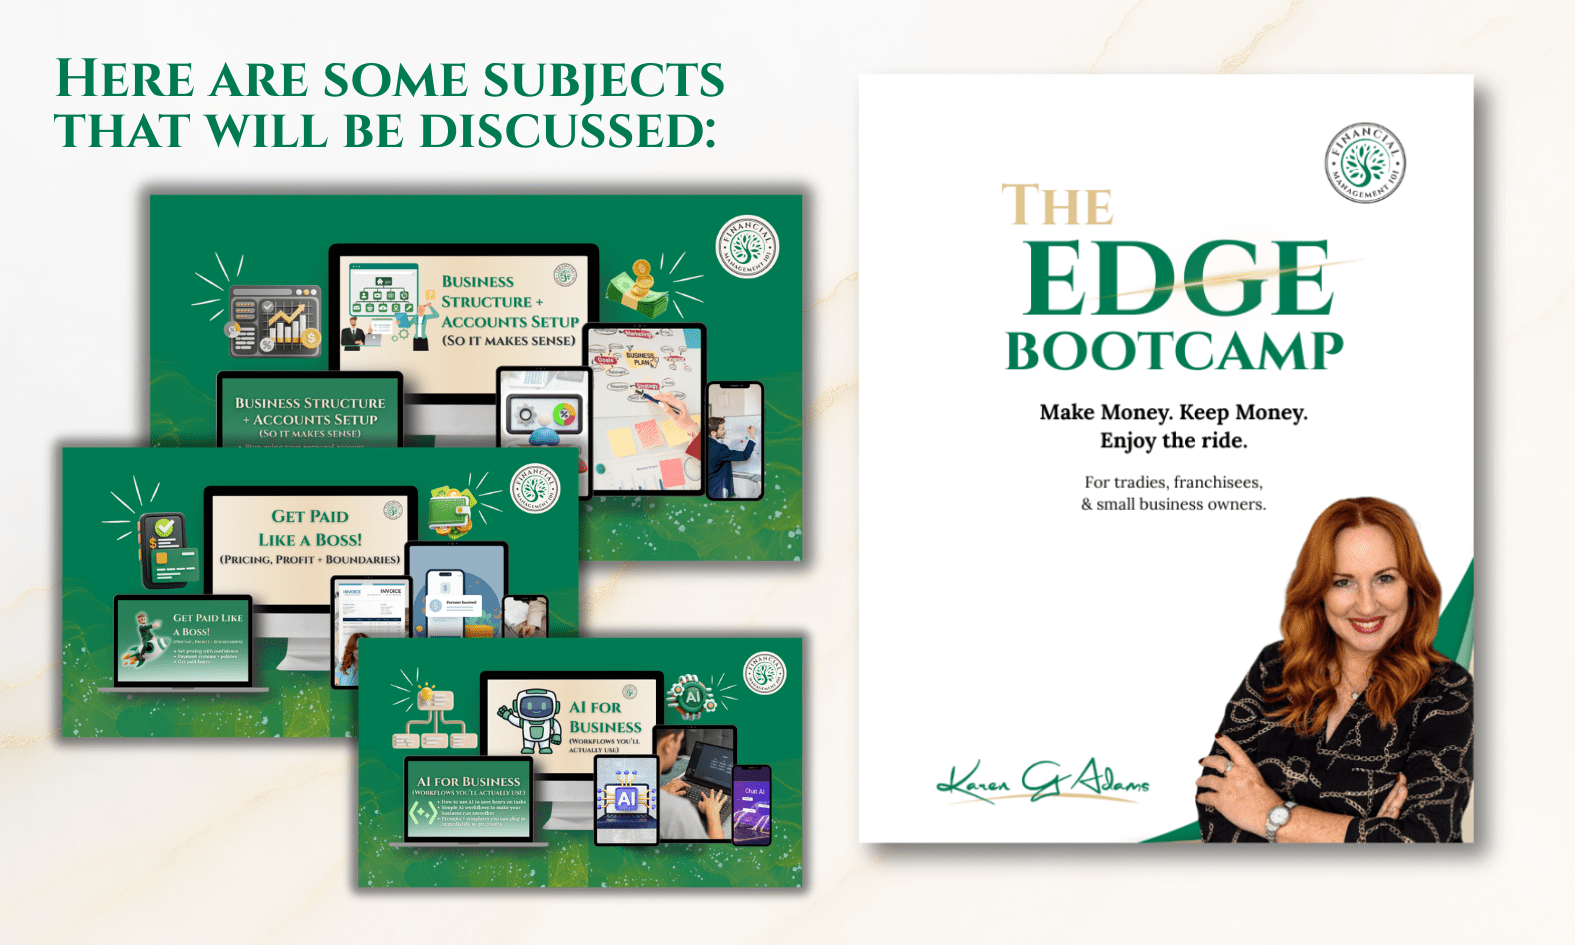
    Join The Edge Bootcamp

    #HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings 
     

    How Can I Rebuild My Confidence After Making a Financial Mistake or Falling Behind on My Budget?

    How Can I Rebuild My Confidence After Making a Financial Mistake or Falling Behind on My Budget?

    We’ve all had that moment.

    You check your bank account… and it’s lower than you thought.
    You open your credit card bill… and it’s higher than you expected.
    You look at your budget… and realse you haven’t followed it for two weeks.

    Cue the shame spiral.

    If you’ve recently made a money mistake – or you just feel behind – I want you to know this:

    You are not alone.
    You are not a failure.
    And you are absolutely capable of bouncing back stronger.

    This blog will walk you through how to move from guilt to growth, and rebuild your confidence one step at a time.

    1. Separate Your Self-Worth from Your Net Worth

    First and foremost: you are not your bank balance.

    Your financial missteps don’t make you “bad with money.” They make you human.

    Whether you overspent, ignored your budget, or slipped back into old habits, it doesn’t define who you are. It’s a moment – not a life sentence.

    Start here:

    • Remind yourself: “I am capable of change.”
    • Reflect on a past financial win, no matter how small

    Say out loud: “I forgive myself. I’m ready to move forward.”

    2. Get Honest (Without the Shame)

    Let’s name what happened – not to beat yourself up, but to take your power back.

    Ask yourself:

    • What did I spend that I hadn’t planned for?
    • Did I avoid tracking or checking in with my money?
    • Did I say “yes” to things I couldn’t afford?

    Write it all down. You’re not here to judge yourself – just to gain clarity so you can move forward with purpose.

    3. Understand What Triggered the Slip-Up

    There’s always a “why” behind every money misstep mand understanding it is key to change.

    Common triggers:

    • Emotional spending (boredom, stress, celebration)
    • People-pleasing (saying yes to things out of guilt)
    • Lack of planning (unexpected expenses you didn’t prep for)
    • Old money stories (like “I’ll never get ahead anyway”)

    Identifying the trigger gives you a new layer of awareness and that’s when real change begins.

    4. Reset with a Micro-Goal

    When your confidence is shaken, the best thing you can do is create a tiny win that rebuilds momentum.

    Here are some examples:

    • Track your spending for the next 3 days
    • Create a mini budget just for this week
    • Make one extra payment toward your credit card
    • Pause one subscription and save the money instead

    Success is a series of small, intentional steps. Start with one.

    Create a mini budget for this week

    5. Watch Your Words (They Matter More Than You Think)

    Your internal dialogue becomes your financial reality.

    Let’s flip the script:

    ❌ “I’m terrible with money.”
    ✅ “I’m learning how to manage my money better every day.”
    ❌ “I’ll never get out of debt.”
    ✅ “Every payment I make moves me closer to freedom.”
    ❌ “I can’t stick to a budget.”
    ✅ “I’m figuring out a system that works for me.”

    Language matters. Speak like someone who’s growing because you are.

    6. Track Progress, Not Perfection

    You don’t have to get everything right to be making progress. Celebrate the fact that:

    • You noticed the slip-up
    • You chose to stop and reflect
    • You’re taking action now

    That’s what winning with money actually looks like.

    Make a habit of reflecting each month:

    • What went well?
    • Where did I struggle?

    • What can I adjust?

    And remember: even showing up for your finances when it’s hard is worth celebrating.

    7. Lean Into Support – Don’t Do This Alone

    Shame thrives in isolation. Confidence grows in community.

    Find a space where:

    • You can ask questions without feeling judged
    • You can share your wins and struggles
    • You can be held accountable to your goals

    That’s exactly what Financial Muscle Coaching is a coaching and accountability space, where we normalise setbacks and celebrate bounce-backs.

    Inside the membership, you’ll find structure, strategy, and support – all in one place.

    8. Build Your Financial Muscle, One Rep at a Time

    Rebuilding financial confidence is like building physical strength – it happens one rep at a time.

    One decision to check your balance.
    One habit of tracking your spending.
    One conversation where you ask for help instead of hiding.
    One payment that moves you forward.

    You don’t need to leap – you just need to lift. And every lift makes you stronger.

    Final Thoughts

    Mistakes are part of the journey – not the end of it.

    You are not behind. You are not bad with money. And you don’t have to do this perfectly to make progress.

    Every time you choose to come back – to review, reflect, and reset – you’re rebuilding your confidence.

    You’re showing yourself what you’re made of.
    And you’re writing a new money story that’s rooted in self-trust, resilience, and growth.

    You’ve got this. And I’m right here cheering you on.

    ? Join Financial Muscle Coaching

    If you’re tired of navigating your money alone – or beating yourself up every time you slip – Financial Muscle Coaching is the place for you.

    In this weekly coaching space, you’ll get:
    ✅ Encouragement instead of criticism
    ✅ Clear, doable action plans that meet you where you are
    ✅ Real accountability to build habits and confidence that last

    No more shame. No more silence. Just strength, strategy, and steady growth.

    Join Financial Muscle Coaching Now

    #HowToChangeMoneyMindset #ResetMyMoneyBeliefs #BuildFinancialConfidence #MoneyMindsetHelp #FinancialMindsetCoaching #HowToFeelBetterAboutMoney #WhyDoIFeelStressedAboutMoney #NewYearMoneyMindset #MoneyMindsetReset2025 #PositiveMoneyBeliefs #MoneyMindset #FinancialFreedomJourney #MoneyCoach #BudgetMindset #AbundanceMindset

    Why Do Most People Fail at Their New Year’s Resolutions and How Can I Actually Stick to My Financial Goals This Year?

    Why Do Most People Fail at Their New Year’s Resolutions and How Can I Actually Stick to My Financial Goals This Year?

    New Year, Same Resolutions? Let’s Talk About It.

    Ahhh January the month of green smoothies, gym selfies, and freshly purchased planners that are definitely going to change your life this time, right?

    If you’re like most people, you’ve probably made a few New Year’s resolutions that sounded amazing on January 1st… but by February? They’re long forgotten, buried under Uber Eats receipts and good intentions.

    And when it comes to money goals? Ohhh, this is where the guilt hits hard.

    So let’s break it down: Why do New Year’s resolutions fail and what can you do instead to actually stick to your financial goals this year?

    Spoiler: It’s not about willpower. It’s about building financial muscle and that’s what I help people do every day.

    The Stats Don’t Lie – Most Resolutions Don’t Last

    According to research:

    • 43% of people expect to fail their resolutions by February
    • Only 9% actually feel successful by the end of the year
    • The most common failed resolutions? Diet, fitness… and yes — money

    Why? Because most resolutions are made in the heat of a moment – not rooted in a system, a strategy, or support.

    We say things like:

    • “I’m going to save $5,000 this year!”
    • “I’m cutting up ALL my credit cards!”
    • “I’ll never spend money on takeout again!”

    …but we don’t have a real plan behind it. Just hope, hype, and maybe a pretty notebook.

    New Year’s Resolutions

    Why Financial Resolutions Fail: The Real Talk

    Here’s what I’ve seen in my coaching practice over and over:

    1. The goal is too vague.
      “Get better with money” isn’t a goal – it’s a wish. Your brain doesn’t know what to do with that.
    2. There’s no timeline.
      Saving “someday” or “this year” doesn’t create urgency or clarity.
    3. You try to do too much, too fast.
      Going from zero to “never spending a dollar unless it’s pre-budgeted” is like deciding to run a marathon when you haven’t walked around the block in months.
    4. No accountability.
      When you’re the only one who knows your goals… it’s easy to quit. Life gets busy, bills pile up, and suddenly, your “big resolution” is a tab you closed weeks ago.
    5. Shame gets in the way.
      One slip-up, and your inner critic screams, “See?! You always mess this up!” And so you give up again.

    Sound familiar?

    So What Actually Works? (This Is Where It Gets Fun)

    Instead of setting rigid resolutions, try this instead:

    ✅ Set Clear Financial Intentions – Not Punishments

    Financial intentions focus on who you want to become and how you want to feel – not just what you want to do.

    For example:

    • “I want to feel peaceful when I check my bank account.”
    • “I want to be someone who saves consistently.”
    • “I want to feel proud of my money decisions.”

    From there, we build small, tangible goals that align with that intention. That’s the sweet spot.

    ✅ Build Micro Goals That Stack Into Momentum

    Instead of “Save $5,000 this year,” try:

    • “Transfer $100 every payday to my savings account.”
    • “Do 1 no-spend weekend per month.”
    • “Track my spending daily for 30 days.”

    These small actions feel doable and when done consistently, they change everything.

    ✅ Have a System – Not Just a Goal

    Anyone can write a goal. But what’s your system to get there?

    Here’s a basic system I teach inside my Financial Muscle Coaching:

    1. Weekly money check-ins (10 minutes)
    2. Monthly budget reviews
    3. Track 1 habit at a time (like spending or debt payments)
    4. Celebrate progress every month.

    Have a Money Budgeting System

    Systems create structure and structure creates success. Don’t wait – join the membership now and start living your best life from today.

    Join Financial Muscle Coaching Now

    #WhyDoResolutionsFail #HowToStickToFinancialGoals #WhyCantIKeepNewYearGoals #NewYearMoneyResolutionHelp #HowToMakeMoneyGoalsThatLast #MoneyGoalsNotResolutions #HowToStayMotivatedWithMoney #BreakTheCycleWithMoney #SmartFinancialGoals2025 #BuildBetterMoneyHabits #NewYearsResolutionFail #MoneyGoals2025 #FinancialGoalsThatStick #BudgetGoals #MoneyHabits #ResolutionReset #MoneyCoaching #FinancialMuscle #GoalSettingTips #SmartMoneyMoves 

    Mind Over Money: How to Rewrite Your Financial Story & Build a Breakthrough Mindset

    Mind Over Money: How to Rewrite Your Financial Story & Build a Breakthrough Mindset

    Let’s start with the truth:

    You can have the perfect budget, a great-paying job, even a savings plan, and still feel stuck financially.

    Why? Because if your mindset doesn’t change, your money won’t either.

    In this blog, we’re going to unpack:

    • The power of mindset in creating real financial change
    • How money stories are formed (and how to rewrite them)
    • Common mindset blocks that keep people stuck
    • Simple tools to build a breakthrough mindset
    • How this fits into your journey toward financial freedom

    Let’s dive in!

    ? What Is a Money Mindset (and Why Should You Care)?

    Your money mindset is your core belief system around money. It shapes how you:

    • Spend
    • Save
    • Earn
    • Invest
    • React in financial stress

    It’s the voice in your head that says:

    • “I’m just not good with money.”
    • “Money always slips through my fingers.”
    • “I have to work hard to survive.”

    Or, on the flip side:

    • “I’m in control of my finances.”
    • “I know how to make money work for me.”
    • “Wealth is available to me.”

    The difference? Mindset.

    This isn’t wishful thinking, this is neuroscience and behavioural psychology. What you believe impacts how you behave. And how you behave impacts your bank account.

    ? Where Do These Beliefs Come From?

    Most of our money beliefs are formed before age 7.

    You may have grown up hearing:

    • “Money doesn’t grow on trees.”
    • “We can’t afford that.”
    • “Rich people are greedy.”

    Without realising it, those phrases became part of your internal money script – even if they don’t serve you now.

    Other money stories come from:

    • Your parents’ relationship with money
    • Cultural or community influences
    • Early financial trauma (like debt, bankruptcy, poverty)

    Good news? You can rewrite the script.

    ? Common Money Mindset Blocks (And How They Show Up)

    If you’ve ever thought:

    • “As soon as I get ahead, something always knocks me back.”
    • “I don’t deserve to be wealthy.”
    • “I feel anxious just opening my banking app,”

    …you’re not alone.

    Here are 5 of the most common mindset blocks we see:

    1. Scarcity Thinking

    The belief that there’s never enough (time, money, opportunities). This leads to fear-based decisions and self-sabotage.

    2. Imposter Syndrome

    Feeling like you’re not smart or “good enough” to manage money well. You might under-earn or avoid taking risks.

    3. Fear of Success

    It sounds weird, but many fear what will change if they actually become successful.

    4. Guilt Around Wealth

    Especially common if you grew up in struggle or were taught that money = greed.

    5. Money Avoidance

    This shows up as procrastination, not checking accounts, or avoiding financial conversations.

    Getting Out of Debt Starts in Your Mind

    ✨ The Power of Rewriting Your Financial Story

    Here’s the deal: your current money story isn’t your final chapter.

    You can shift from:

    • “I’ll always be in debt” → “I’m learning how to manage and reduce my debt.”
    • “I’m terrible with money” → “I’m becoming more financially confident every day.”

    Just like you wouldn’t expect physical results without working out, you can’t expect financial change without working on your mindset.

    ? Simple Tools to Strengthen Your Money Mindset

    1. Awareness is Power

    Start by journaling or reflecting on your early money memories. What did you hear, see, or feel growing up?

    2. Affirmations That Stick

    Affirmations are powerful when they’re practiced consistently. Try these:

    • “I am safe and in control of my finances.”
    • “Every dollar I spend and save has purpose.”
    • “I deserve financial abundance.”

    3. Surround Yourself With Growth

    Follow financial educators, podcasts, and communities that reinforce positive beliefs about money.

    4. Set Micro-Goals

    Progress builds confidence. Start with tiny, achievable wins – like tracking your expenses or saving $10/week.

    5. Visualise the Outcome

    Spend 2 minutes a day visualising what your financially free life looks like. Your brain responds powerfully to visualisation.

    6. Join a Supportive Program

    A structured environment with accountability and coaching helps speed up your mindset shift.

    That’s exactly what we provide in the Financial Freedom Breakthrough Program, launching this September.

    ? The Role of Mindset in the Financial Freedom Diagram

    Let’s circle back to the diagram from Financial Management 101.

    If you’re stuck at the bottom (overwhelmed, struggling, surviving), it’s not just a numbers issue.

    It’s a belief issue.

    Mindset is the foundation that supports every other level:

    • Budgeting
    • Saving
    • Debt reduction
    • Credit health
    • Wealth building
    • Estate planning

    With the right mindset, these tools feel doable. Without it, even the best strategy will collapse.

    ? Real Talk: You Are NOT Broken

    Maybe you’ve made mistakes. Maybe you’ve felt stuck for years. Maybe you’re scared to even start.

    That doesn’t make you broken – it makes you human.

    Your past doesn’t define you. Your future is still yours to shape.

    And the first step? Believing you can.

    Working on your money mindset while paying off debt is so important.

    ? Ready to Rewrite Your Story?

    Here’s how to begin:

    1. Download our Free Money Mindset Workbook (coming soon)
    2. Join the waitlist for the Financial Freedom Breakthrough Program
    3. Share this post with someone who needs to hear it today

      ? Final Thoughts

      Money mindset isn’t fluff, it’s the fuel behind every breakthrough.

      If you want a different result, you need a different belief.

      You’re not meant to just survive. You’re meant to thrive.

      Let’s start believing in that version of you, and take action to bring it to life.

      Your Financial Freedom Breakthrough™
      Are You Ignoring Your Financial Safety Net? Why Wills & Estate Planning Matter (Even If You’re Young!)

      Are You Ignoring Your Financial Safety Net? Why Wills & Estate Planning Matter (Even If You’re Young!)

      Alright, friend… it’s time we talk about something that everyone needs, but almost no one wants to deal with.

      Wills. Estate Planning. Life insurance.

      Did your eyes just glaze over?

      Did you suddenly feel an overwhelming urge to click away or scroll to the fun stuff on Instagram?
      Stay with me, because this may just be one of the most important money conversations you’ll ever have. Here’s the hard truth:

      If you’re ignoring estate planning because you think it’s “only for rich people” or “something I can figure out later,” you’re playing a dangerous game with your financial future, and the people you love most.
      In this post, I’m going to:

      • Bust the biggest myths about wills and estate planning.
      • Show you why everyone (yes, even you!) needs a plan.
      • Break down exactly what you need to do – without confusing legal jargon.
      • Help you take simple, meaningful action to protect your future.

      And don’t worry, this isn’t going to be dry or boring.

      We’re going to make this approachable, empowering, and (dare I say?) a little fun. Because protecting your future should feel like an act of love and self-respect, not something you dread.

      ? Myth #1: “Estate Planning Is Only for Rich People”

      Let’s start here, because this myth is everywhere. When most people hear the phrase “estate planning,” they picture wealthy people with sprawling mansions, yachts, and family fortunes that need protecting. But here’s the truth: If you own anything – even a car, a bank account, or a pet – you have an estate.

      Estate planning isn’t just for millionaires. It’s for:

      • The young professional with a growing savings account.
      • The parent who wants to protect their kids.
      • The small business owner with assets tied to their company.
      • The renter with a car loan and a retirement fund.

      If you have money, possessions, dependents, or even digital assets – estate planning applies to you.

      If you own anything - even a car, a bank account, or a pet - you have an estate.

      ? Why Avoiding Estate Planning Could Cost You (Big Time)

      I get it – thinking about wills, death, and “what ifs” isn’t exactly a fun Friday night activity. But here’s the thing… Avoiding estate planning doesn’t make it go away. It just creates more chaos for the people you care about most. Without a will or estate plan in place:

      • The courts decide who gets your assets – and it may not align with your wishes.
      • Your loved ones could be tied up in legal battles for months (or even years).
      • Minor children could end up with a guardian chosen by the court – not you.
      • Your hard-earned money could get eaten up by legal fees, taxes, or other costs.

      In short, not planning can create stress, delays, and heartache at the worst possible time.

      But when you take just a little time to set up your financial safety net? You give your loved ones clarity, protection, and peace of mind.

      ? “But I’m Too Young for a Will!”

      Another common myth? Thinking you’re too young to need a will. Here’s a little truth bomb:

      Wills aren’t about age – they’re about responsibility.

      You may not think you need one yet, but ask yourself:

      • Do you have savings, retirement accounts, or life insurance?
      • Do you have pets who rely on you?
      • Do you own a car, home, or business?
      • Do you have people who depend on your income?
      • Do you have strong opinions about where your money should go if something happens to you?

      If you answered yes to any of those, it’s time to start planning. Remember—estate planning isn’t about expecting the worst. It’s about being prepared for whatever life throws your way.

      ✨ Estate Planning: It’s Not Just About Death – It’s About Life, Too!

      One of the most overlooked parts of estate planning? It’s not just about what happens after you’re gone. It also protects you while you’re alive, especially if you ever:

      • Become seriously ill.
      • Get injured and can’t manage your finances or healthcare decisions.

      Your estate plan can include documents like:

      • Power of Attorney: Designating someone you trust to manage your finances if you can’t.
      • Healthcare Directive: Outlining your wishes for medical treatment and end-of-life care.
      • Guardianship Designations: Naming who will care for your minor children if you’re unable to.

      These documents ensure your voice is heard – no matter what.

      ? What’s Actually Included in a Basic Estate Plan?

      Let’s strip away the legal jargon and break this down simply. Here’s what most people need in their estate plan:

      1. A Will

      This legal document spells out:

      • Who will inherit your assets (money, property, belongings, etc.).
      • Who will take care of your children or dependents (if applicable).
      • Who will manage your estate (called an executor)

      What To Include in A Basic Estate Plan

      2. Power of Attorney (POA)

      This gives someone legal authority to:

      • Handle your finances if you’re incapacitated.
      • Make decisions on your behalf if you can’t.

      3. Healthcare Directive (Living Will)

      This outlines your medical wishes if you’re unable to communicate them.

      4. Beneficiary Designations

      Certain accounts (like life insurance, retirement accounts, and some bank accounts) allow you to name a beneficiary directly. These override your will, so it’s crucial to keep them updated.

      5. Guardianship Designations (If Applicable)

      If you have minor children, this document names who you want to raise them if you’re unable to.

      Bonus: Trusts (Optional for Some)

      While not necessary for everyone, trusts can:

      • Help avoid probate (the legal process of validating a will).
      • Provide additional control over how and when assets are distributed.
      • Offer potential tax benefits.

      ? How to Get Started with Estate Planning (Without Feeling Overwhelmed)

      Deep breath – this doesn’t have to be complicated! Here’s how to start, step by step:

      Step 1: Take Inventory

      List all your:

      • Bank accounts
      • Retirement accounts
      • Investments
      • Properties
      • Vehicles
      • Insurance policies
      • Personal belongings of high value
      • Digital assets (crypto, social media, etc.)

      Step 2: Clarify Your Wishes

      Think about:

      • Who should inherit your assets?
      • Who do you trust to handle your finances and healthcare if needed?
      • Who would you want to care for your kids or pets?
      • Are there any charitable causes you’d like to support?

      Step 3: Get Legal Help (If Needed)

      While you can create simple wills online for a low cost, it’s often wise to consult an estate attorney, especially if:

      • You have significant assets.
      • You own a business.
      • You have a blended family or complex situation.

      Step 4: Communicate Your Plan

      This is the step most people skip, but it’s essential! Let your loved ones know:

      • That you’ve created an estate plan.
      • Where they can find the documents.
      • Who has been designated for certain roles.

      Transparency now avoids confusion later.

      Step 5: Review & Update Regularly

      Life changes – your estate plan should too. Revisit your documents anytime you:

      • Get married or divorced.
      • Have children.
      • Move to a new state (laws vary).
      • Experience major financial changes.

      ? But What If You Don’t Have Much to Leave Behind?

      Here’s a powerful truth: Estate planning isn’t just about leaving behind money – it’s about leaving behind clarity. Even if your financial picture feels “small” right now, your loved ones will still need to:

      • Handle your debts and bills.
      • Access your accounts.
      • Close out your digital presence.
      • Make healthcare decisions if needed.

      Having a clear plan ensures they can do so smoothly. Plus, it sends a strong message: “I respect myself and the people I care about enough to plan ahead.”

      ? Estate Planning = Empowerment, Not Fear

      I get it – this can all feel heavy. But here’s how I want you to reframe it:

      Estate planning isn’t about preparing for doom and gloom.

      It’s about:

      • Taking ownership of your life.
      • Protecting your family.
      • Making your wishes known.
      • Creating peace of mind, for you and for those you love.

      It’s one of the most profound acts of love and responsibility you can make.

      ? How This Connects to Your Financial Breakthrough

      In my Your Financial Freedom Breakthrough™ – 90 Day Money Makeover program, we don’t just focus on day-to-day money tasks like budgeting and debt. We go deeper, because true financial empowerment covers everything. That includes:

      • Building your savings.
      • Tackling your debt.
      • Creating an intentional spending plan.
      • AND making sure your financial house is in order with estate planning.

      Most programs skip this step, but I refuse to. Why? Because I’ve seen firsthand how having a financial safety net changes lives.

      In the program, you’ll:

      • Learn exactly what legal documents you need.
      • Get simple checklists to help you start (even if you’re a total beginner).
      • Be guided through tough but important questions with compassion and clarity.

      It’s all about making this process approachable, doable, and even empowering.

      ? Ready to Take Action? (Mini Challenge!)

      Let’s get you started today with a bite-sized action step.

      Estate Planning Mini Challenge:

      Make a list of ALL your current accounts and assets. Check the beneficiaries on your bank accounts and retirement funds. Update them if needed.

      Choose ONE document to tackle this month:

      • Will
      • Power of Attorney
      • Healthcare Directive

      Start with the easiest one for you. This tiny step will start creating massive peace of mind, and it’s easier than you think.

      ? Final Thoughts: Your Legacy Starts Now

      Here’s what I want you to remember: Estate planning isn’t just for “older” or “wealthy” people – it’s for everyone who wants to protect their future.

      You don’t need to do it all at once, but starting somewhere is powerful. This isn’t about fear – it’s about empowerment, peace of mind, and love.

      And if you’re ready to take this even further to finally build a money plan that covers everything from budgeting to wills and beyond, get ready. My Your Financial Freedom Breakthrough™ – 90 Day Money Makeover opens on September 10th, and it’s designed to help you:

      • Create lasting financial change.
      • Build a money system that works for your life.
      • Feel empowered, organised, and confident with your finances – once and for all.

      You’ve got this, and I’m cheering you on every step of the way.

      Your Financial Freedom Breakthrough™
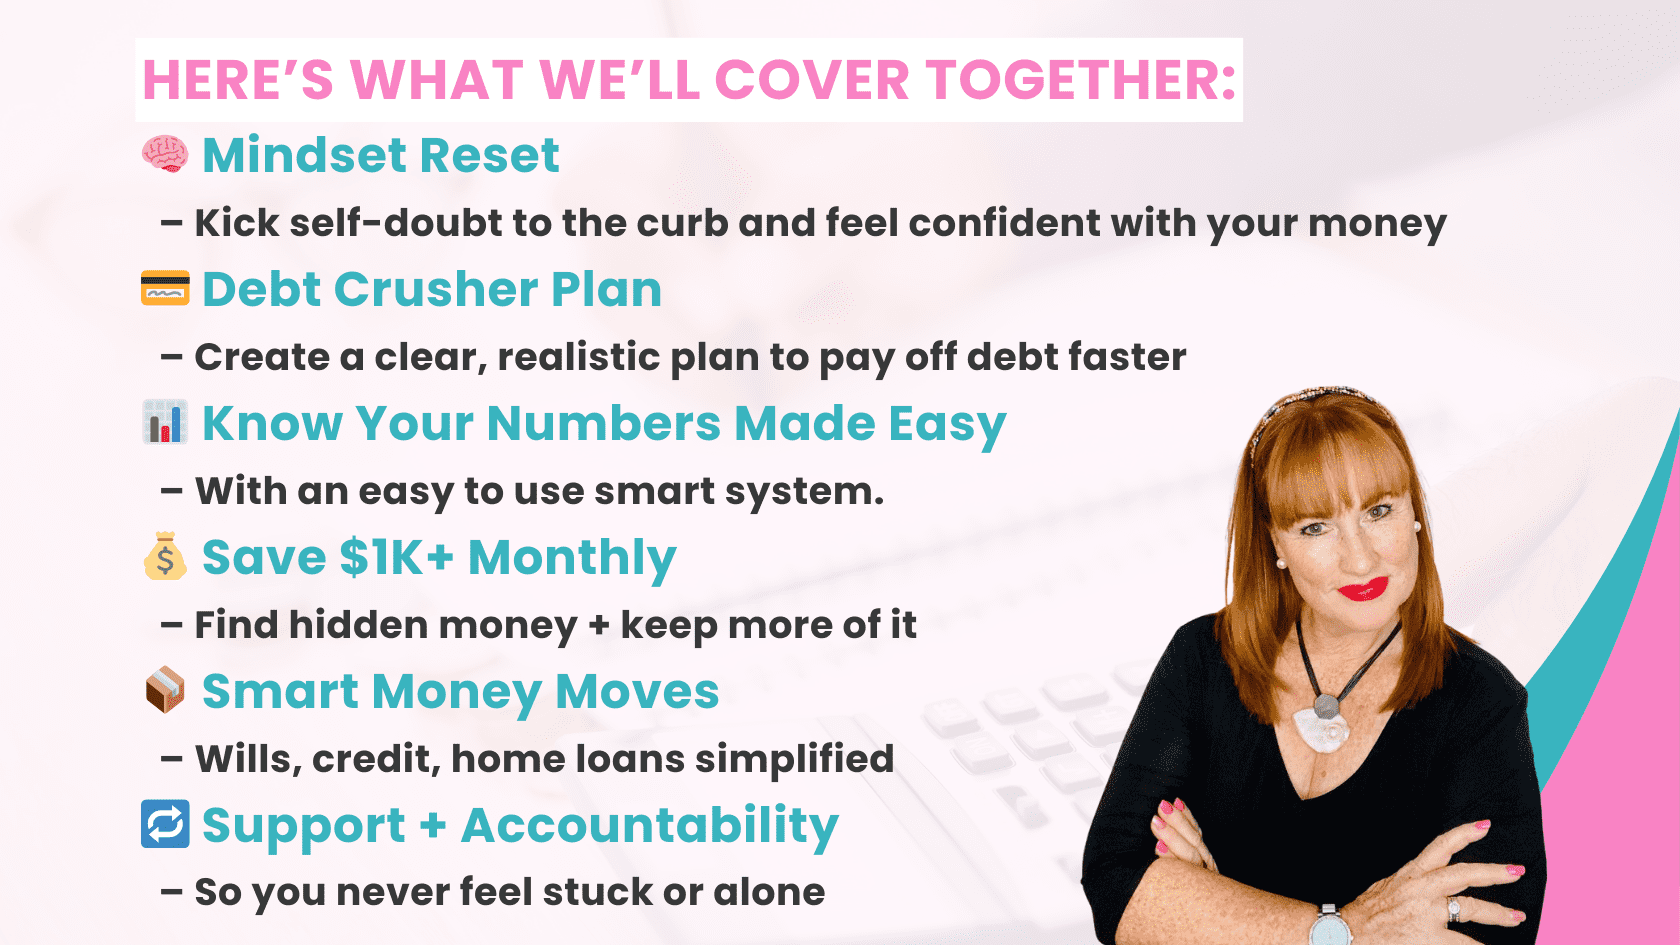
      Your Financial Freedom Breakthrough™ - Scope