Is Money Stress the Missing Piece in Your Wellbeing Strategy?

Is Money Stress the Missing Piece in Your Wellbeing Strategy?

You provide mental health support, but money is often part of the stress employees are carrying. Here’s how practical financial wellbeing education complements your EAP, without straying into personal advice.

We know how much thought goes into a wellbeing strategy. The EAP is in place. The mental health training has been rolled out. Leaders have been coached to check in on their people.

And still, something doesn’t quite add up. Engagement scores plateau. Absenteeism doesn’t shift the way you’d expect. People say they’re “fine” and clearly aren’t.

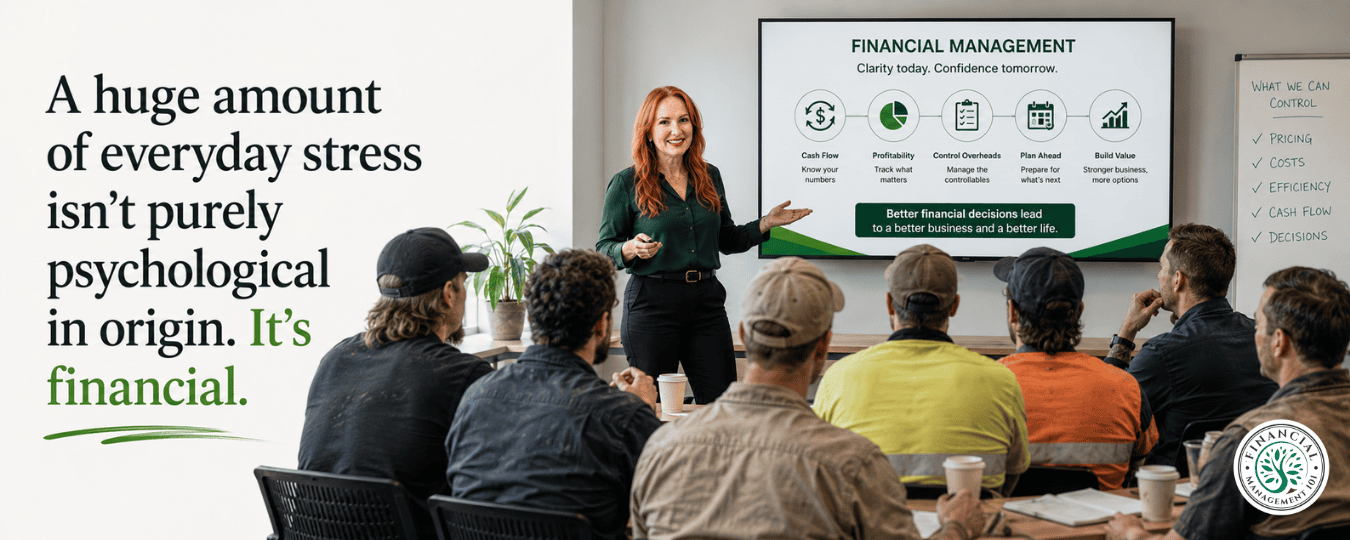
Here’s what often gets missed: a huge amount of everyday stress isn’t purely psychological in origin. It’s financial. And most wellbeing strategies aren’t built to touch it.

By the end of this, you’ll know why financial stress behaves differently to other workplace stressors, and how practical financial education sits alongside your EAP rather than competing with it.
Your employees don’t need another financial webinar.
They need personal, practical support that actually changes how they feel and what they do with their money.

Money stress doesn’t look like a “money” problem at work

Financial stress rarely walks into HR and announces itself. It shows up as distraction, short tempers, disengagement, or someone quietly declining opportunities that would help their career because the timing feels too risky.

It’s also one of the few stressors that follows people to work every single day, rather than arriving as a one-off event. A restructure or a difficult client eventually resolves. A mortgage rate rise, or not knowing where next month’s numbers land, doesn’t switch off at 9am.

Why your EAP alone doesn’t close this gap

Your EAP is doing exactly what it’s designed to do; professional, confidential support for people in genuine distress. That matters, and it isn’t in question here.

What an EAP isn’t built for is teaching everyday financial capability. Counselling can help someone process the anxiety money is causing them. It generally isn’t set up to help them understand their pay structure, build a spending plan, or feel confident having a money conversation with a partner.

That’s a different kind of support, practical, skill-based, and preventative rather than crisis-response.

Where financial wellbeing education fits

This is where financial wellbeing education does its work: building everyday money confidence and capability, in plain English, before things reach crisis point.

It’s general education, not personal advice. Nobody’s reviewing an individual’s mortgage or telling them what to do with their super. It’s giving people the foundations; how budgeting actually works, how debt behaves, how to read their own numbers, so they can make their own informed decisions.

Layered with an EAP, you get both ends covered: support for people who are already struggling, and education that helps prevent financial stress building into something bigger in the first place.

What this can look like in practice

Financial wellbeing education for workplaces can sit alongside existing programmes in a few different ways:

  • A standalone session or short series, run like any other professional development topic.
  • Content woven into an existing wellbeing calendar, alongside mental health and physical health initiatives.
  • A resource employees can return to in their own time, for privacy around a genuinely personal topic.

Done well, it’s positioned the same way physical or mental health education is a normal, non-judgemental part of supporting people, not a red flag that something’s wrong.

The Takeaway

A strong wellbeing strategy supports the whole person, and for most people, money is part of that picture whether it’s named or not. An EAP handles the crisis. Financial wellbeing education handles the everyday end, building the confidence and capability that helps prevent the crisis in the first place.

Together, they give your people a genuinely complete safety net, not just a mental health one.

If you’d like to explore what financial wellbeing education could look like for your team, we’d love to talk it through with you.
The Financial Wellbeing Solution Your People Deserve — and Your Workplace Needs

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess #EAP #EmployeeAssistanceProgram
#EntrepreneurMindset
 

Your First Quarter Report Card

Your First Quarter Report Card

July, August, September – done and dusted, more or less. So how’s the new financial year actually going? Not “how busy have you been.” How’s it going?

Most business owners can rattle off exactly how flat out they’ve been since July; the jobs, the clients, the late nights. Fewer can tell you how profitable they’ve been over the same stretch. And that gap between “flat out” and “actually ahead”, is exactly where a quick quarter check-in earns its keep. It’s the difference between a business that feels busy and a business you can actually prove is moving forward.

Nobody waits for the end-of-year school report to find out how a kid’s tracking. You check in along the way – a note home, a parent-teacher chat, a quiet word, and adjust before it becomes a bigger conversation. Your business deserves the same courtesy. Not a full audit, not a forensic dive into every transaction, just an honest look at the first three months of the new financial year, before you’re four quarters deep wondering where it all went and why the number at tax time doesn’t match the effort you know you put in.

Why most business owners skip this

It’s not laziness. It’s usually one of two things, either it feels like it’ll take hours you don’t have, or there’s a quiet fear of what it might show. Both of those assumptions tend to be wrong. This exercise takes less time than a coffee catch-up, and more often than not, the number is somewhere between “not as bad as I feared” and “better than I gave myself credit for.” The dread is almost always worse than the discovery.

Three questions, one cup of tea

Three questions, one cup of tea

Did revenue roughly match what you were hoping for? Doesn’t need to be precise; ahead, on track, or behind is enough of an answer for now. And if you realise you never actually set a target for the quarter, that’s not a failure, it’s just a perfectly good place to start next time. You can’t be ahead or behind a target that doesn’t exist.

Did profit follow revenue, or did it quietly wander off on its own? This is the one that catches people out most often, and it’s the one I see most in this line of work. Revenue climbs, everyone’s thrilled, the calendar’s fuller than ever and then the bank balance doesn’t quite reflect it, because costs crept up right alongside the growth without anyone clocking it. Materials went up. A subcontractor’s rate went up. You took on a bit more admin help. None of it felt like a big decision at the time, but added together it’s eaten the extra revenue and then some. If you’ve felt busier than ever this quarter but the numbers don’t quite match the feeling, this is usually why.

What’s one thing you’d do differently heading into the next quarter? Not five things, just one! Trying to fix everything at once is how good intentions turn into nothing changing at all. Maybe it’s pricing, which almost every business owner I meet is quietly undercharging on. Maybe it’s chasing invoices a little sooner instead of letting them drift. Maybe it’s finally looking at where the money’s actually going instead of guessing based on vibes and a general sense of dread. Pick the lever that would move things most, and leave the rest for next quarter’s version of this exercise.

What to do with what you find

If the quarter came in ahead, resist the urge to immediately spend the difference on something exciting. Sit with it for a bit. Ask whether it’s a genuine trend or a one-off good stretch before you build plans around it. If it came in behind, resist the opposite urge, the spiral into “the whole business is failing.” One quarter is one quarter. It’s a data point, not a verdict. The value isn’t in the number itself, it’s in what the number tells you to look at next.

Why quarterly, specifically

A quarter is a genuinely good length of time to check in on; long enough to see a real pattern rather than a one-off blip, short enough to actually change course while it still matters. Check monthly and you risk reacting to noise, a slow week that means nothing, a good week that means nothing either. Check yearly and you find out too late to do much about it. Quarterly sits right in the sweet spot, giving you enough information to trust it, and enough time left in the year to actually act on it.

The business owners I see making calmer, more confident decisions are almost always the ones checking in quarterly, not just at tax time when the accountant delivers the number and there’s nothing left to do but accept it. Checking quarterly puts you back in the driver’s seat of your own financial year, rather than a passenger finding out where you ended up after the fact.

If you’d like a proper look under the bonnet, the CEO Dashboard gives you full visibility on exactly how the quarter really went not the guessed version, the real one.

Turning it into a rhythm

The businesses that get the most out of this aren’t doing anything clever, they’ve just made it a rhythm rather than a rescue mission. Same week each quarter. Same three questions. Same short list of actions afterwards. It stops being a big, dreaded event and becomes something closer to a habit, the business equivalent of a regular check-up rather than an emergency room visit.

If this is the first time you’ve done a proper quarter check-in, don’t worry about making it perfect. The value isn’t in precision, it’s in the act of actually stopping to look, on a schedule, instead of only looking when something’s gone wrong enough to force your hand.

Setting yourself up for next quarter

Before you close the laptop on this exercise, write down one number you’ll check again in three months. Just one. Revenue, profit margin, average invoice value, whatever feels most relevant to where you are right now. Having that one number in mind gives the next quarter’s check-in a head start, because you’ll already know what you’re comparing against instead of starting from scratch each time.

Small, consistent check-ins beat big, occasional audits every time. That’s true of your car, your health, and it’s absolutely true of your business.

The CEO Dashboard

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess
#EntrepreneurMindset


R U OK? (The Question You Never Ask Yourself)

R U OK? (The Question You Never Ask Yourself)

On September 10, most of Australia will be asking each other “R U OK?” Workplaces will run morning teas. There’ll be yellow everywhere. It’s a genuinely good day, and I’m glad it exists – it’s done a lot for getting these conversations out into the open where they belong, after years of them staying firmly behind closed doors.

But here’s the question I actually want to ask you, business owner to business owner… when’s the last time you asked yourself that?

We’re brilliant at checking in on everyone else. Staff, clients, family, that one supplier who always sounds a bit frazzled on the phone. But most business owners I talk to haven’t had an honest conversation with themselves in months. We’re too busy holding everything together to notice we might not be, ourselves. We’re the ones people come to when something’s gone wrong, which means we’ve quietly trained everyone around us, including ourselves to believe we don’t need checking on.

Running a business is one of the loneliest jobs going, if I’m honest. You’re the one everyone brings their problems to. There’s rarely anyone bringing you theirs, asking how you’re actually tracking underneath it all. Even the people who love you tend to ask “how’s the business going?” rather than “how are you going?” and those are very different questions with very different answers.

The performance of “fine”

There’s a particular skill business owners develop without meaning to, the ability to say “yeah, good, flat out” in a completely convincing tone while privately feeling anything but. It becomes automatic. Someone asks how you’re going at the school pickup, at the football, at a client meeting, and out it comes before you’ve even thought about it. Over time, that automatic answer starts to replace the honest one, even in your own head. You stop checking because you’ve gotten so good at performing that you don’t seem to need it.

So today, let’s flip it. Three questions, and actual permission to answer them properly, without the reflexive “yeah, good, flat out” that we all give without thinking.

Am I okay, or am I just coping?

There’s a real difference. Coping looks like getting through the week in one piece, ticking things off, keeping the wheels on. Okay looks like genuinely enjoying the thing you built, feeling proud of it, curious about where it’s going, energised rather than depleted by it. If you’ve been in coping mode for a while now, that’s worth noticing, not brushing off with “it’s just a busy season,” because busy seasons have a habit of becoming permanent if nobody names them.

There’s no shame in “coping” as an honest answer. It’s often the truest thing a business owner has said about themselves in months, once they finally stop and let themselves say it. The shame only comes from pretending otherwise for too long.

What am I carrying that I haven't said out loud?
For a lot of business owners, it's the money. The gap between what the business brings in and what it feels like it should be bringing in by now, given how hard you're working.

What am I carrying that I haven’t said out loud?

For a lot of business owners, it’s the money. The gap between what the business brings in and what it feels like it should be bringing in by now, given how hard you’re working. That gap is heavy to carry on your own, and you really don’t have to. I’ve had conversations with business owners who’ve been sitting on that particular worry for years, silently, because it felt embarrassing to say out loud, like admitting it meant admitting they’d failed at something. It’s not embarrassing. It’s incredibly common, and it’s fixable once it’s actually spoken about, usually far more fixable than the years of silent worry suggested.

Sometimes what people are carrying isn’t even the money itself, it’s the fear of what the money says about them. That’s a heavier load than the actual numbers ever are.

Who’s actually in my corner?

Not staff. Not clients. I mean the people who ask how you’re going, not just how the business is going. If that list is short, that’s your sign; a mentor, a community, or even just a standing coffee with someone who genuinely gets what this life is like. Business ownership can be surprisingly isolating even when you’re surrounded by people all day, because being surrounded by people isn’t the same as being known by them.

The physical signs worth noticing

Sometimes the “am I okay” question is easier to answer by looking at the body rather than the mind. Are you sleeping properly, or lying awake running through tomorrow’s problems? Are you short-tempered with people who don’t deserve it? Have you stopped doing the small things that used to recharge you – the walk, the round of golf, the Sunday paper, because there’s “no time”? These aren’t small details. They’re often the clearest signal available that the tank’s getting low, well before the mind is ready to admit it in so many words.

It’s okay to not have the answer yet

If you sat with those three questions and didn’t love your answers, that’s not a failure, that’s information. The whole point of asking is so you can actually do something with what you find, rather than carrying it around unexamined for another six months. Awareness on its own doesn’t fix anything, but it’s the step that has to come first, and it’s the step most business owners skip entirely because it’s uncomfortable.

You can’t run a healthy business from an empty tank. Checking in on yourself isn’t soft, whatever the old-school hustle crowd would have you believe, it’s strategy, plain and simple. A business owner who’s running on empty makes worse decisions, snaps more easily, and enjoys less of what they’ve built. None of that helps the business either – it’s not a trade-off between looking after yourself and looking after the business. They’re the same job.

And if part of what’s weighing on you is the money side of things, that’s exactly what The Edge exists for. A place where you’re not carrying it solo, surrounded by other business owners asking each other the real questions instead of the polite ones.

Join The Edge: https://financialmanagement101.com.au/work-with-karen/the-edge/

And if today’s the day you actually need to talk to someone, Lifeline is on 13 11 14, any hour, no appointment needed.

What to do once you’ve asked yourself

Asking the question is the easy part, once you’ve actually made yourself do it. The harder part is what comes next, because most business owners are excellent at identifying a problem and then filing it away under “deal with that eventually.” So if any of the three questions above landed a bit close to home, don’t let it end there.

Pick one small thing. Not a complete overhaul of your life, not a dramatic announcement to everyone that you’re “making changes.” One small thing; a call to a friend you’ve been meaning to make, an actual look at the money situation you’ve been avoiding, a boundary around one evening a week that’s just yours. Small, specific, doable this week, not “someday.”

Business owners checking in on business owners

Business owners checking in on business owners

There’s a particular kind of relief that comes from talking to someone else who genuinely understands what this life involves – the highs that nobody else quite gets excited about the way you do, and the lows that nobody else quite understands the weight of either. Friends and family love you, but unless they’ve run a business themselves, there’s a layer of it they simply can’t relate to, however much they try.

That’s part of why community matters so much here. Not a support group in the clinical sense, just other people in the same boat, who ask “how are you really going” and actually mean it, who’ve had the sleepless nights over cash flow and the quiet pride over a client win, and who get it without you having to explain the whole backstory first.

THE EDGE Membership

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess
#EntrepreneurMindset


Your Team Might Look Fine – But Financial Stress Could Be Costing More Than You Think

Your Team Might Look Fine – But Financial Stress Could Be Costing More Than You Think

“They seem fine.”

It is one of the most common assumptions leaders make.
And to be fair, it is an easy one to make.

Most employees are not walking into work announcing that they are worried about bills, debt, interest rates, or the rising cost of everyday life.

They keep going.
They keep performing.
They keep pushing through.

But financial stress has a way of showing up quietly.

It can look like a distraction.
Low energy.
Mood changes.
Reduced confidence.
Increased absenteeism.
Burnout.
Or eventually, a resignation that seems to come out of nowhere.

The employee looked fine.
But they were not fine.

The silent pressure many employees are carrying

The current financial climate is affecting people in deeply personal ways.
Even capable, high-performing employees can be under enormous pressure.

When money stress builds, people can feel:

  • mentally overloaded
  • emotionally flat
  • ashamed to ask for help
  • trapped in a cycle of stress and avoidance
  • worried about keeping up with household costs
  • fearful about debt, repayments, or unexpected expenses

And because money is still a sensitive topic, many employees suffer in silence.

That silence can be expensive.

The current financial climate is affecting people in deeply personal ways.
Even capable, high-performing employees can be under enormous pressure.

Why this is bigger than employee perks

Free lunches, social events, and workplace rewards all have their place.
But they do not solve financial anxiety.

When someone is lying awake worrying about bills, a pizza party is not going to restore their peace of mind.

This is why financial wellbeing deserves more attention inside workplaces.
It addresses a real problem that affects people’s everyday lives and their capacity to function well at work.

It is practical. It is human. And right now, it is incredibly relevant.

What financial wellbeing support actually does

A strong financial wellbeing approach helps employees move from stress and confusion to clarity and confidence.

That might involve helping them:

  • understand where their money is going
  • create simple systems that reduce overwhelm
  • identify savings opportunities they have missed
  • tackle debt with a clearer plan
  • improve money habits and mindset
  • feel more hopeful and less stuck

Notice that this is not about judgement. It is about support.

Financial pressure can affect anyone. The goal is not to shame people for needing help. The goal is to give them tools that genuinely make life feel more manageable.

What employers gain when they take this seriously

When businesses support staff with financial wellbeing, the impact can ripple through the whole workplace.

You may see:

  • better focus and engagement
  • increased productivity
  • lower staff turnover
  • stronger trust and loyalty
  • reduced burnout risk
  • a more supportive workplace culture

People remember employers who support them through hard seasons.
Not just with words, but with meaningful action.

Reassurance is part of support

Let’s pause here for something important.

If you are an employee feeling the pressure right now, please hear this:

You are not weak.
You are not bad with money just because things feel hard.
You are not the only one feeling stretched.

This season may be challenging, but it does not define you.
With the right support, practical tools, and small consistent changes, things can improve.

And if you are an employer reading this, never underestimate how powerful it is to create a workplace where people feel safe to get support before they hit breaking point.

    Reassurance is part of support

    Support before crisis is the smarter move

    Too often, workplaces respond after the damage is done.
    After the burnout.
    After the resignation.
    After the drop in performance.
    After the personal crisis spills into professional life.

    But early support changes that.

    When businesses proactively offer financial wellbeing resources, they help staff build resilience before the pressure becomes overwhelming.
    That is better for the employee and better for the organisation.

    A more compassionate and practical workplace benefit

    There is a reason financial wellbeing is becoming such an important conversation.
    It sits at the intersection of performance, retention, mental wellbeing, and culture.

    It is not about fixing everything overnight.
    It is about giving people a starting point.
    A plan.
    A sense that they are not alone.
    A pathway back to confidence.

    And in uncertain times, that kind of support matters more than ever.

    My Financial Wellbeing Program helps workplaces support staff with practical money tools, confidence-building education, and real guidance that reduces stress and strengthens wellbeing.

    Because when your people feel better about money, they often feel better at work too.

    And that is good for everyone.

    Financial Wellbeing Program

    #HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings 


    How Can I Rebuild My Confidence After Making a Financial Mistake or Falling Behind on My Budget?

    How Can I Rebuild My Confidence After Making a Financial Mistake or Falling Behind on My Budget?

    We’ve all had that moment.

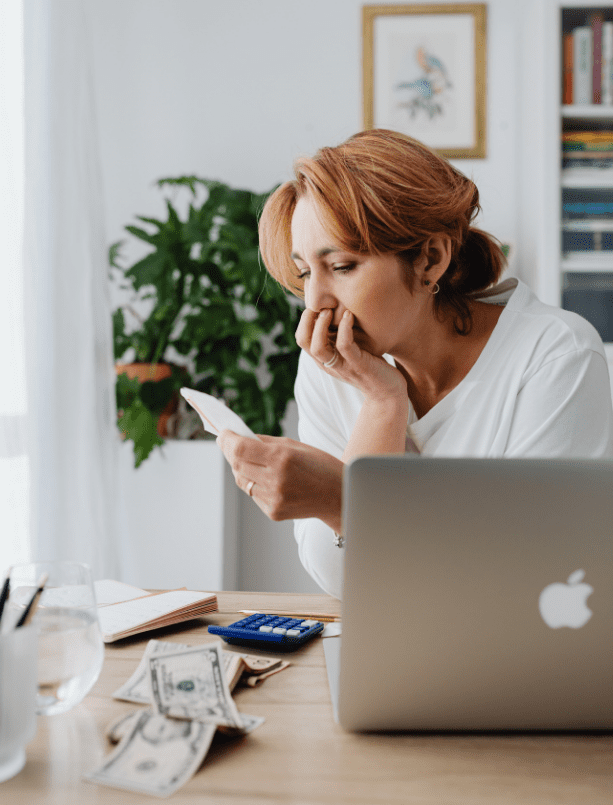
    You check your bank account… and it’s lower than you thought.
    You open your credit card bill… and it’s higher than you expected.
    You look at your budget… and realse you haven’t followed it for two weeks.

    Cue the shame spiral.

    If you’ve recently made a money mistake – or you just feel behind – I want you to know this:

    You are not alone.
    You are not a failure.
    And you are absolutely capable of bouncing back stronger.

    This blog will walk you through how to move from guilt to growth, and rebuild your confidence one step at a time.

    1. Separate Your Self-Worth from Your Net Worth

    First and foremost: you are not your bank balance.

    Your financial missteps don’t make you “bad with money.” They make you human.

    Whether you overspent, ignored your budget, or slipped back into old habits, it doesn’t define who you are. It’s a moment – not a life sentence.

    Start here:

    • Remind yourself: “I am capable of change.”
    • Reflect on a past financial win, no matter how small

    Say out loud: “I forgive myself. I’m ready to move forward.”

    2. Get Honest (Without the Shame)

    Let’s name what happened – not to beat yourself up, but to take your power back.

    Ask yourself:

    • What did I spend that I hadn’t planned for?
    • Did I avoid tracking or checking in with my money?
    • Did I say “yes” to things I couldn’t afford?

    Write it all down. You’re not here to judge yourself – just to gain clarity so you can move forward with purpose.

    3. Understand What Triggered the Slip-Up

    There’s always a “why” behind every money misstep mand understanding it is key to change.

    Common triggers:

    • Emotional spending (boredom, stress, celebration)
    • People-pleasing (saying yes to things out of guilt)
    • Lack of planning (unexpected expenses you didn’t prep for)
    • Old money stories (like “I’ll never get ahead anyway”)

    Identifying the trigger gives you a new layer of awareness and that’s when real change begins.

    4. Reset with a Micro-Goal

    When your confidence is shaken, the best thing you can do is create a tiny win that rebuilds momentum.

    Here are some examples:

    • Track your spending for the next 3 days
    • Create a mini budget just for this week
    • Make one extra payment toward your credit card
    • Pause one subscription and save the money instead

    Success is a series of small, intentional steps. Start with one.

    Create a mini budget for this week

    5. Watch Your Words (They Matter More Than You Think)

    Your internal dialogue becomes your financial reality.

    Let’s flip the script:

    ❌ “I’m terrible with money.”
    ✅ “I’m learning how to manage my money better every day.”
    ❌ “I’ll never get out of debt.”
    ✅ “Every payment I make moves me closer to freedom.”
    ❌ “I can’t stick to a budget.”
    ✅ “I’m figuring out a system that works for me.”

    Language matters. Speak like someone who’s growing because you are.

    6. Track Progress, Not Perfection

    You don’t have to get everything right to be making progress. Celebrate the fact that:

    • You noticed the slip-up
    • You chose to stop and reflect
    • You’re taking action now

    That’s what winning with money actually looks like.

    Make a habit of reflecting each month:

    • What went well?
    • Where did I struggle?

    • What can I adjust?

    And remember: even showing up for your finances when it’s hard is worth celebrating.

    7. Lean Into Support – Don’t Do This Alone

    Shame thrives in isolation. Confidence grows in community.

    Find a space where:

    • You can ask questions without feeling judged
    • You can share your wins and struggles
    • You can be held accountable to your goals

    That’s exactly what Financial Muscle Coaching is a coaching and accountability space, where we normalise setbacks and celebrate bounce-backs.

    Inside the membership, you’ll find structure, strategy, and support – all in one place.

    8. Build Your Financial Muscle, One Rep at a Time

    Rebuilding financial confidence is like building physical strength – it happens one rep at a time.

    One decision to check your balance.
    One habit of tracking your spending.
    One conversation where you ask for help instead of hiding.
    One payment that moves you forward.

    You don’t need to leap – you just need to lift. And every lift makes you stronger.

    Final Thoughts

    Mistakes are part of the journey – not the end of it.

    You are not behind. You are not bad with money. And you don’t have to do this perfectly to make progress.

    Every time you choose to come back – to review, reflect, and reset – you’re rebuilding your confidence.

    You’re showing yourself what you’re made of.
    And you’re writing a new money story that’s rooted in self-trust, resilience, and growth.

    You’ve got this. And I’m right here cheering you on.

    ? Join Financial Muscle Coaching

    If you’re tired of navigating your money alone – or beating yourself up every time you slip – Financial Muscle Coaching is the place for you.

    In this weekly coaching space, you’ll get:
    ✅ Encouragement instead of criticism
    ✅ Clear, doable action plans that meet you where you are
    ✅ Real accountability to build habits and confidence that last

    No more shame. No more silence. Just strength, strategy, and steady growth.

    Join Financial Muscle Coaching Now

    #HowToChangeMoneyMindset #ResetMyMoneyBeliefs #BuildFinancialConfidence #MoneyMindsetHelp #FinancialMindsetCoaching #HowToFeelBetterAboutMoney #WhyDoIFeelStressedAboutMoney #NewYearMoneyMindset #MoneyMindsetReset2025 #PositiveMoneyBeliefs #MoneyMindset #FinancialFreedomJourney #MoneyCoach #BudgetMindset #AbundanceMindset