Is Money Stress the Missing Piece in Your Wellbeing Strategy?

Is Money Stress the Missing Piece in Your Wellbeing Strategy?

You provide mental health support, but money is often part of the stress employees are carrying. Here’s how practical financial wellbeing education complements your EAP, without straying into personal advice.

We know how much thought goes into a wellbeing strategy. The EAP is in place. The mental health training has been rolled out. Leaders have been coached to check in on their people.

And still, something doesn’t quite add up. Engagement scores plateau. Absenteeism doesn’t shift the way you’d expect. People say they’re “fine” and clearly aren’t.

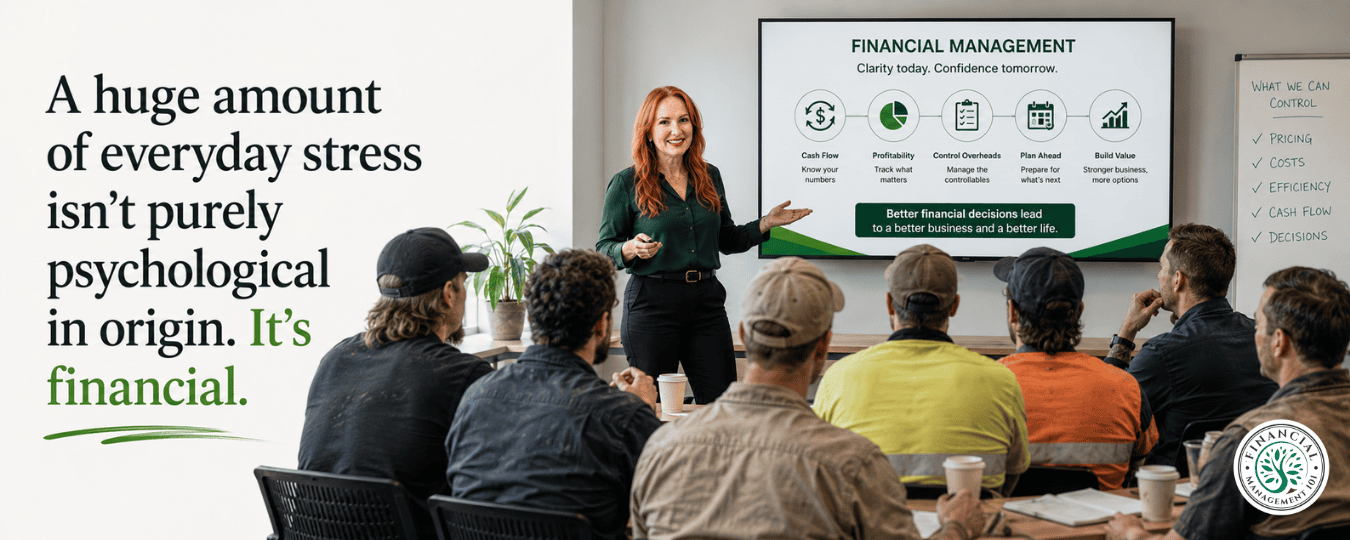
Here’s what often gets missed: a huge amount of everyday stress isn’t purely psychological in origin. It’s financial. And most wellbeing strategies aren’t built to touch it.

By the end of this, you’ll know why financial stress behaves differently to other workplace stressors, and how practical financial education sits alongside your EAP rather than competing with it.
Your employees don’t need another financial webinar.
They need personal, practical support that actually changes how they feel and what they do with their money.

Money stress doesn’t look like a “money” problem at work

Financial stress rarely walks into HR and announces itself. It shows up as distraction, short tempers, disengagement, or someone quietly declining opportunities that would help their career because the timing feels too risky.

It’s also one of the few stressors that follows people to work every single day, rather than arriving as a one-off event. A restructure or a difficult client eventually resolves. A mortgage rate rise, or not knowing where next month’s numbers land, doesn’t switch off at 9am.

Why your EAP alone doesn’t close this gap

Your EAP is doing exactly what it’s designed to do; professional, confidential support for people in genuine distress. That matters, and it isn’t in question here.

What an EAP isn’t built for is teaching everyday financial capability. Counselling can help someone process the anxiety money is causing them. It generally isn’t set up to help them understand their pay structure, build a spending plan, or feel confident having a money conversation with a partner.

That’s a different kind of support, practical, skill-based, and preventative rather than crisis-response.

Where financial wellbeing education fits

This is where financial wellbeing education does its work: building everyday money confidence and capability, in plain English, before things reach crisis point.

It’s general education, not personal advice. Nobody’s reviewing an individual’s mortgage or telling them what to do with their super. It’s giving people the foundations; how budgeting actually works, how debt behaves, how to read their own numbers, so they can make their own informed decisions.

Layered with an EAP, you get both ends covered: support for people who are already struggling, and education that helps prevent financial stress building into something bigger in the first place.

What this can look like in practice

Financial wellbeing education for workplaces can sit alongside existing programmes in a few different ways:

  • A standalone session or short series, run like any other professional development topic.
  • Content woven into an existing wellbeing calendar, alongside mental health and physical health initiatives.
  • A resource employees can return to in their own time, for privacy around a genuinely personal topic.

Done well, it’s positioned the same way physical or mental health education is a normal, non-judgemental part of supporting people, not a red flag that something’s wrong.

The Takeaway

A strong wellbeing strategy supports the whole person, and for most people, money is part of that picture whether it’s named or not. An EAP handles the crisis. Financial wellbeing education handles the everyday end, building the confidence and capability that helps prevent the crisis in the first place.

Together, they give your people a genuinely complete safety net, not just a mental health one.

If you’d like to explore what financial wellbeing education could look like for your team, we’d love to talk it through with you.
The Financial Wellbeing Solution Your People Deserve — and Your Workplace Needs

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess #EAP #EmployeeAssistanceProgram
#EntrepreneurMindset
 

R U OK? (The Question You Never Ask Yourself)

R U OK? (The Question You Never Ask Yourself)

On September 10, most of Australia will be asking each other “R U OK?” Workplaces will run morning teas. There’ll be yellow everywhere. It’s a genuinely good day, and I’m glad it exists – it’s done a lot for getting these conversations out into the open where they belong, after years of them staying firmly behind closed doors.

But here’s the question I actually want to ask you, business owner to business owner… when’s the last time you asked yourself that?

We’re brilliant at checking in on everyone else. Staff, clients, family, that one supplier who always sounds a bit frazzled on the phone. But most business owners I talk to haven’t had an honest conversation with themselves in months. We’re too busy holding everything together to notice we might not be, ourselves. We’re the ones people come to when something’s gone wrong, which means we’ve quietly trained everyone around us, including ourselves to believe we don’t need checking on.

Running a business is one of the loneliest jobs going, if I’m honest. You’re the one everyone brings their problems to. There’s rarely anyone bringing you theirs, asking how you’re actually tracking underneath it all. Even the people who love you tend to ask “how’s the business going?” rather than “how are you going?” and those are very different questions with very different answers.

The performance of “fine”

There’s a particular skill business owners develop without meaning to, the ability to say “yeah, good, flat out” in a completely convincing tone while privately feeling anything but. It becomes automatic. Someone asks how you’re going at the school pickup, at the football, at a client meeting, and out it comes before you’ve even thought about it. Over time, that automatic answer starts to replace the honest one, even in your own head. You stop checking because you’ve gotten so good at performing that you don’t seem to need it.

So today, let’s flip it. Three questions, and actual permission to answer them properly, without the reflexive “yeah, good, flat out” that we all give without thinking.

Am I okay, or am I just coping?

There’s a real difference. Coping looks like getting through the week in one piece, ticking things off, keeping the wheels on. Okay looks like genuinely enjoying the thing you built, feeling proud of it, curious about where it’s going, energised rather than depleted by it. If you’ve been in coping mode for a while now, that’s worth noticing, not brushing off with “it’s just a busy season,” because busy seasons have a habit of becoming permanent if nobody names them.

There’s no shame in “coping” as an honest answer. It’s often the truest thing a business owner has said about themselves in months, once they finally stop and let themselves say it. The shame only comes from pretending otherwise for too long.

What am I carrying that I haven't said out loud?
For a lot of business owners, it's the money. The gap between what the business brings in and what it feels like it should be bringing in by now, given how hard you're working.

What am I carrying that I haven’t said out loud?

For a lot of business owners, it’s the money. The gap between what the business brings in and what it feels like it should be bringing in by now, given how hard you’re working. That gap is heavy to carry on your own, and you really don’t have to. I’ve had conversations with business owners who’ve been sitting on that particular worry for years, silently, because it felt embarrassing to say out loud, like admitting it meant admitting they’d failed at something. It’s not embarrassing. It’s incredibly common, and it’s fixable once it’s actually spoken about, usually far more fixable than the years of silent worry suggested.

Sometimes what people are carrying isn’t even the money itself, it’s the fear of what the money says about them. That’s a heavier load than the actual numbers ever are.

Who’s actually in my corner?

Not staff. Not clients. I mean the people who ask how you’re going, not just how the business is going. If that list is short, that’s your sign; a mentor, a community, or even just a standing coffee with someone who genuinely gets what this life is like. Business ownership can be surprisingly isolating even when you’re surrounded by people all day, because being surrounded by people isn’t the same as being known by them.

The physical signs worth noticing

Sometimes the “am I okay” question is easier to answer by looking at the body rather than the mind. Are you sleeping properly, or lying awake running through tomorrow’s problems? Are you short-tempered with people who don’t deserve it? Have you stopped doing the small things that used to recharge you – the walk, the round of golf, the Sunday paper, because there’s “no time”? These aren’t small details. They’re often the clearest signal available that the tank’s getting low, well before the mind is ready to admit it in so many words.

It’s okay to not have the answer yet

If you sat with those three questions and didn’t love your answers, that’s not a failure, that’s information. The whole point of asking is so you can actually do something with what you find, rather than carrying it around unexamined for another six months. Awareness on its own doesn’t fix anything, but it’s the step that has to come first, and it’s the step most business owners skip entirely because it’s uncomfortable.

You can’t run a healthy business from an empty tank. Checking in on yourself isn’t soft, whatever the old-school hustle crowd would have you believe, it’s strategy, plain and simple. A business owner who’s running on empty makes worse decisions, snaps more easily, and enjoys less of what they’ve built. None of that helps the business either – it’s not a trade-off between looking after yourself and looking after the business. They’re the same job.

And if part of what’s weighing on you is the money side of things, that’s exactly what The Edge exists for. A place where you’re not carrying it solo, surrounded by other business owners asking each other the real questions instead of the polite ones.

Join The Edge: https://financialmanagement101.com.au/work-with-karen/the-edge/

And if today’s the day you actually need to talk to someone, Lifeline is on 13 11 14, any hour, no appointment needed.

What to do once you’ve asked yourself

Asking the question is the easy part, once you’ve actually made yourself do it. The harder part is what comes next, because most business owners are excellent at identifying a problem and then filing it away under “deal with that eventually.” So if any of the three questions above landed a bit close to home, don’t let it end there.

Pick one small thing. Not a complete overhaul of your life, not a dramatic announcement to everyone that you’re “making changes.” One small thing; a call to a friend you’ve been meaning to make, an actual look at the money situation you’ve been avoiding, a boundary around one evening a week that’s just yours. Small, specific, doable this week, not “someday.”

Business owners checking in on business owners

Business owners checking in on business owners

There’s a particular kind of relief that comes from talking to someone else who genuinely understands what this life involves – the highs that nobody else quite gets excited about the way you do, and the lows that nobody else quite understands the weight of either. Friends and family love you, but unless they’ve run a business themselves, there’s a layer of it they simply can’t relate to, however much they try.

That’s part of why community matters so much here. Not a support group in the clinical sense, just other people in the same boat, who ask “how are you really going” and actually mean it, who’ve had the sleepless nights over cash flow and the quiet pride over a client win, and who get it without you having to explain the whole backstory first.

THE EDGE Membership

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess
#EntrepreneurMindset


The Emergency Fund Isn’t Optional – How to Build One Without Feeling Broke (and why it changes everything)

The Emergency Fund Isn’t Optional – How to Build One Without Feeling Broke (and why it changes everything)

Let’s talk about the one money habit that turns chaos into calm faster than almost anything else:

An emergency fund.

Now before you roll your eyes and think, “Karen, I knowww… but I can barely afford groceries,” stay with me.

Because I’m not about to tell you to magically save three months of expenses overnight, live on rice and sadness, and stop enjoying life.

That’s not financial education – that’s financial punishment. 😅

What I am going to do is show you how to build an emergency fund in a way that feels doable, realistic, and actually sticks… even if money is tight.

And here’s why this matters:

An emergency fund isn’t just “money in an account.”
It’s peace, options, and less stress when life does what life does best… surprise you at the worst possible time.

So let’s get your financial house in order by building the foundation that stops everything from wobbling.

Why the Emergency Fund Is Non-Negotiable (Even If You Have Debt)

I want you to imagine your finances like a house.

If your foundation is cracked, everything else feels unstable:

  • you can’t plan properly
  • you can’t relax
  • you’re constantly bracing for impact
  • and one unexpected bill can knock you sideways

An emergency fund is the foundation.

It stops you from:

  • using credit cards “just this once”
  • grabbing BNPL for essentials
  • borrowing from family
  • draining your savings every time something happens
  • feeling like you’re always behind

Even if you’re paying down debt, you still need a buffer.
Because without one, every emergency becomes more debt… and that cycle is exhausting.

An Emergency Fund Is Non-Negotiable Even If You Have Debt

The Biggest Myth: “I’ll Start When I Have More Money”

This is the #1 reason people delay emergency savings.

They think:

  • “I’ll start when I get a pay rise.”

  • “I’ll start when the kids are older.”

  • “I’ll start when the cost of living calms down.” (lol… remember calm?)

  • “I’ll start when things settle.”

But here’s the truth:

Things don’t settle.
You just get stronger and more organised.

And you don’t get stronger by waiting.
You get stronger by starting small and building consistency.

You don’t need a massive emergency fund to change your life.
You need the habit of saving, the system that supports it, and the confidence that you can handle surprises.

What Counts as an “Emergency”? (Let’s Be Clear)

If we don’t define “emergency,” your emergency fund gets eaten by:

  • sales

  • convenience spending

  • spontaneous “self-care” shopping

  • and that “it’s been a week” moment at Target 😄

An emergency is:
✅ urgent
✅ necessary
✅ unexpected
✅ not in the budget

Examples:

  • car repairs

  • urgent medical/dental

  • last-minute travel for family reasons

  • job loss or reduced income

  • essential home repairs

  • unexpected vet bills (pets are adorable little financial liabilities)

Not emergencies:
❌ a holiday
❌ Christmas (it’s predictable, we plan for it)
❌ a new phone because your current one is “annoying”
❌ a birthday gift (also predictable)
❌ a sale (I don’t care how good the sale is)

For those predictable costs, we use sinking funds (we’ll talk about that shortly).

Emergency Fund vs Sinking Funds (The Difference That Changes Everything)

This is a game-changer for getting your financial house in order.

Emergency fund:

For true, unexpected emergencies.

Sinking funds:

For expected expenses that don’t happen weekly or monthly but absolutely happen:

  • car rego and insurance
  • school expenses
  • rates
  • Christmas
  • birthdays
  • holidays
  • annual subscriptions
  • car servicing

When people don’t have sinking funds, they call predictable bills an “emergency”… and then their emergency fund never grows.

So yes, we want both. But we start with a buffer first.

Step One: Build a “Stress Buffer” (The First Goal)

Forget “3 months of expenses” for a second.

Your first goal is what I call a Stress Buffer:

  • $500 if you’re starting from scratch
  • $1,000 if you have a bit more breathing room

This amount won’t solve everything, but it will stop the small stuff from turning into drama.

And you know what? When you see that balance grow, something shifts.

You start trusting yourself. You feel less panicked. You stop living on the edge of your bank balance.

That’s financial muscle building in real time.

“But I Can’t Save” – Yes You Can (Here’s How)

I’m going to say this kindly:

Most people can save something.
They just haven’t had a system that makes it automatic and non-negotiable.

Here are practical ways to start, even if you’re on a tight budget.

1) The Micro-Save Method

Start with:

  • $10 a week

  • or $25 a fortnight

  • or $2 a day

Yes, it feels small. But small done consistently becomes powerful.

The goal is not the amount at the start.
The goal is building the identity of: “I’m someone who saves.”

2) The “Pay Yourself First” Transfer

This is the most important strategy of all:

Set up an automatic transfer on payday into a separate account called:

  • “Emergency Fund”

  • “Stress Buffer”

  • “Do Not Touch” 😄

  • “Future Me’s Peace”

When it’s automatic, you don’t have to think about it.

And thinking less about money is the dream, isn’t it?

3) The Round-Up Hack

Many banks let you round up purchases and move the difference into savings.

It’s not life-changing on its own, but combined with automation?
It’s a lovely little boost.

4) The “Found Money” Rule

Any unexpected money goes to the emergency fund until you hit your first goal:

  • tax returns

  • bonuses

  • cashback

  • refunds

  • gifts

  • overtime

You can still enjoy some of it – I’m not a monster – but Future You gets first dibs until your foundation is built.

Where to Put Your Emergency Fund (So You Don’t Accidentally Spend It)

This part matters because if your emergency fund is sitting next to your spending money… it will be treated like spending money.

Human brains do not like temptation.

Here’s the rule:
✅ separate account
✅ not linked to your everyday card
✅ easy enough to access in an emergency, but not instant-grab easy

A high-interest savings account is often a good option for many people, but the key isn’t the interest rate – it’s the separation.

If you have to take one extra step to access it, you’ll be less likely to raid it for non-emergencies.

How Much Should Your Emergency Fund Be?

Once you’ve built the Stress Buffer, you can level up.

Here are the common tiers:

Tier 1: $500–$1,000 Stress Buffer

Stops small emergencies becoming debt.

Tier 2: 1 month of essential expenses

Covers short-term hiccups.

Tier 3: 3 months of essential expenses

A solid safety net for most households.

Tier 4: 6 months of essential expenses

Great if you’re self-employed, commission-based, or in an industry with variable work.

Important: You don’t have to build this in a week. You build it steadily and that’s what makes it sustainable.

The “Life Is Lifey” List: Why Emergencies Keep Happening

Here are just a few things I see all the time:

  • the car decides it’s done with life
  • unexpected house repair
  • the hot water system taps out
  • the dog eats something it shouldn’t (again)
  • a dentist visit becomes a “how is this $800?” moment
  • your kid needs something for school tomorrow
  • your income changes unexpectedly


These aren’t rare events. They’re predictable unpredictables.

And when you have an emergency fund, you stop being shocked and start being prepared. That is the point.

Life Emergencies Keep Happening

What If You’re Paying Off Debt?

Here’s my professional but real-life approach: If you have debt, you still build a Stress Buffer first.

Why? Because without it, you’ll keep going back into debt every time something happens.

A simple strategy is:

  1. Build $500 – $1,000 buffer
  2. Focus on debt payoff
  3. Build 1 month expenses
  4. Continue debt payoff + build sinking funds
  5. Build to 3 months expenses

This is balanced. Realistic. And it reduces stress.

How to Make Saving Feel Less Painful (Because Yes, It Can)

Saving can feel like deprivation when your brain believes money is scarce.

So we make it feel lighter by doing two things:

1) Make it automatic

If you’re relying on motivation, you’ll save only when you feel inspired.

And motivation is… inconsistent. Automation builds wealth quietly.

2) Give your savings a purpose

Calling it “Savings” is boring. Calling it “Freedom Fund” or “Peace Buffer” hits differently.

Name it like it matters, because it does.

The Secret to Getting Your Financial House in Order: One System That Runs Without You

Here’s the truth:

Most people don’t fail at money because they don’t care.
They fail because they don’t have a system, they’re doing everything manually, with willpower, while stressed.

And that’s like trying to carry groceries without bags. Possible… but messy and exhausting.

A system looks like:

  • separate accounts
  • automatic transfers
  • sinking funds for predictable costs
  • a weekly 10-minute money check-in
  • clear rules for what is/isn’t an emergency

This is what creates calm.

Want Help Building This (So It Actually Sticks)? Join the Membership.

If you’ve read this and thought:

“I want this, but I need help setting it up.” or “I’ve tried to save before and it disappears.” or “I need a plan that’s realistic for my life.”

That’s exactly why I created my Membership.

Inside the Membership we don’t just talk about emergency funds – we build the whole system:
✅  Your Stress Buffer plan (based on your income and expenses)
✅  Automated transfers so saving happens without willpower
✅  Sinking funds so predictable expenses stop feeling like emergencies
✅  Amoney map so your cash flow has structure
✅  Support and guidance so you don’t fall off track

You don’t need to “try harder.” You need the right strategy and ongoing support.

If you’re ready to stop living one unexpected bill away from stress, join the Membership.
Let’s build your emergency fund, get your financial house in order, and help you feel calm with money again for good.

Join The Membership at Financial Management 101

#HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings 


How Do I Recover From Holiday Overspending and Start Fresh With My Money in the New Year?

How Do I Recover From Holiday Overspending and Start Fresh With My Money in the New Year?

The holiday lights have dimmed, the decorations are packed away, and the credit card bill has landed in your inbox. January can feel like a financial hangover – but it doesn’t have to stay that way. The new year is the perfect time for a fresh start with your money. Let’s turn those post-holiday regrets into real financial progress.

Step 1: Acknowledge the Overspend – Without Shame

Let’s be real. You probably didn’t mean to go overboard, but the season has a way of loosening our wallets. Flash sales, peer pressure, holiday cheer – it’s a perfect storm of spending. Here’s the deal: You’re not bad with money. You’re human.

The first thing I tell my clients: “You can’t change what you won’t face.” So open those credit card statements, take a breath, and look at the total. It’s just data and now you’re in the driver’s seat.

Step 2: Have a “Money Review Day”

Set aside one focused hour this week for your personal “Money Review Day – grab a coffee, and get into CEO mode:

 ? Print or pull up your December statements
? List your total credit card balances
? Note the interest rates and minimum payments
✂️ Highlight 3 spending categories to cut back this month

This is about clarity, not judgment. Think of it as gathering puzzle pieces before you start putting them together.

 Have a “Money Review Day”

Step 3: Set a Short-Term Payoff Goal

Massive goals feel good in theory, but small wins are what keep you going. Look at your balances and pick ONE target:

  • Your smallest balance to clear quickly (Snowball method)
  • Your highest-interest card to save money (Avalanche method)

Example: If you owe $3,000 across 3 cards, focus on paying off the $500 one first. That win builds confidence and momentum.

Step 4: Build a Realistic January Budget

Post-holiday budgeting is all about breathing room. Not punishment. Build a one-month “recovery budget” that helps you regain control:

✅ Cover essentials first: Rent/mortgage, food, utilities, transport
❌ Cut or pause: Subscriptions, takeout, impulse buys
? Redirect: Any leftover funds go straight to your debt goal

Even an extra $50 a week toward debt adds up. And if money is tight? See if you can generate a little extra (selling unused items, picking up a side hustle, cashback apps, etc.).

Step 5: Create a “Holiday Payback Plan”

If you overspent by $1,200 in December, divide that into 6 monthly chunks: $200/month. Add it to your budget now and automate it.

This isn’t about guilt – it’s about taking control on your terms. When you have a plan, the weight of the debt gets lighter.

Step 6: Replace Shame with Strategy

Negative self-talk like “I’m terrible with money” only reinforces stuck patterns. Flip the script:

❌ “I can’t believe I did this again.”
✅ “I’m learning new habits that support my goals.”

Money is emotional and mindset matters. Be your own biggest ally, not your harshest critic.

Step 7: Future-Proof Next Year with a Holiday Fund

Want to avoid this January stress next time? Start now with a holiday sinking fund:

  • Name it: “Holiday Joy Fund”
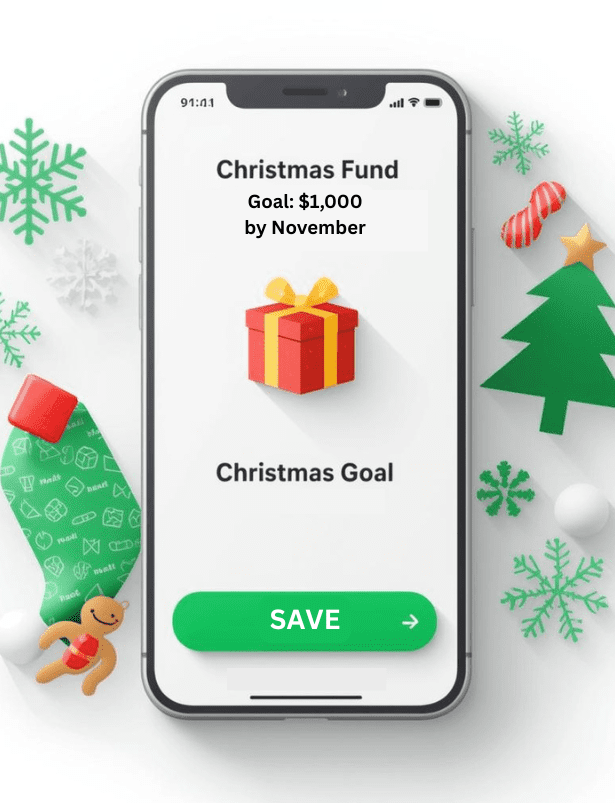
  • Set a goal: $1,000 by November
  • Break it down: $42/month or $21/paycheck

Automate it. When next December hits, you’ll be ready, and proud of yourself.

 Future-Proof Next Year with a Holiday Fund

Step 8: Find a Support System

This journey is easier (and more fun) when you don’t do it alone. Whether it’s a money buddy, group, or coach – accountability is the secret sauce. That’s where my “Financial Muscle Coaching Membership” helps keep you accountable and gives you to the tools and knowledge to update your financial future.

Most people don’t need more information. They need support, structure, and a system.

Final Thoughts

You don’t have to fix everything overnight. But you do have to start. And now is the perfect time. Your financial reset starts with one decision, one action, and one new mindset: You’re in control now.

Ready to stop feeling stuck and finally build real financial momentum? Join Financial Muscle Coaching – this is a membership designed to help you rebuild, reset, and grow stronger with your money. It’s time to train your financial muscles and feel powerful about your money choices.

Let’s make this your best money year yet. ??

Join Financial Muscle Coaching Now

#HowToRecoverFromOverspending #HolidayDebtHelp2025 #PostHolidayMoneyStress #GetBackOnTrackFinancially #HowToResetMoneyAfterTheHolidays #OverspentAtChristmasNowWhat #NewYearFinancialReset #HowToFixMyFinancesAfterHolidays #MoneyRecoveryPlan #CreditCardHangoverHelp

Mind Over Money: How to Rewrite Your Financial Story & Build a Breakthrough Mindset

Mind Over Money: How to Rewrite Your Financial Story & Build a Breakthrough Mindset

Let’s start with the truth:

You can have the perfect budget, a great-paying job, even a savings plan, and still feel stuck financially.

Why? Because if your mindset doesn’t change, your money won’t either.

In this blog, we’re going to unpack:

  • The power of mindset in creating real financial change
  • How money stories are formed (and how to rewrite them)
  • Common mindset blocks that keep people stuck
  • Simple tools to build a breakthrough mindset
  • How this fits into your journey toward financial freedom

Let’s dive in!

? What Is a Money Mindset (and Why Should You Care)?

Your money mindset is your core belief system around money. It shapes how you:

  • Spend
  • Save
  • Earn
  • Invest
  • React in financial stress

It’s the voice in your head that says:

  • “I’m just not good with money.”
  • “Money always slips through my fingers.”
  • “I have to work hard to survive.”

Or, on the flip side:

  • “I’m in control of my finances.”
  • “I know how to make money work for me.”
  • “Wealth is available to me.”

The difference? Mindset.

This isn’t wishful thinking, this is neuroscience and behavioural psychology. What you believe impacts how you behave. And how you behave impacts your bank account.

? Where Do These Beliefs Come From?

Most of our money beliefs are formed before age 7.

You may have grown up hearing:

  • “Money doesn’t grow on trees.”
  • “We can’t afford that.”
  • “Rich people are greedy.”

Without realising it, those phrases became part of your internal money script – even if they don’t serve you now.

Other money stories come from:

  • Your parents’ relationship with money
  • Cultural or community influences
  • Early financial trauma (like debt, bankruptcy, poverty)

Good news? You can rewrite the script.

? Common Money Mindset Blocks (And How They Show Up)

If you’ve ever thought:

  • “As soon as I get ahead, something always knocks me back.”
  • “I don’t deserve to be wealthy.”
  • “I feel anxious just opening my banking app,”

…you’re not alone.

Here are 5 of the most common mindset blocks we see:

1. Scarcity Thinking

The belief that there’s never enough (time, money, opportunities). This leads to fear-based decisions and self-sabotage.

2. Imposter Syndrome

Feeling like you’re not smart or “good enough” to manage money well. You might under-earn or avoid taking risks.

3. Fear of Success

It sounds weird, but many fear what will change if they actually become successful.

4. Guilt Around Wealth

Especially common if you grew up in struggle or were taught that money = greed.

5. Money Avoidance

This shows up as procrastination, not checking accounts, or avoiding financial conversations.

Getting Out of Debt Starts in Your Mind

✨ The Power of Rewriting Your Financial Story

Here’s the deal: your current money story isn’t your final chapter.

You can shift from:

  • “I’ll always be in debt” → “I’m learning how to manage and reduce my debt.”
  • “I’m terrible with money” → “I’m becoming more financially confident every day.”

Just like you wouldn’t expect physical results without working out, you can’t expect financial change without working on your mindset.

? Simple Tools to Strengthen Your Money Mindset

1. Awareness is Power

Start by journaling or reflecting on your early money memories. What did you hear, see, or feel growing up?

2. Affirmations That Stick

Affirmations are powerful when they’re practiced consistently. Try these:

  • “I am safe and in control of my finances.”
  • “Every dollar I spend and save has purpose.”
  • “I deserve financial abundance.”

3. Surround Yourself With Growth

Follow financial educators, podcasts, and communities that reinforce positive beliefs about money.

4. Set Micro-Goals

Progress builds confidence. Start with tiny, achievable wins – like tracking your expenses or saving $10/week.

5. Visualise the Outcome

Spend 2 minutes a day visualising what your financially free life looks like. Your brain responds powerfully to visualisation.

6. Join a Supportive Program

A structured environment with accountability and coaching helps speed up your mindset shift.

That’s exactly what we provide in the Financial Freedom Breakthrough Program, launching this September.

? The Role of Mindset in the Financial Freedom Diagram

Let’s circle back to the diagram from Financial Management 101.

If you’re stuck at the bottom (overwhelmed, struggling, surviving), it’s not just a numbers issue.

It’s a belief issue.

Mindset is the foundation that supports every other level:

  • Budgeting
  • Saving
  • Debt reduction
  • Credit health
  • Wealth building
  • Estate planning

With the right mindset, these tools feel doable. Without it, even the best strategy will collapse.

? Real Talk: You Are NOT Broken

Maybe you’ve made mistakes. Maybe you’ve felt stuck for years. Maybe you’re scared to even start.

That doesn’t make you broken – it makes you human.

Your past doesn’t define you. Your future is still yours to shape.

And the first step? Believing you can.

Working on your money mindset while paying off debt is so important.

? Ready to Rewrite Your Story?

Here’s how to begin:

  1. Download our Free Money Mindset Workbook (coming soon)
  2. Join the waitlist for the Financial Freedom Breakthrough Program
  3. Share this post with someone who needs to hear it today

    ? Final Thoughts

    Money mindset isn’t fluff, it’s the fuel behind every breakthrough.

    If you want a different result, you need a different belief.

    You’re not meant to just survive. You’re meant to thrive.

    Let’s start believing in that version of you, and take action to bring it to life.

    Your Financial Freedom Breakthrough™