R U OK? (The Question You Never Ask Yourself)

R U OK? (The Question You Never Ask Yourself)

On September 10, most of Australia will be asking each other “R U OK?” Workplaces will run morning teas. There’ll be yellow everywhere. It’s a genuinely good day, and I’m glad it exists – it’s done a lot for getting these conversations out into the open where they belong, after years of them staying firmly behind closed doors.

But here’s the question I actually want to ask you, business owner to business owner… when’s the last time you asked yourself that?

We’re brilliant at checking in on everyone else. Staff, clients, family, that one supplier who always sounds a bit frazzled on the phone. But most business owners I talk to haven’t had an honest conversation with themselves in months. We’re too busy holding everything together to notice we might not be, ourselves. We’re the ones people come to when something’s gone wrong, which means we’ve quietly trained everyone around us, including ourselves to believe we don’t need checking on.

Running a business is one of the loneliest jobs going, if I’m honest. You’re the one everyone brings their problems to. There’s rarely anyone bringing you theirs, asking how you’re actually tracking underneath it all. Even the people who love you tend to ask “how’s the business going?” rather than “how are you going?” and those are very different questions with very different answers.

The performance of “fine”

There’s a particular skill business owners develop without meaning to, the ability to say “yeah, good, flat out” in a completely convincing tone while privately feeling anything but. It becomes automatic. Someone asks how you’re going at the school pickup, at the football, at a client meeting, and out it comes before you’ve even thought about it. Over time, that automatic answer starts to replace the honest one, even in your own head. You stop checking because you’ve gotten so good at performing that you don’t seem to need it.

So today, let’s flip it. Three questions, and actual permission to answer them properly, without the reflexive “yeah, good, flat out” that we all give without thinking.

Am I okay, or am I just coping?

There’s a real difference. Coping looks like getting through the week in one piece, ticking things off, keeping the wheels on. Okay looks like genuinely enjoying the thing you built, feeling proud of it, curious about where it’s going, energised rather than depleted by it. If you’ve been in coping mode for a while now, that’s worth noticing, not brushing off with “it’s just a busy season,” because busy seasons have a habit of becoming permanent if nobody names them.

There’s no shame in “coping” as an honest answer. It’s often the truest thing a business owner has said about themselves in months, once they finally stop and let themselves say it. The shame only comes from pretending otherwise for too long.
What am I carrying that I haven't said out loud?
For a lot of business owners, it's the money. The gap between what the business brings in and what it feels like it should be bringing in by now, given how hard you're working.

What am I carrying that I haven’t said out loud?

For a lot of business owners, it’s the money. The gap between what the business brings in and what it feels like it should be bringing in by now, given how hard you’re working. That gap is heavy to carry on your own, and you really don’t have to. I’ve had conversations with business owners who’ve been sitting on that particular worry for years, silently, because it felt embarrassing to say out loud, like admitting it meant admitting they’d failed at something. It’s not embarrassing. It’s incredibly common, and it’s fixable once it’s actually spoken about, usually far more fixable than the years of silent worry suggested.

Sometimes what people are carrying isn’t even the money itself, it’s the fear of what the money says about them. That’s a heavier load than the actual numbers ever are.

Who’s actually in my corner?

Not staff. Not clients. I mean the people who ask how you’re going, not just how the business is going. If that list is short, that’s your sign; a mentor, a community, or even just a standing coffee with someone who genuinely gets what this life is like. Business ownership can be surprisingly isolating even when you’re surrounded by people all day, because being surrounded by people isn’t the same as being known by them.

The physical signs worth noticing

Sometimes the “am I okay” question is easier to answer by looking at the body rather than the mind. Are you sleeping properly, or lying awake running through tomorrow’s problems? Are you short-tempered with people who don’t deserve it? Have you stopped doing the small things that used to recharge you – the walk, the round of golf, the Sunday paper, because there’s “no time”? These aren’t small details. They’re often the clearest signal available that the tank’s getting low, well before the mind is ready to admit it in so many words.

It’s okay to not have the answer yet

If you sat with those three questions and didn’t love your answers, that’s not a failure, that’s information. The whole point of asking is so you can actually do something with what you find, rather than carrying it around unexamined for another six months. Awareness on its own doesn’t fix anything, but it’s the step that has to come first, and it’s the step most business owners skip entirely because it’s uncomfortable.

You can’t run a healthy business from an empty tank. Checking in on yourself isn’t soft, whatever the old-school hustle crowd would have you believe, it’s strategy, plain and simple. A business owner who’s running on empty makes worse decisions, snaps more easily, and enjoys less of what they’ve built. None of that helps the business either – it’s not a trade-off between looking after yourself and looking after the business. They’re the same job.

And if part of what’s weighing on you is the money side of things, that’s exactly what The Edge exists for. A place where you’re not carrying it solo, surrounded by other business owners asking each other the real questions instead of the polite ones.

Join The Edge: https://financialmanagement101.com.au/work-with-karen/the-edge/

And if today’s the day you actually need to talk to someone, Lifeline is on 13 11 14, any hour, no appointment needed.

What to do once you’ve asked yourself

Asking the question is the easy part, once you’ve actually made yourself do it. The harder part is what comes next, because most business owners are excellent at identifying a problem and then filing it away under “deal with that eventually.” So if any of the three questions above landed a bit close to home, don’t let it end there.

Pick one small thing. Not a complete overhaul of your life, not a dramatic announcement to everyone that you’re “making changes.” One small thing; a call to a friend you’ve been meaning to make, an actual look at the money situation you’ve been avoiding, a boundary around one evening a week that’s just yours. Small, specific, doable this week, not “someday.”
Business owners checking in on business owners

Business owners checking in on business owners

There’s a particular kind of relief that comes from talking to someone else who genuinely understands what this life involves – the highs that nobody else quite gets excited about the way you do, and the lows that nobody else quite understands the weight of either. Friends and family love you, but unless they’ve run a business themselves, there’s a layer of it they simply can’t relate to, however much they try.

That’s part of why community matters so much here. Not a support group in the clinical sense, just other people in the same boat, who ask “how are you really going” and actually mean it, who’ve had the sleepless nights over cash flow and the quiet pride over a client win, and who get it without you having to explain the whole backstory first.
THE EDGE Membership

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess
#EntrepreneurMindset
 

Busy Is Not Profitable: 7 Financial Foundations Every Business Owner Needs

Busy Is Not Profitable: 7 Financial Foundations Every Business Owner Needs

There’s a big myth in small business that if you just work hard enough, everything will eventually click into place.

Spoiler alert: hard work matters, but hard work without financial foundations can leave you exhausted, underpaid, and wondering why your business still feels so heavy.

I see this all the time with small business owners, tradies, franchisees, coaches, and self-employed professionals.

They are flat out. Clients are coming in. Invoices are going out. The calendar is packed.

And yet… There is still stress. Still pressure. Still that sinking feeling of, “Why does it feel like I’m doing all this work and not getting ahead?”

Here’s why:

Because busy is not profitable. And being great at your trade or profession is not the same as having strong money systems.

The good news? You do not need a finance degree to fix this. You just need the right foundations.

Here are seven of the most important ones.

1. A cashflow system that tells the truth

Cashflow is not something you check when you are already in trouble.
It is something you build so you can stay out of trouble.

A good cashflow system shows you:

  • what is coming in
  • what is going out
  • what bills are approaching
  • what is available to spend
  • what needs to be set aside for tax, super, wages, and future costs

Cashflow gives you visibility. Visibility gives you control.

2. Clear separation between personal and business money

Using your personal account like a business overdraft creates confusion fast.

It becomes harder to track spending, harder to know what the business is really earning, and harder to make clean decisions.

Separating business and personal finances is one of the fastest ways to reduce chaos.
It is not about being fancy. It is about being clear.

3. Pricing that actually protects your profit

So many business owners price from fear.

Fear of losing the sale.
Fear of seeming too expensive.
Fear of being judged.

But underpricing does not make you more professional. It makes your business more fragile.

Your pricing needs to cover more than the job in front of you. It needs to reflect overheads, admin time, tax obligations, profit goals, and the actual value you deliver.

Pricing with confidence is not greedy.
It is responsible.

4. A plan to pay yourself properly

Using your personal account like a business overdraft creates confusion fast.

It becomes harder to track spending, harder to know what the business is really earning, and harder to make clean decisions.

Separating business and personal finances is one of the fastest ways to reduce chaos.
It is not about being fancy. It is about being clear.

5. Weekly and monthly money rhythms

You do not need to stare at your numbers every day.
But you do need a rhythm.

That might include:

  • checking cashflow weekly
  • reviewing key reports monthly
  • monitoring expenses and margins
  • tracking unpaid invoices
  • spotting small issues before they turn into big ones

Confidence with numbers is built through repetition, not perfection.

6. Knowing your numbers without drowning in them

You do not need to obsess over every metric.
You do need to know the numbers that matter.

Think:

  • revenue
  • gross profit
  • operating expenses
  • net profit
  • cash position
  • debt levels
  • wage costs
  • tax set-asides

The goal is not more complexity.
The goal is better decisions.

When you know what your numbers are saying, you stop making emotional decisions and start making strategic ones.

7. A business structure that can handle growth

Growth is exciting, but if your systems are messy, it can magnify every weakness.

That is why foundations matter before scaling.

You want business systems that support:

  • clear accounts setup
  • simple automations
  • better reporting
  • cleaner budgeting
  • stronger decision-making
  • less burnout

Strong structure makes growth feel possible instead of painful.

Business foundations create freedom

Why this matters right now

The business landscape is not getting easier.
Costs are rising. Margins can be tight. Pressure builds quickly when you do not have clarity.

That is exactly why now is the time to stop relying on memory, hope, and hustle alone.

The strongest business owners are not always the loudest or busiest.
They are the ones who know their numbers, trust their systems, and make decisions early.

Foundations Create freedom

Let’s make this simple. When your financial foundations are solid, you get:

  • less panic
  • less avoidance
  • less confusion
  • better decisions
  • stronger profit
  • more confidence
  • more breathing room

And honestly? More enjoyment.

Because business should not feel like one long financial mystery.

    A business structure will help you handle growth

    Your invitation to stop winging it

    If you know your foundations need work, you are not alone.
    And you do not have to figure it all out the hard way.

    That is exactly what The Edge Bootcamp is designed to help you do.

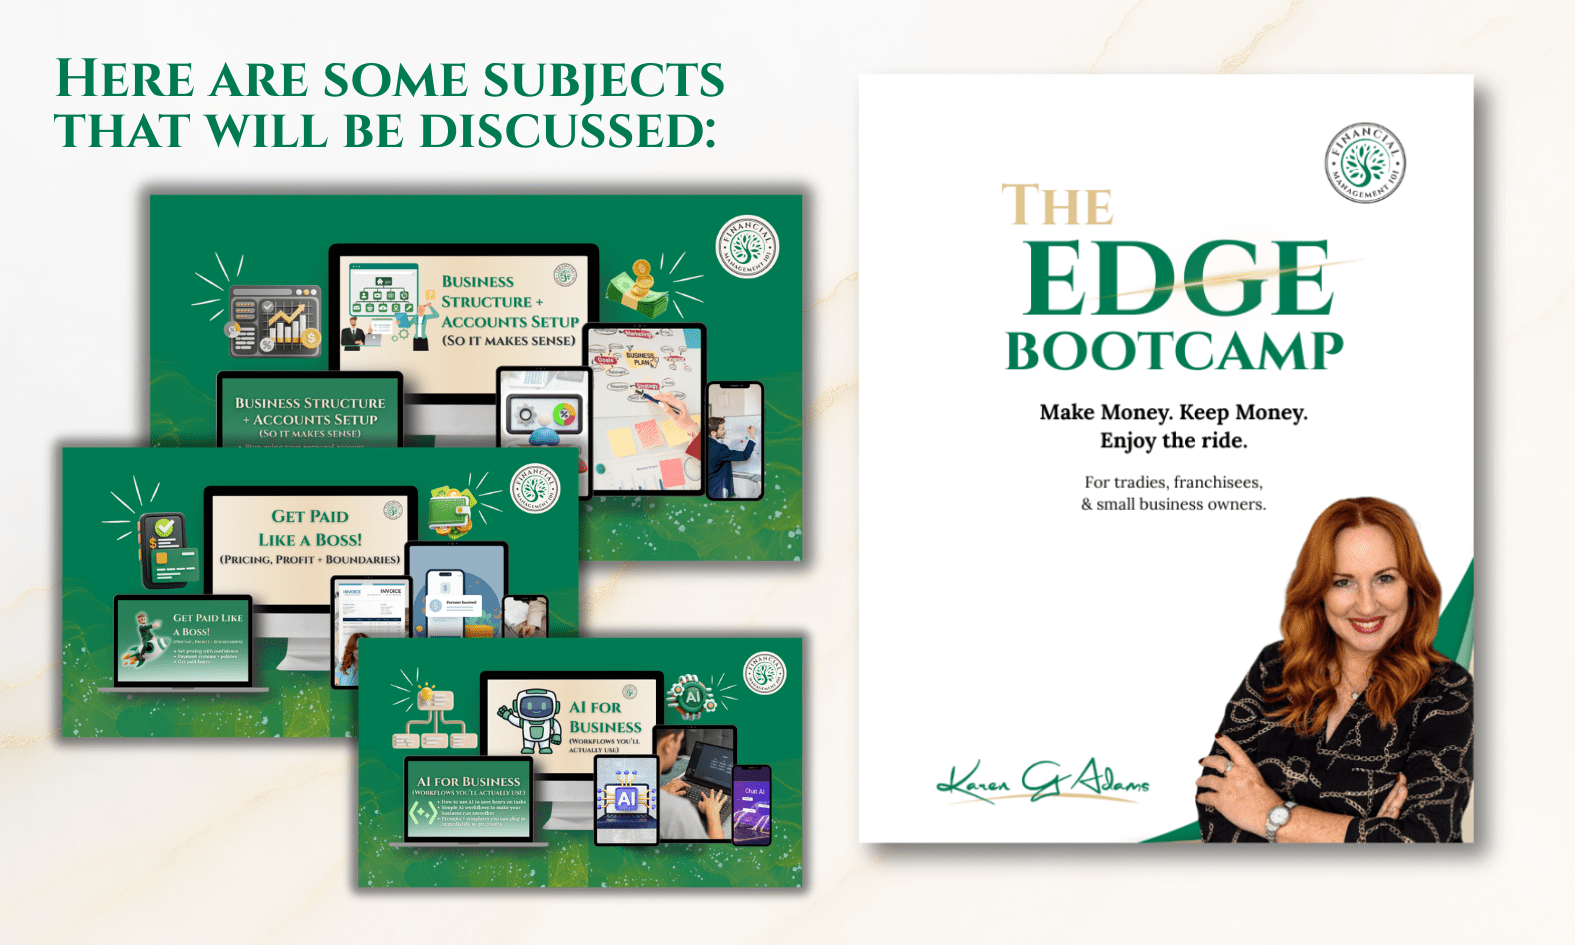
    Over two practical, high-impact days, we dig into the real foundations of profitable business: money systems, CEO mindset, cashflow, paying yourself, pricing, budgets, business setup, reading your numbers, leadership, growth stages, and more.

    This is for business owners who want results, not just motivation.

    Join The Edge Bootcamp in May and give your business the foundations it needs to make money, keep money, and enjoy the ride.

    Because being flat out is not the goal.
    Building a business that works for you is.

    Join The Edge Bootcamp

    #HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings 


    Budgeting Without the Boring: The Money Map Method That Actually Works

    Budgeting Without the Boring: The Money Map Method That Actually Works

    Let’s be honest for a second. The word “budget” has the same vibe as:

    • “We need to talk…”
    • “Your call is being transferred…”
    • “Please see the attached invoice…”

    It makes people tense. Defensive. Slightly sweaty. 😅

    And here’s the irony: most people don’t hate having a plan. They hate the way budgeting has been sold to them – like it’s punishment for daring to enjoy life.

    So today, I’m giving you a different approach.

    Not a strict budget.
    Not a spreadsheet that needs a PhD to operate.
    Not a system that makes you feel like you have to track every piece of gum you’ve ever purchased.

    This is Money Mapping – the method I use with clients who want to feel in control, not controlled.

    Because your money doesn’t need a prison.

    It needs a plan. A plan that fits your actual life. Not the version of you who meal preps on Sundays and never impulse buys at Kmart.

    (If that version of you exists, I’d like to meet her. She sounds organised and slightly intimidating.)

    Why Traditional Budgets Fail (and why it’s not your fault)

    Most budgets fail for three reasons:

    1) They’re too restrictive

    People try to cut everything at once: coffees, fun, birthdays, little treats, takeaway, holidays… and then wonder why they rebound like a rubber band.

    If a budget feels like suffering, you won’t stick to it.
    Your brain will treat it like a threat.
    And humans don’t do “threat” long-term.

    2) They’re too complicated

    Forty-seven categories. Daily tracking. Constant adjustments.
    You miss one thing and suddenly you feel like you’ve “failed.”

    A budget that requires constant maintenance becomes another job.
    And nobody needs a second job that doesn’t pay.

    3) They’re built on guilt, not goals

    Many budgets are basically: “Stop spending money on things that make you happy.”

    No thanks.

    Money mapping works because it’s:

    • simple
    • flexible
    • based on priorities
    • designed for consistency, not perfection

    What is a Money Map?

    A Money Map is a simple plan that tells your money where to go before life grabs it.

    It answers these questions:

    1. What must be paid? (essentials + bills)
    2. What matters to you? (your priorities)
    3. What are we building? (savings, emergency fund, investing, debt reduction)
    4. How do we keep your life enjoyable while still making progress? (yes, fun stays)

    A money map is not about tracking every dollar.
    It’s about creating a flow.

    And when your money flows with intention, financial stress drops fast

    A Money Map is a simple plan that tells your money where to go before life grabs it.

    The Big Mindset Shift: A Budget Isn’t Restriction – It’s Permission

    I want you to reframe this:

    A budget isn’t a list of things you can’t do.
    It’s a permission slip that says:

    ✅ “Yes, you can spend money on what you love.”
    ✅ “Yes, you can have fun.”
    ✅ “Yes, you can enjoy your life.”
    … and also
    ✅ “Yes, you can build wealth and feel safe.”

    That’s the goal: enjoying today while protecting tomorrow.

    The Money Map Framework (Simple, Powerful, Real-Life Friendly)

    Here’s the structure I recommend. It’s clean and easy:

    Category 1: Essentials (Must Pays)

    These are the costs of keeping your life running:

    • mortgage/rent
    • utilities
    • groceries
    • fuel/transport
    • insurance
    • minimum debt repayments
    • childcare/school essentials
    • basic medical

    These are your “keep the lights on” expenses.

    Category 2: Future You (Your Financial Muscle)

    This is where you build safety and wealth:

    • emergency fund
    • sinking funds (car rego, Christmas, school costs, rates, holidays)
    • extra debt repayments
    • investing/super top-ups (where appropriate)

    Future You deserves funding. Not “whatever’s left.”

    Rainy Day Fund or Emergency Fund

    Category 3: Fun & Freedom (Guilt-Free Spending)

    This is the category that keeps you sane:

    • coffees
    • dinners out
    • entertainment
    • hobbies
    • shopping (within reason, Karen… within reason 😄)
    • little treats

    The reason most budgets fail is because this category is either missing or unrealistically small.

    We’re not doing that here.

    Step-by-Step: How to Build Your Money Map in Under an Hour

    Grab a pen, notes app, or whatever you use when you’re feeling productive for five minutes.

    Step 1: Find your baseline numbers

    Look at the last 4–8 weeks of spending (not because we love pain, but because data helps).

    Write down:

    • total income (after tax)
    • total essentials
    • average weekly spending (groceries, fuel, eating out, shopping)
    • debt minimums
    • any annual bills that sneak up (rego, insurance, school, rates)

    You’re not judging. You’re observing.

    Step 2: Choose your “Money Map style”

    There are two main styles:

    1. A) Weekly Flow Map (best for people paid weekly/fortnightly)
    • Allocate money each pay into Essentials / Future You / Fun
    1. B) Monthly Map (best for salaried monthly pay)
    • Set amounts for each category and automate them

    If you’ve tried budgeting before and it didn’t stick, weekly is usually easier because it gives faster feedback.

    Step 3: Set up separate accounts (this is where the magic happens)

    I’m going to say this lovingly:

    If all your money sits in one account, your brain will treat it like it’s all available.
    That’s not a discipline problem. That’s a human brain problem.

    A simple setup is:

    1. Bills account (Essentials)
    2. Spending account (groceries/fuel/fun)
    3. Future You account (emergency + sinking funds)

    Automation is your best friend. Because you’re busy.
    And your money system should run even when you’re tired.

    Step 4: Decide your “non-negotiables”

    These are your priorities — the things you want your money to reflect.

    Examples:

    • “I want to stop feeling anxious about bills.”
    • “I want an emergency fund.”
    • “I want to pay off this debt.”
    • “I want to travel without putting it on a credit card.”
    • “I want to stop fighting with my partner about money.”

    Your money map should support your real goals — not someone else’s idea of financial success.

    Step 5: Allocate your numbers (start simple)

    Here’s a starting point many people can relate to:

    • Essentials: 60–75%
    • Future You: 10–20% (even 5% is a start if money is tight)
    • Fun & Freedom: 10–20%

    If your essentials are currently higher than 75% — you’re not alone. Cost of living has been doing the most.

    This is where strategy matters: we might need to reduce leaks, renegotiate bills, or adjust the debt plan to create breathing room.

    Step 6: Create one weekly “Money Date” (10 minutes)

    Once a week:

    • check what’s coming out
    • check what’s coming in
    • make sure bills are covered
    • adjust your spending category if needed

    No drama. No self-lectures. Just a quick check-in.

    Think of it like brushing your teeth. You don’t do it once and call it done forever.

    The “I Hate Tracking” Version: The 3-Number Method

    If you’re someone who rebels against tracking (I see you), do this instead:

    Pick three numbers each week:

    1. Your weekly spending limit (food + fuel + fun)
    2. Your weekly Future You transfer
    3. Your “buffer amount” you want to keep in your spending account

    Then the rule is simple:
    When spending hits the limit… you stop spending until next week.
    No guilt. Just boundaries.

    This is the system many of my clients love because it’s:

    • quick
    • clear
    • low-maintenance
    • effective

    Money Map in Real Life: What This Looks Like (Example)

    Let’s say your household brings in $2,500 a week after tax.

    You might map it like this:

    • $1,700 Essentials (bills, groceries, fuel, minimum debt)
    • $400 Future You (emergency fund + sinking funds + extra debt)
    • $400 Fun & Freedom (eating out, treats, spending money)

    Then you automate:

    • $1,700 goes straight into Bills account
    • $400 into Future You account
    • $400 stays in Spending account

    Now you’re not trying to “budget” daily.
    You’re simply spending from the right place.

    And when your Spending account runs low, it gives you a clear signal:
    “That’s it for this week.”

    No spreadsheet required.

    What If There’s Not Enough Money to Map?

    This is the part where I get very real with you:

    If you feel like there’s never enough, it doesn’t mean you’re failing.
    It means your map needs to include leak-plugging and breathing space first.

    Here’s what I do with clients when money is tight:

    1. tighten obvious leaks (subscriptions, lazy renewals, bank fees)
    2. build a tiny emergency buffer (even $500 can change your stress levels)
    3. stabilise bills and reduce panic spending
    4. create sinking funds for predictable expenses
    5. then build momentum

    You don’t jump from stressed to thriving in one week.
    But you can absolutely move from chaos to calm with the right steps.

    The Most Important Part: Your Money Map Must Match Your Personality

    Some people need structure.
    Some need flexibility.
    Some need boundaries.
    Some need permission.

    So here are a few personality-based tweaks:

    If you’re an overspender:

    • reduce “available money” in your spending account
    • use separate “fun” cash or a dedicated card
    • increase automation

    If you’re an underspender/anxious saver:

    • allocate guilt-free fun money and actually spend it
    • focus on safety targets (emergency fund)
    • build confidence with small consistent steps

    If you’re a “set and forget” person:

    • automate everything
    • schedule the weekly money check-in
    • keep categories very simple

    If you’re a couple/family:

    • do a shared Money Map + personal spending allowances
    • agree on the weekly “household number”
    • remove judgement from the conversation

    Money mapping isn’t one-size-fits-all.
    It’s “your life, your values, your plan.”

    If You Want This to Stick, Join the Membership

    Now, if you’re reading this thinking:

    “Okay… this makes sense. But I need help setting it up properly.” or “I’ve tried before and I fall off the wagon.” or “I want a system that actually fits my life.”

    That’s exactly what my Membership is for.

    Because here’s the truth:

    Most people don’t need more information. They need support, structure, and someone to keep them consistent.

    Inside the Membership, we don’t just talk about budgeting. We:
    ✅ build your personal Money Map (based on your real numbers)
    ✅ set up accounts and automation so it runs without willpower
    ✅ create sinking funds so life stops surprising you
    ✅ learn how to manage spending without guilt
    ✅ build financial muscle with ongoing guidance and community

    You’re not meant to do this alone.

    If you’re ready to stop winging it and start feeling calm and in control, join the Membership.
    Let’s build your Money Map together — and get your financial house in order the smart way.

    budgeting without spreadsheets, simple budget method, cash flow planning, how to budget in Australia, reduce financial stress, personal finance tips, money management system, budgeting for beginners, weekly money check-in, sinking funds, financial management 101, Karen G Adams, financial coaching


    How Can I Rebuild My Confidence After Making a Financial Mistake or Falling Behind on My Budget?

    How Can I Rebuild My Confidence After Making a Financial Mistake or Falling Behind on My Budget?

    We’ve all had that moment.

    You check your bank account… and it’s lower than you thought.
    You open your credit card bill… and it’s higher than you expected.
    You look at your budget… and realse you haven’t followed it for two weeks.

    Cue the shame spiral.

    If you’ve recently made a money mistake – or you just feel behind – I want you to know this:

    You are not alone.
    You are not a failure.
    And you are absolutely capable of bouncing back stronger.

    This blog will walk you through how to move from guilt to growth, and rebuild your confidence one step at a time.

    1. Separate Your Self-Worth from Your Net Worth

    First and foremost: you are not your bank balance.

    Your financial missteps don’t make you “bad with money.” They make you human.

    Whether you overspent, ignored your budget, or slipped back into old habits, it doesn’t define who you are. It’s a moment – not a life sentence.

    Start here:

    • Remind yourself: “I am capable of change.”
    • Reflect on a past financial win, no matter how small

    Say out loud: “I forgive myself. I’m ready to move forward.”

    2. Get Honest (Without the Shame)

    Let’s name what happened – not to beat yourself up, but to take your power back.

    Ask yourself:

    • What did I spend that I hadn’t planned for?
    • Did I avoid tracking or checking in with my money?
    • Did I say “yes” to things I couldn’t afford?

    Write it all down. You’re not here to judge yourself – just to gain clarity so you can move forward with purpose.

    3. Understand What Triggered the Slip-Up

    There’s always a “why” behind every money misstep mand understanding it is key to change.

    Common triggers:

    • Emotional spending (boredom, stress, celebration)
    • People-pleasing (saying yes to things out of guilt)
    • Lack of planning (unexpected expenses you didn’t prep for)
    • Old money stories (like “I’ll never get ahead anyway”)

    Identifying the trigger gives you a new layer of awareness and that’s when real change begins.

    4. Reset with a Micro-Goal

    When your confidence is shaken, the best thing you can do is create a tiny win that rebuilds momentum.

    Here are some examples:

    • Track your spending for the next 3 days
    • Create a mini budget just for this week
    • Make one extra payment toward your credit card
    • Pause one subscription and save the money instead

    Success is a series of small, intentional steps. Start with one.

    Create a mini budget for this week

    5. Watch Your Words (They Matter More Than You Think)

    Your internal dialogue becomes your financial reality.

    Let’s flip the script:

    ❌ “I’m terrible with money.”
    ✅ “I’m learning how to manage my money better every day.”
    ❌ “I’ll never get out of debt.”
    ✅ “Every payment I make moves me closer to freedom.”
    ❌ “I can’t stick to a budget.”
    ✅ “I’m figuring out a system that works for me.”

    Language matters. Speak like someone who’s growing because you are.

    6. Track Progress, Not Perfection

    You don’t have to get everything right to be making progress. Celebrate the fact that:

    • You noticed the slip-up
    • You chose to stop and reflect
    • You’re taking action now

    That’s what winning with money actually looks like.

    Make a habit of reflecting each month:

    • What went well?
    • Where did I struggle?

    • What can I adjust?

    And remember: even showing up for your finances when it’s hard is worth celebrating.

    7. Lean Into Support – Don’t Do This Alone

    Shame thrives in isolation. Confidence grows in community.

    Find a space where:

    • You can ask questions without feeling judged
    • You can share your wins and struggles
    • You can be held accountable to your goals

    That’s exactly what Financial Muscle Coaching is a coaching and accountability space, where we normalise setbacks and celebrate bounce-backs.

    Inside the membership, you’ll find structure, strategy, and support – all in one place.

    8. Build Your Financial Muscle, One Rep at a Time

    Rebuilding financial confidence is like building physical strength – it happens one rep at a time.

    One decision to check your balance.
    One habit of tracking your spending.
    One conversation where you ask for help instead of hiding.
    One payment that moves you forward.

    You don’t need to leap – you just need to lift. And every lift makes you stronger.

    Final Thoughts

    Mistakes are part of the journey – not the end of it.

    You are not behind. You are not bad with money. And you don’t have to do this perfectly to make progress.

    Every time you choose to come back – to review, reflect, and reset – you’re rebuilding your confidence.

    You’re showing yourself what you’re made of.
    And you’re writing a new money story that’s rooted in self-trust, resilience, and growth.

    You’ve got this. And I’m right here cheering you on.

    ? Join Financial Muscle Coaching

    If you’re tired of navigating your money alone – or beating yourself up every time you slip – Financial Muscle Coaching is the place for you.

    In this weekly coaching space, you’ll get:
    ✅ Encouragement instead of criticism
    ✅ Clear, doable action plans that meet you where you are
    ✅ Real accountability to build habits and confidence that last

    No more shame. No more silence. Just strength, strategy, and steady growth.

    Join Financial Muscle Coaching Now

    #HowToChangeMoneyMindset #ResetMyMoneyBeliefs #BuildFinancialConfidence #MoneyMindsetHelp #FinancialMindsetCoaching #HowToFeelBetterAboutMoney #WhyDoIFeelStressedAboutMoney #NewYearMoneyMindset #MoneyMindsetReset2025 #PositiveMoneyBeliefs #MoneyMindset #FinancialFreedomJourney #MoneyCoach #BudgetMindset #AbundanceMindset

    How Can I Reset My Money Mindset This Year and Finally Feel in Control of My Finances?

    How Can I Reset My Money Mindset This Year and Finally Feel in Control of My Finances?

    It’s Not Just About the Numbers – It’s About Your Mindset

    Look, you can have the best spreadsheet in the world…

    You can download all the budget apps, cut back on coffee, and cancel every subscription.

    But if your money mindset hasn’t shifted? You’ll still feel stuck, overwhelmed, or like “you’re just not good with money.”

    Let’s fix that because 2026 is the year we stop dragging last year’s money baggage into our future.

    This blog is your ultimate guide to resetting your mindset, clearing out old financial beliefs, and building a powerful, positive relationship with money.

    And yes – it’s fun, it’s doable, and it’s way more effective than another boring budget.

    Let’s go.

    What Even Is a Money Mindset?

    Your money mindset is the collection of beliefs, emotions, and thoughts you have about money. It’s your personal “money story” – the internal script you repeat (often subconsciously) about earning, saving, spending, and wealth.

    Some of it comes from your childhood, your past experiences, or society’s weird money rules. And here’s the wild part: It influences every single money decision you make.

    Your mindset determines whether you:

    • Save confidently or hoard out of fear
    • Ask for more money or shrink your value
    • Budget with ease or avoid your bank balance like it’s haunted

    Signs You Might Need a Money Mindset Reset

    ?‍♀️ You feel anxious or guilty every time you spend money
    ? You avoid looking at your bank account or credit card
    ?‍♂️ You say things like “I’m just bad with money” or “I’ll never get ahead”
    ?‍♀️ You feel stuck in a paycheck-to-paycheck cycle, even when your income grows

    If that sounds like you, it doesn’t mean you’re broken – it means it’s time to reprogram your financial brain.

    Step 1: Identify the Old Money Stories Holding You Back

    Before you can shift your mindset, you need to see what you’re working with.

    Ask yourself:

    • What did I learn about money growing up?
    • What do I believe about wealthy people?
    • When I think about money, do I feel free or fearful?

    Some common limiting beliefs:

    • “There’s never enough money.”
    • “Money is hard to manage.”
    • “I’m not good with numbers.”
    • “More money means more stress.”

    ? None of these are facts. They’re just beliefs. And beliefs can change.

    Step 2: Choose Empowering New Money Beliefs

    You get to write a new story this year. Start by replacing the old thoughts with intentional, positive ones:

    Instead of: “I’m bad with money” → Say: “I’m learning how to manage my money powerfully.”
    Instead of: “I’ll never get ahead” → Say: “Every dollar I manage well moves me forward.”
    Instead of: “Money is stressful” → Say: “Money is a tool I’m learning to use with confidence.”

    ✨ Tip: Write your new beliefs down. Post them on your mirror. Make them your phone wallpaper. Say them out loud. Train your brain to believe better.

    Step 3: Connect Your Money to What You Actually Value

    Ask yourself:

    • What do I want money to do for me this year?
    • What do I value most – freedom? stability? generosity? joy?
    • How can I align my spending and saving with those values?

    Example: 

    If you value peace of mind, create a savings plan.
    If you value freedom, reduce debt.
    If you value fun, build in guilt-free spending money.

    Money doesn’t just serve numbers – it should serve your life.

    Money doesn’t just serve numbers - it should serve your life.

    Step 4: Make Mindset Work Part of Your Routine

    You don’t go to the gym once and expect abs, right?
    Same with your mindset. It takes repetition.

    Here’s a weekly reset routine you can follow:

    ? Money Mindset Reset (10 Minutes):

    • Review your thoughts from the week – what came up around money?
    • Journal one thing you’re proud of financially
    • Write or say one new belief out loud
    • Visualise yourself succeeding with money

    ? Do this every Sunday before your weekly budget check-in and you’ll be unstoppable.

    Step 5: Surround Yourself With New Financial Energy

    If you want to upgrade your mindset, you need to upgrade your environment.

    That might look like:

    • Listening to empowering money podcasts
    • Following financial educators who speak your language (hello ? yes me ?)
    • Talking about money with friends who are also growing
    • Hiring a coach who helps you reframe, reset, and rise (hello ? yes me again ?)

    You can’t change your money mindset in isolation. That’s why I created my Financial Muscle Coaching Membership.  It’s where financial growth meets real community and support.

    Listen to empowering money podcasts like Managing Money Made Easy

    Step 6: Replace Shame With Curiosity

    When things go “wrong”  you overspend, forget a bill, or avoid a budget – don’t spiral into shame. Instead, ask:

    • What triggered this?
    • What do I need right now – support, structure, or space?
    • What can I do differently next time?

    Every financial hiccup is just data. Don’t let one moment of messiness define your entire money story.

    You’re allowed to be a work in progress and a success story at the same time.

    Step 7: Set Mindset-Based Goals for the Year

    Let’s skip the boring “save more, spend less” vibe.

    Try these instead:

    • “This year, I’m building my financial self-trust.”
    • “This year, I’m proving I can stick to one habit consistently.”
    • “This year, I’m learning to enjoy managing my money.”

    Then break that into monthly goals:
    ✅ January: Track every dollar
    ✅ February: Create a spending plan aligned to my values
    ✅ March: Build an emergency fund of $300

    Momentum creates confidence and mindset fuels momentum.

    Final Thoughts: You Can’t Budget Your Way Out of a Scarcity Mindset

    If you’re stuck in fear, guilt, or shame around money, no spreadsheet will save you. You have to go deeper. And you have to believe that a new relationship with money is possible for you.

    Because it is.

    You are not bad with money.
    You are not too far behind.
    You are not stuck – you’re just getting started.

    And when you build a strong, positive money mindset? Everything else gets easier.

    Let’s build that mindset muscle together.

    ? Join Financial Muscle Coaching

    If you’re ready to change your money mindset, build real financial confidence, and create a life that feels good – not just looks good on paper – I’ve got you.

    Join Financial Muscle Coaching – my coaching community where we:
    ✅ Rewrite limiting money stories
    ✅ Build strong, sustainable habits
    ✅ Create aligned goals you actually want to follow

    This isn’t just budgeting. This is mindset, motivation, and muscle – built week by week, with me in your corner.

    Your money mindset reset starts here. Let’s go. ?

    Join Financial Muscle Coaching Now

    #HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney #MindsetShiftForMoney #RebuildMoneyConfidence #WhatIsMoneyMindset #MoneyMindsetTransformation #MoneyMindset #MoneyConfidence #FinancialReset #MoneyHealing #FinancialEmpowerment #AbundanceMindset #WealthMindset #MoneyCoach #MoneyGoals2025 #FinancialMuscle