Father’s Day and the Business Owner Who Can’t Switch Off

Father’s Day and the Business Owner Who Can’t Switch Off

Happy Father’s Day to every business owner who “just needs to check one email” during the barbecue.

You know the scene. Phone face-down on the table, out of principle. Two minutes later, face-up again. “Just checking something quick.” Forty-five minutes later, still checking, while someone’s asking if you want another sausage and you’re not entirely sure you heard them the first time.

Here’s the bit nobody says out loud; if you genuinely can’t switch off for one Sunday, it’s not because you’re dedicated, it’s because something in the business is relying entirely on you being switched on, all the time. That’s not commitment. That’s a business that hasn’t had its systems built yet, quietly telling on itself every time your phone lights up at a family lunch.

I say this with love, because I’ve been that person too. There’s a particular kind of guilt that creeps in when you’re not checking, like something’s about to fall over the second you look away. Sometimes it will. That’s actually useful information, not a personality flaw. It tells you precisely where the weak point is, rather than leaving you to vaguely feel like you should “be better at switching off,” which is advice with nothing practical underneath it.
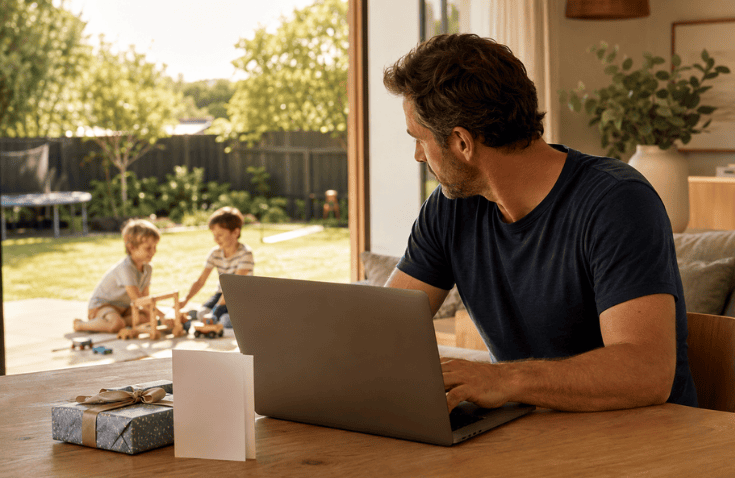
Happy Father's Day to every business owner who "just needs to check one email" during the barbecue.

It’s not a discipline problem

Most business owners think the fix is “just try harder to unplug.” Buy a nicer phone case, set a screen time limit, promise yourself Sunday is sacred. And then Sunday arrives and none of it holds, because the willpower was never the actual problem.

You can’t discipline your way out of a business with no systems, no visibility, and nobody else who knows where anything lives. If you’re the only one who knows the client’s login, the only one who knows how the invoicing actually works, the only one who can answer “did that order go out,” then of course you can’t switch off – you’re not being undisciplined, you’re being the entire operations department in one exhausted human body.

The phone-checking isn’t the actual problem. It’s just the symptom you can see. Fixing the symptom without fixing the cause is like taking the batteries out of a smoke alarm because the beeping is annoying.

What it costs, quietly

There’s a cost to this that doesn’t show up on the profit and loss but shows up everywhere else. It shows up in the conversation you half-listened to. The moment with the kids you were technically present for but not really in. The mate who stopped inviting you to things because you always seemed distracted, or cancelled at the last minute, or spent the whole time with one eye on your phone. None of that gets tracked anywhere. It just quietly accumulates until one day you notice the gap.

The real question to ask

The more useful question isn’t “how do I switch off more.” It’s “what would genuinely happen today if I didn’t check my phone at all?” If the honest answer is “everything would fall apart”, that tells you exactly where the gaps are. Not a criticism. A map.

Sit with that answer for a second. Is it really everything, or is it one or two specific things? Usually, when people actually write it down, the list is shorter than the panic suggested. There’s something almost funny about how big the fear feels compared to how short the actual list turns out to be once it’s on paper instead of in your head.

Building the buffer, one piece at a time

You don’t need to overhaul the whole business in a weekend to get some breathing room back. Start with the smallest, most repeated interruption, the thing that pulls you out of family time most often and ask what it would take to hand even part of that off. A simple checklist someone else can follow. A shared login instead of a personal one. An automated reminder instead of you personally remembering. None of these are big, dramatic fixes. They’re small, boring, unglamorous changes, and they’re exactly the ones that actually stick.

One small fix before the next family day

Before your next family day, try this. Write down the three things that would actually need you if they went sideways. Then ask yourself, honestly, whether one of those three could be handled by a simple checklist, a bit of automation, or someone else entirely, instead of by you personally, every single time. Fix one. That’s next Father’s Day a little more sorted than this one and the one after that, a little more sorted again. This isn’t a one-weekend fix. It’s a habit of slowly handing things off until your presence isn’t the only thing holding the whole operation together.

A better business creates a better life and a better life includes actually being at the barbecue, present for the conversation, not just physically there while mentally reconciling last month’s invoices.

The version of success worth aiming for

There’s a version of business success that gets celebrated a lot, the one measured in revenue, growth, how many staff you’ve got, how big the operation’s gotten. It’s a fine measure, as far as it goes. But it misses something important, which is whether the person who built all of that can actually enjoy a Sunday without their phone glued to their hand.

I’d argue the better measure of success is this – can you take a full day off, properly off, and come back to a business that’s still standing, without having spent the whole day half-present because part of you never left? That’s a much harder thing to build than revenue, and it’s a much better thing to have.
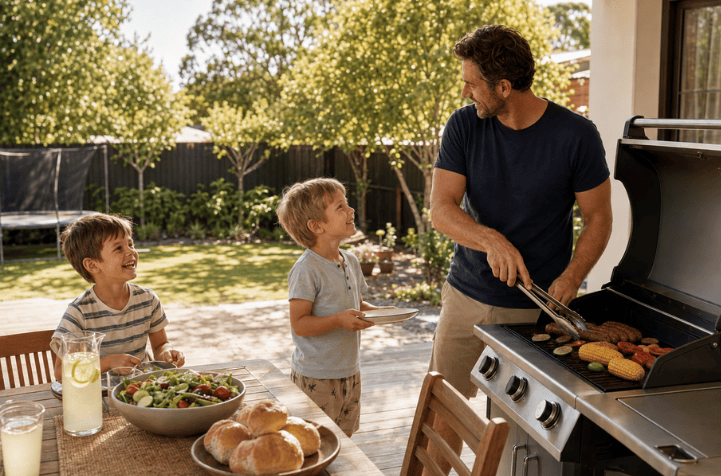
Building the systems that let you switch off isn't a luxury add-on. It's kind of the whole point of doing this in the first place.

Kids notice more than we think

There’s a particular moment a lot of business-owner parents have at some point; a kid saying something like “you’re always on your phone,” delivered completely matter-of-factly, no drama attached, which somehow makes it land harder than if they’d shouted it. Kids don’t measure your love by how hard you’re working for their future. They measure it by whether you were actually there when they wanted to tell you something, show you something, or just have you sitting next to them doing nothing in particular.

That’s not a guilt trip, plenty of us are working exactly because we want a better life for them. It’s just worth remembering that the “better life” bit doesn’t only mean money down the track. It means you, actually present, more often than not.

Building the systems that let you switch off isn’t a luxury add-on. It’s kind of the whole point of doing this in the first place.

If you want help working out exactly where your business is leaning on you too hard, The CEO Dashboard is built for precisely that, a clear look at what’s actually relying on you, and what could run perfectly well without you for a Sunday afternoon.
The CEO Dashboard

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess
#EntrepreneurMindset
 

The Emergency Fund Isn’t Optional – How to Build One Without Feeling Broke (and why it changes everything)

The Emergency Fund Isn’t Optional – How to Build One Without Feeling Broke (and why it changes everything)

Let’s talk about the one money habit that turns chaos into calm faster than almost anything else:

An emergency fund.

Now before you roll your eyes and think, “Karen, I knowww… but I can barely afford groceries,” stay with me.

Because I’m not about to tell you to magically save three months of expenses overnight, live on rice and sadness, and stop enjoying life.

That’s not financial education – that’s financial punishment. 😅

What I am going to do is show you how to build an emergency fund in a way that feels doable, realistic, and actually sticks… even if money is tight.

And here’s why this matters:

An emergency fund isn’t just “money in an account.”
It’s peace, options, and less stress when life does what life does best… surprise you at the worst possible time.

So let’s get your financial house in order by building the foundation that stops everything from wobbling.

Why the Emergency Fund Is Non-Negotiable (Even If You Have Debt)

I want you to imagine your finances like a house.

If your foundation is cracked, everything else feels unstable:

  • you can’t plan properly
  • you can’t relax
  • you’re constantly bracing for impact
  • and one unexpected bill can knock you sideways

An emergency fund is the foundation.

It stops you from:

  • using credit cards “just this once”
  • grabbing BNPL for essentials
  • borrowing from family
  • draining your savings every time something happens
  • feeling like you’re always behind

Even if you’re paying down debt, you still need a buffer.
Because without one, every emergency becomes more debt… and that cycle is exhausting.

An Emergency Fund Is Non-Negotiable Even If You Have Debt

The Biggest Myth: “I’ll Start When I Have More Money”

This is the #1 reason people delay emergency savings.

They think:

  • “I’ll start when I get a pay rise.”

  • “I’ll start when the kids are older.”

  • “I’ll start when the cost of living calms down.” (lol… remember calm?)

  • “I’ll start when things settle.”

But here’s the truth:

Things don’t settle.
You just get stronger and more organised.

And you don’t get stronger by waiting.
You get stronger by starting small and building consistency.

You don’t need a massive emergency fund to change your life.
You need the habit of saving, the system that supports it, and the confidence that you can handle surprises.

What Counts as an “Emergency”? (Let’s Be Clear)

If we don’t define “emergency,” your emergency fund gets eaten by:

  • sales

  • convenience spending

  • spontaneous “self-care” shopping

  • and that “it’s been a week” moment at Target 😄

An emergency is:
✅ urgent
✅ necessary
✅ unexpected
✅ not in the budget

Examples:

  • car repairs

  • urgent medical/dental

  • last-minute travel for family reasons

  • job loss or reduced income

  • essential home repairs

  • unexpected vet bills (pets are adorable little financial liabilities)

Not emergencies:
❌ a holiday
❌ Christmas (it’s predictable, we plan for it)
❌ a new phone because your current one is “annoying”
❌ a birthday gift (also predictable)
❌ a sale (I don’t care how good the sale is)

For those predictable costs, we use sinking funds (we’ll talk about that shortly).

Emergency Fund vs Sinking Funds (The Difference That Changes Everything)

This is a game-changer for getting your financial house in order.

Emergency fund:

For true, unexpected emergencies.

Sinking funds:

For expected expenses that don’t happen weekly or monthly but absolutely happen:

  • car rego and insurance
  • school expenses
  • rates
  • Christmas
  • birthdays
  • holidays
  • annual subscriptions
  • car servicing

When people don’t have sinking funds, they call predictable bills an “emergency”… and then their emergency fund never grows.

So yes, we want both. But we start with a buffer first.

Step One: Build a “Stress Buffer” (The First Goal)

Forget “3 months of expenses” for a second.

Your first goal is what I call a Stress Buffer:

  • $500 if you’re starting from scratch
  • $1,000 if you have a bit more breathing room

This amount won’t solve everything, but it will stop the small stuff from turning into drama.

And you know what? When you see that balance grow, something shifts.

You start trusting yourself. You feel less panicked. You stop living on the edge of your bank balance.

That’s financial muscle building in real time.

“But I Can’t Save” – Yes You Can (Here’s How)

I’m going to say this kindly:

Most people can save something.
They just haven’t had a system that makes it automatic and non-negotiable.

Here are practical ways to start, even if you’re on a tight budget.

1) The Micro-Save Method

Start with:

  • $10 a week

  • or $25 a fortnight

  • or $2 a day

Yes, it feels small. But small done consistently becomes powerful.

The goal is not the amount at the start.
The goal is building the identity of: “I’m someone who saves.”

2) The “Pay Yourself First” Transfer

This is the most important strategy of all:

Set up an automatic transfer on payday into a separate account called:

  • “Emergency Fund”

  • “Stress Buffer”

  • “Do Not Touch” 😄

  • “Future Me’s Peace”

When it’s automatic, you don’t have to think about it.

And thinking less about money is the dream, isn’t it?

3) The Round-Up Hack

Many banks let you round up purchases and move the difference into savings.

It’s not life-changing on its own, but combined with automation?
It’s a lovely little boost.

4) The “Found Money” Rule

Any unexpected money goes to the emergency fund until you hit your first goal:

  • tax returns

  • bonuses

  • cashback

  • refunds

  • gifts

  • overtime

You can still enjoy some of it – I’m not a monster – but Future You gets first dibs until your foundation is built.

Where to Put Your Emergency Fund (So You Don’t Accidentally Spend It)

This part matters because if your emergency fund is sitting next to your spending money… it will be treated like spending money.

Human brains do not like temptation.

Here’s the rule:
✅ separate account
✅ not linked to your everyday card
✅ easy enough to access in an emergency, but not instant-grab easy

A high-interest savings account is often a good option for many people, but the key isn’t the interest rate – it’s the separation.

If you have to take one extra step to access it, you’ll be less likely to raid it for non-emergencies.

How Much Should Your Emergency Fund Be?

Once you’ve built the Stress Buffer, you can level up.

Here are the common tiers:

Tier 1: $500–$1,000 Stress Buffer

Stops small emergencies becoming debt.

Tier 2: 1 month of essential expenses

Covers short-term hiccups.

Tier 3: 3 months of essential expenses

A solid safety net for most households.

Tier 4: 6 months of essential expenses

Great if you’re self-employed, commission-based, or in an industry with variable work.

Important: You don’t have to build this in a week. You build it steadily and that’s what makes it sustainable.

The “Life Is Lifey” List: Why Emergencies Keep Happening

Here are just a few things I see all the time:

  • the car decides it’s done with life
  • unexpected house repair
  • the hot water system taps out
  • the dog eats something it shouldn’t (again)
  • a dentist visit becomes a “how is this $800?” moment
  • your kid needs something for school tomorrow
  • your income changes unexpectedly


These aren’t rare events. They’re predictable unpredictables.

And when you have an emergency fund, you stop being shocked and start being prepared. That is the point.

Life Emergencies Keep Happening

What If You’re Paying Off Debt?

Here’s my professional but real-life approach: If you have debt, you still build a Stress Buffer first.

Why? Because without it, you’ll keep going back into debt every time something happens.

A simple strategy is:

  1. Build $500 – $1,000 buffer
  2. Focus on debt payoff
  3. Build 1 month expenses
  4. Continue debt payoff + build sinking funds
  5. Build to 3 months expenses

This is balanced. Realistic. And it reduces stress.

How to Make Saving Feel Less Painful (Because Yes, It Can)

Saving can feel like deprivation when your brain believes money is scarce.

So we make it feel lighter by doing two things:

1) Make it automatic

If you’re relying on motivation, you’ll save only when you feel inspired.

And motivation is… inconsistent. Automation builds wealth quietly.

2) Give your savings a purpose

Calling it “Savings” is boring. Calling it “Freedom Fund” or “Peace Buffer” hits differently.

Name it like it matters, because it does.

The Secret to Getting Your Financial House in Order: One System That Runs Without You

Here’s the truth:

Most people don’t fail at money because they don’t care.
They fail because they don’t have a system, they’re doing everything manually, with willpower, while stressed.

And that’s like trying to carry groceries without bags. Possible… but messy and exhausting.

A system looks like:

  • separate accounts
  • automatic transfers
  • sinking funds for predictable costs
  • a weekly 10-minute money check-in
  • clear rules for what is/isn’t an emergency

This is what creates calm.

Want Help Building This (So It Actually Sticks)? Join the Membership.

If you’ve read this and thought:

“I want this, but I need help setting it up.” or “I’ve tried to save before and it disappears.” or “I need a plan that’s realistic for my life.”

That’s exactly why I created my Membership.

Inside the Membership we don’t just talk about emergency funds – we build the whole system:
✅  Your Stress Buffer plan (based on your income and expenses)
✅  Automated transfers so saving happens without willpower
✅  Sinking funds so predictable expenses stop feeling like emergencies
✅  Amoney map so your cash flow has structure
✅  Support and guidance so you don’t fall off track

You don’t need to “try harder.” You need the right strategy and ongoing support.

If you’re ready to stop living one unexpected bill away from stress, join the Membership.
Let’s build your emergency fund, get your financial house in order, and help you feel calm with money again for good.

Join The Membership at Financial Management 101

#HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings 


How Can I Rebuild My Confidence After Making a Financial Mistake or Falling Behind on My Budget?

How Can I Rebuild My Confidence After Making a Financial Mistake or Falling Behind on My Budget?

We’ve all had that moment.

You check your bank account… and it’s lower than you thought.
You open your credit card bill… and it’s higher than you expected.
You look at your budget… and realse you haven’t followed it for two weeks.

Cue the shame spiral.

If you’ve recently made a money mistake – or you just feel behind – I want you to know this:

You are not alone.
You are not a failure.
And you are absolutely capable of bouncing back stronger.

This blog will walk you through how to move from guilt to growth, and rebuild your confidence one step at a time.

1. Separate Your Self-Worth from Your Net Worth

First and foremost: you are not your bank balance.

Your financial missteps don’t make you “bad with money.” They make you human.

Whether you overspent, ignored your budget, or slipped back into old habits, it doesn’t define who you are. It’s a moment – not a life sentence.

Start here:

  • Remind yourself: “I am capable of change.”
  • Reflect on a past financial win, no matter how small

Say out loud: “I forgive myself. I’m ready to move forward.”

2. Get Honest (Without the Shame)

Let’s name what happened – not to beat yourself up, but to take your power back.

Ask yourself:

  • What did I spend that I hadn’t planned for?
  • Did I avoid tracking or checking in with my money?
  • Did I say “yes” to things I couldn’t afford?

Write it all down. You’re not here to judge yourself – just to gain clarity so you can move forward with purpose.

3. Understand What Triggered the Slip-Up

There’s always a “why” behind every money misstep mand understanding it is key to change.

Common triggers:

  • Emotional spending (boredom, stress, celebration)
  • People-pleasing (saying yes to things out of guilt)
  • Lack of planning (unexpected expenses you didn’t prep for)
  • Old money stories (like “I’ll never get ahead anyway”)

Identifying the trigger gives you a new layer of awareness and that’s when real change begins.

4. Reset with a Micro-Goal

When your confidence is shaken, the best thing you can do is create a tiny win that rebuilds momentum.

Here are some examples:

  • Track your spending for the next 3 days
  • Create a mini budget just for this week
  • Make one extra payment toward your credit card
  • Pause one subscription and save the money instead

Success is a series of small, intentional steps. Start with one.

Create a mini budget for this week

5. Watch Your Words (They Matter More Than You Think)

Your internal dialogue becomes your financial reality.

Let’s flip the script:

❌ “I’m terrible with money.”
✅ “I’m learning how to manage my money better every day.”
❌ “I’ll never get out of debt.”
✅ “Every payment I make moves me closer to freedom.”
❌ “I can’t stick to a budget.”
✅ “I’m figuring out a system that works for me.”

Language matters. Speak like someone who’s growing because you are.

6. Track Progress, Not Perfection

You don’t have to get everything right to be making progress. Celebrate the fact that:

  • You noticed the slip-up
  • You chose to stop and reflect
  • You’re taking action now

That’s what winning with money actually looks like.

Make a habit of reflecting each month:

  • What went well?
  • Where did I struggle?

  • What can I adjust?

And remember: even showing up for your finances when it’s hard is worth celebrating.

7. Lean Into Support – Don’t Do This Alone

Shame thrives in isolation. Confidence grows in community.

Find a space where:

  • You can ask questions without feeling judged
  • You can share your wins and struggles
  • You can be held accountable to your goals

That’s exactly what Financial Muscle Coaching is a coaching and accountability space, where we normalise setbacks and celebrate bounce-backs.

Inside the membership, you’ll find structure, strategy, and support – all in one place.

8. Build Your Financial Muscle, One Rep at a Time

Rebuilding financial confidence is like building physical strength – it happens one rep at a time.

One decision to check your balance.
One habit of tracking your spending.
One conversation where you ask for help instead of hiding.
One payment that moves you forward.

You don’t need to leap – you just need to lift. And every lift makes you stronger.

Final Thoughts

Mistakes are part of the journey – not the end of it.

You are not behind. You are not bad with money. And you don’t have to do this perfectly to make progress.

Every time you choose to come back – to review, reflect, and reset – you’re rebuilding your confidence.

You’re showing yourself what you’re made of.
And you’re writing a new money story that’s rooted in self-trust, resilience, and growth.

You’ve got this. And I’m right here cheering you on.

? Join Financial Muscle Coaching

If you’re tired of navigating your money alone – or beating yourself up every time you slip – Financial Muscle Coaching is the place for you.

In this weekly coaching space, you’ll get:
✅ Encouragement instead of criticism
✅ Clear, doable action plans that meet you where you are
✅ Real accountability to build habits and confidence that last

No more shame. No more silence. Just strength, strategy, and steady growth.

Join Financial Muscle Coaching Now

#HowToChangeMoneyMindset #ResetMyMoneyBeliefs #BuildFinancialConfidence #MoneyMindsetHelp #FinancialMindsetCoaching #HowToFeelBetterAboutMoney #WhyDoIFeelStressedAboutMoney #NewYearMoneyMindset #MoneyMindsetReset2025 #PositiveMoneyBeliefs #MoneyMindset #FinancialFreedomJourney #MoneyCoach #BudgetMindset #AbundanceMindset

Mind Over Money: How to Rewrite Your Financial Story & Build a Breakthrough Mindset

Mind Over Money: How to Rewrite Your Financial Story & Build a Breakthrough Mindset

Let’s start with the truth:

You can have the perfect budget, a great-paying job, even a savings plan, and still feel stuck financially.

Why? Because if your mindset doesn’t change, your money won’t either.

In this blog, we’re going to unpack:

  • The power of mindset in creating real financial change
  • How money stories are formed (and how to rewrite them)
  • Common mindset blocks that keep people stuck
  • Simple tools to build a breakthrough mindset
  • How this fits into your journey toward financial freedom

Let’s dive in!

? What Is a Money Mindset (and Why Should You Care)?

Your money mindset is your core belief system around money. It shapes how you:

  • Spend
  • Save
  • Earn
  • Invest
  • React in financial stress

It’s the voice in your head that says:

  • “I’m just not good with money.”
  • “Money always slips through my fingers.”
  • “I have to work hard to survive.”

Or, on the flip side:

  • “I’m in control of my finances.”
  • “I know how to make money work for me.”
  • “Wealth is available to me.”

The difference? Mindset.

This isn’t wishful thinking, this is neuroscience and behavioural psychology. What you believe impacts how you behave. And how you behave impacts your bank account.

? Where Do These Beliefs Come From?

Most of our money beliefs are formed before age 7.

You may have grown up hearing:

  • “Money doesn’t grow on trees.”
  • “We can’t afford that.”
  • “Rich people are greedy.”

Without realising it, those phrases became part of your internal money script – even if they don’t serve you now.

Other money stories come from:

  • Your parents’ relationship with money
  • Cultural or community influences
  • Early financial trauma (like debt, bankruptcy, poverty)

Good news? You can rewrite the script.

? Common Money Mindset Blocks (And How They Show Up)

If you’ve ever thought:

  • “As soon as I get ahead, something always knocks me back.”
  • “I don’t deserve to be wealthy.”
  • “I feel anxious just opening my banking app,”

…you’re not alone.

Here are 5 of the most common mindset blocks we see:

1. Scarcity Thinking

The belief that there’s never enough (time, money, opportunities). This leads to fear-based decisions and self-sabotage.

2. Imposter Syndrome

Feeling like you’re not smart or “good enough” to manage money well. You might under-earn or avoid taking risks.

3. Fear of Success

It sounds weird, but many fear what will change if they actually become successful.

4. Guilt Around Wealth

Especially common if you grew up in struggle or were taught that money = greed.

5. Money Avoidance

This shows up as procrastination, not checking accounts, or avoiding financial conversations.

Getting Out of Debt Starts in Your Mind

The Power of Rewriting Your Financial Story

Here’s the deal: your current money story isn’t your final chapter.

You can shift from:

  • “I’ll always be in debt” → “I’m learning how to manage and reduce my debt.”
  • “I’m terrible with money” → “I’m becoming more financially confident every day.”

Just like you wouldn’t expect physical results without working out, you can’t expect financial change without working on your mindset.

? Simple Tools to Strengthen Your Money Mindset

1. Awareness is Power

Start by journaling or reflecting on your early money memories. What did you hear, see, or feel growing up?

2. Affirmations That Stick

Affirmations are powerful when they’re practiced consistently. Try these:

  • “I am safe and in control of my finances.”
  • “Every dollar I spend and save has purpose.”
  • “I deserve financial abundance.”

3. Surround Yourself With Growth

Follow financial educators, podcasts, and communities that reinforce positive beliefs about money.

4. Set Micro-Goals

Progress builds confidence. Start with tiny, achievable wins – like tracking your expenses or saving $10/week.

5. Visualise the Outcome

Spend 2 minutes a day visualising what your financially free life looks like. Your brain responds powerfully to visualisation.

6. Join a Supportive Program

A structured environment with accountability and coaching helps speed up your mindset shift.

That’s exactly what we provide in the Financial Freedom Breakthrough Program, launching this September.

? The Role of Mindset in the Financial Freedom Diagram

Let’s circle back to the diagram from Financial Management 101.

If you’re stuck at the bottom (overwhelmed, struggling, surviving), it’s not just a numbers issue.

It’s a belief issue.

Mindset is the foundation that supports every other level:

  • Budgeting
  • Saving
  • Debt reduction
  • Credit health
  • Wealth building
  • Estate planning

With the right mindset, these tools feel doable. Without it, even the best strategy will collapse.

? Real Talk: You Are NOT Broken

Maybe you’ve made mistakes. Maybe you’ve felt stuck for years. Maybe you’re scared to even start.

That doesn’t make you broken – it makes you human.

Your past doesn’t define you. Your future is still yours to shape.

And the first step? Believing you can.

Working on your money mindset while paying off debt is so important.

? Ready to Rewrite Your Story?

Here’s how to begin:

  1. Download our Free Money Mindset Workbook (coming soon)
  2. Join the waitlist for the Financial Freedom Breakthrough Program
  3. Share this post with someone who needs to hear it today

    ? Final Thoughts

    Money mindset isn’t fluff, it’s the fuel behind every breakthrough.

    If you want a different result, you need a different belief.

    You’re not meant to just survive. You’re meant to thrive.

    Let’s start believing in that version of you, and take action to bring it to life.

    Your Financial Freedom Breakthrough™
    Debt Freedom: 3 Simple Shifts That Accelerate Your Payoff Plan (Without Losing Your Mind!)

    Debt Freedom: 3 Simple Shifts That Accelerate Your Payoff Plan (Without Losing Your Mind!)

    Let’s get honest for a second. Debt… it’s a heavy word, right? For many of us, just hearing it triggers:

    • A knot in the stomach.
    • A wave of shame or regret.
    • That overwhelming thought: “Will I ever get out of this?”

    If this sounds familiar, take a deep breath – you are not alone. Whether it’s credit cards, student loans, car payments, or that lingering medical bill, debt can feel like a mountain that just keeps growing. But here’s the truth most people won’t tell you:

    Debt freedom isn’t just about paying more toward your balances – it’s about shifting the way you think, act, and plan with your money.

    Today, I’m going to walk you through:

    • Why traditional debt payoff advice often backfires.
    • The three powerful mindset shifts that can accelerate your debt payoff (without sucking all the joy out of your life).
    • How your credit score, saving, and debt freedom are more connected than you think.
    • Simple steps you can take right now to start feeling empowered and in control.

    And yes, we’ll keep it light, fun, and inspiring, because you deserve to feel good about your money journey, even while tackling debt.

    ? The Problem with Traditional Debt Advice (Why It Doesn’t Work for Most People)

    Let’s start here. If you’ve ever Googled “how to pay off debt fast,” you’ve probably seen some version of this advice:

    • “Cut out all unnecessary spending.”
    • “Stop eating out.”
    • “Work a second (or third) job.”
    • “Sell everything you own.”

    And sure… some of these tips can help in extreme situations. But for most people, this kind of advice:

    • Feels impossible to stick with long-term.
    • Creates a cycle of guilt and burnout.
    • Ignores the emotional and psychological side of debt.

    Here’s the truth:

    Debt isn’t just a numbers problem, it’s a behavior and mindset problem, too. Yes, we need to talk about strategy, but if we skip the emotional side of debt, we’ll never create lasting results.

    Getting Out of Debt Starts in Your Mind

    Why Getting Out of Debt Starts in Your Mind (Not Just Your Wallet)

    Debt can feel like quicksand, but it’s often not just about the math. It’s about:

    • The stories you tell yourself about money.
    • The shame or guilt you carry from past mistakes.
    • The anxiety that makes you want to avoid looking at your accounts.

    Think about it:

    • How many times have you avoided checking your credit card balance?
    • How often do you think, “I’ll deal with this later,” when it comes to debt?
    • How many times have you paid off a balance, only to end up back in debt again later?

    This isn’t about being “bad” with money – it’s about being human.

    We live in a world that encourages overspending, instant gratification, and comparison. Debt happens. But freedom from it? That happens when you combine practical steps with internal shifts.

    ? The 3 Simple Shifts That Can Speed Up Your Debt Freedom Journey

    Let’s dive into the real magic. Here are the three powerful mindset shifts that can help you:

    • Pay off debt faster.
    • Stop the cycle of yo-yo debt.
    • Build financial confidence along the way.

    Shift #1: From Shame to Ownership

    Here’s the thing about debt: It thrives in secrecy.

    The more we hide from it, the more it grows, and the worse we feel. Shame sounds like:

    • “I should have known better.”
    • “I’m terrible with money.”
    • “I’ll never get ahead.”

    But here’s the truth:

    • Debt doesn’t define you.
    • Your past mistakes don’t determine your future.
    • You can learn new skills and create different results.

    The first step toward debt freedom isn’t cutting expenses, it’s cutting the shame.

    Action Step:

    • Write down your total debt, every dollar, every balance.
    • Look at it with neutrality – this is data, not a character flaw.

    Say this out loud:

    “This is where I am right now. It’s not permanent. I have the power to change it.” This simple shift from shame to ownership changes everything.

    Shift #2: From Scarcity to Empowered Planning

    Many people approach debt payoff from a place of fear:

    “I need to get rid of this ASAP or else!”

    “I have to sacrifice everything until I’m debt-free.”

    But here’s the problem:

    • Extreme approaches rarely last.
    • Scarcity leads to burnout and yo-yo spending.

    Instead, approach debt payoff from a place of empowerment: “I am intentionally choosing where my money goes each month.”

    This means:

    • Making a realistic debt payoff plan that fits your actual life.
    • Balancing progress with joy, you don’t have to cut everything you love.
    • Prioritising consistency over speed.

    Action Step: Choose a debt payoff method that feels good to you:

    • Debt Snowball: Pay off the smallest balance first for quick wins.
    • Debt Avalanche: Pay off the highest-interest debt first to save money long-term.

    Create a monthly payment plan that includes money for fun and savings. This way, you’ll stay motivated—and avoid slipping back into debt later.

    Create a monthly payment plan that includes money for fun and savings.

    Shift #3: From Avoidance to Proactive Credit Care

    Ah, credit scores, the mysterious numbers that somehow rule our financial lives. Many people either obsess over their credit or completely avoid it. But here’s the truth:

    • Your credit score isn’t your enemy, it’s just a tool.
    • You don’t need to obsess over it daily, but ignoring it won’t help either.

    Proactive credit care means:

    • Checking your credit report at least once a year (you can do this for free!).
    • Disputing any errors that could be dragging your score down.
    • Making consistent, on-time payments to build positive credit history.
    • Keeping credit utilization low (aim for under 30% of your limits).

    Action Step:

    • Go to equifax.com.au and pull your free credit report.
    • Check for errors or suspicious activity.
    • Set up automatic payments for at least the minimum on all debts to protect your score.

    When you face your credit head-on, it becomes a tool, not a threat.

    ? Debt Freedom & Saving: The Power Duo

    Here’s something most debt advice misses: Paying off debt without saving at the same time can backfire. Why? Because if you throw every dollar at debt but don’t have any savings, guess what happens the next time life throws a curveball? Yep – you end up right back in debt.

    Even while you’re paying off debt, it’s essential to:

    • Build a starter emergency fund (even just $500 to $1,000).
    • Save a little every month, even if it’s $10 or $25.

    This small cushion keeps you from relying on credit when unexpected expenses pop up, and they will.

    Action Step:

    • Open a separate savings account (nicknamed “Safety Net” if you like!).
    • Set up automatic transfers – even small ones.
    • Celebrate every deposit, no matter how small.

    This helps break the cycle of debt for good.

    ? Why Debt Freedom Is More Emotional Than You Think

    Here’s something I see all the time in my coaching work: People think paying off debt will automatically make them feel better.

    But here’s the secret:

    • Debt freedom feels amazing, but it also brings up unexpected emotions.
    • Many people feel a strange sense of loss when they finish paying off debt.
    • Others struggle with identity shifts – “Who am I without debt?”
    • And some even self-sabotage and fall back into debt again.

    This is why working on your money mindset while paying off debt is so important. It’s not just about the numbers, it’s about your emotional relationship with money, freedom, and self-worth.

    Working on your money mindset while paying off debt is so important.

    ? Your Debt-Free Future Starts with One Step (But It’s Not What You Think)

    If you’re feeling overwhelmed by your debt right now, here’s what I want you to know:

    You don’t need to:

    • Have a perfect plan.
    • Pay it all off overnight.
    • Deprive yourself to succeed.

    You just need to:

    • Get clear on your numbers.
    • Shift your mindset from shame to empowerment.
    • Take consistent, small actions.

    And yes – this is exactly why inside my Your Financial Freedom Breakthrough™ – 90 Day Money Makeover program, we don’t just talk about debt payoff tactics. We go deep into:

    • Money mindset shifts that last.
    • Customised debt payoff strategies that work for your real life.
    • Credit confidence – so you’re empowered, not intimidated.
    • Saving alongside debt payoff to build true financial stability.

    It’s about creating a debt-free life you love – not one that feels like a punishment. 

    ? Ready to Take Action? (Mini Challenge!)

    Let’s finish this post with a quick action step to help you get started today.

    Debt Freedom Mini Challenge:

    1. Write down your current total debt balance – no judgment, just facts.
    2. Choose your preferred payoff method: Snowball (smallest balance first) or Avalanche (highest interest first).
    3. Set a realistic target date for your first major milestone – paying off ONE account.
    4. Automate your minimum payments, plus an extra small amount toward your top-priority debt.
    5. Start a tiny emergency fund – even just $10 this week – to protect your progress.

    Take one step at a time, and watch the momentum build.

    ? Final Thoughts: You’re Closer to Debt Freedom Than You Think

    Here’s what I want you to walk away with today: Debt freedom isn’t about punishment – it’s about empowerment. You don’t have to wait to feel good about your money – you can start now, even while in debt. Small, consistent shifts – both practical and emotional – are what create lasting change.

    And if you’re ready to take this work deeper – so you can finally break free from debt, grow your savings, and feel peaceful with your money? Your Financial Freedom Breakthrough™ – 90 Day Money Makeover program opens on September 10th. Inside, we’ll tackle:

    • Debt payoff (without shame or extreme restrictions).
    • Credit confidence (in plain English!).
    • Sustainable saving habits.
    • And the deep money mindset work that makes all the difference.

    This isn’t just another debt payoff plan, it’s a total transformation for your financial life. Get ready, friend – your next chapter starts soon.

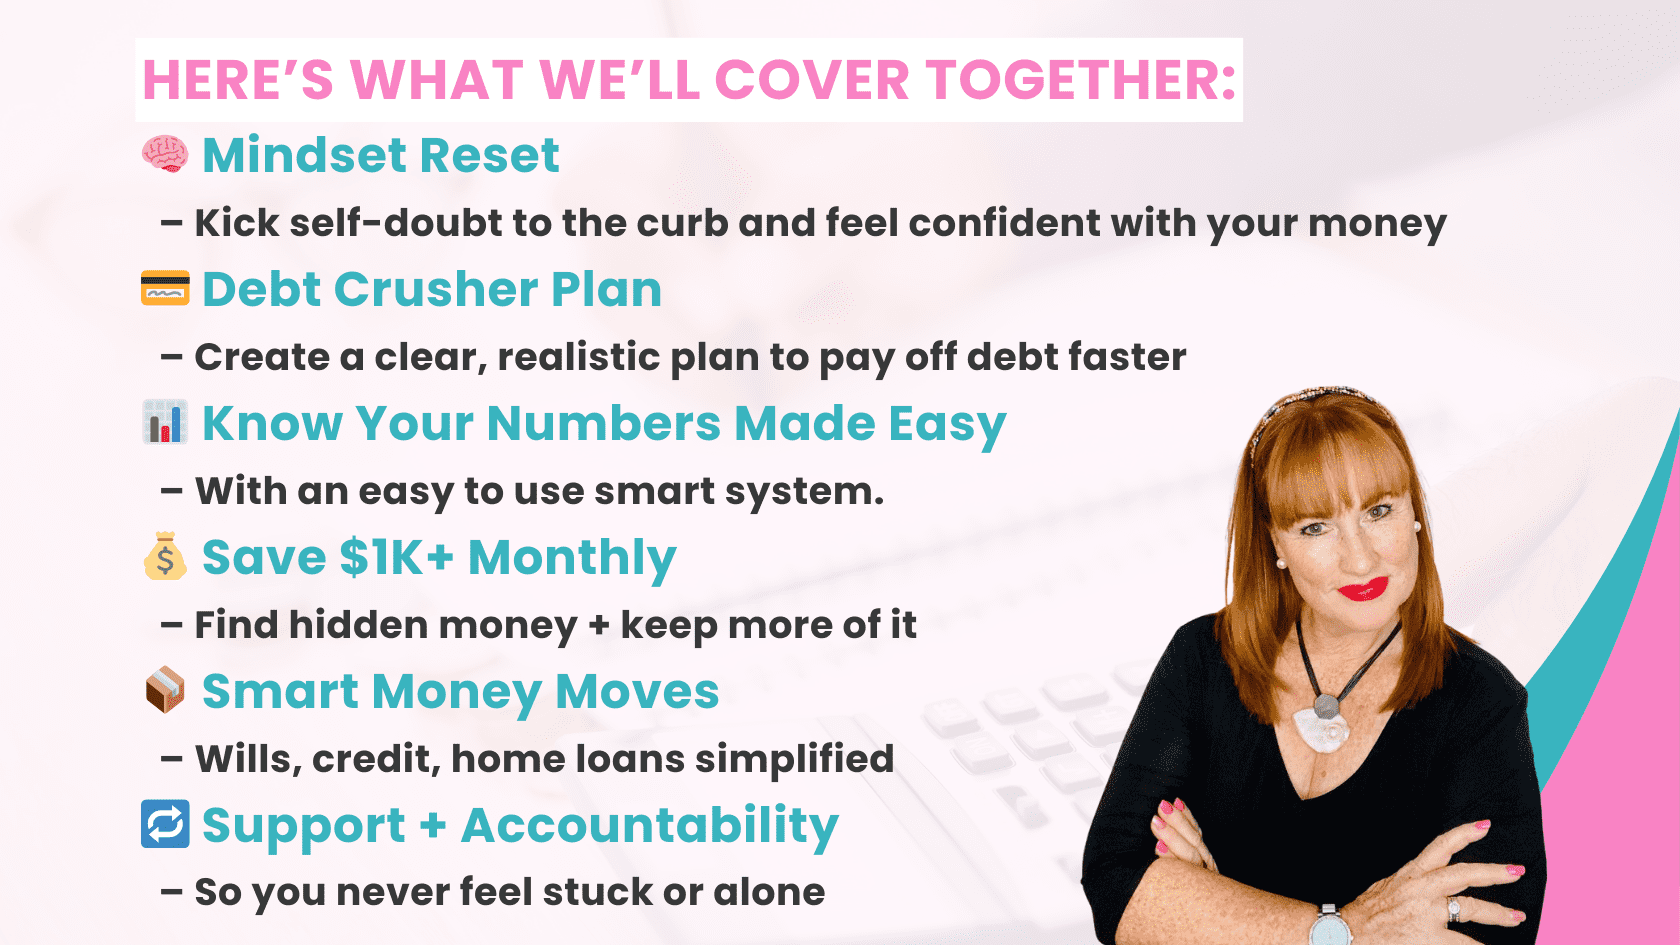
    Your Financial Freedom Breakthrough™
    Your Financial Freedom Breakthrough™ - Scope