Financial Stress at Work Is Real: How Employers Can Support Staff Through Uncertain Times

Financial Stress at Work Is Real: How Employers Can Support Staff Through Uncertain Times

Let’s talk about the thing many workplaces feel but few talk about openly.

Financial stress.

Right now, many employees are carrying a heavy mental load. Rising living costs, debt pressure, interest rate worries, and the emotional weight of trying to “hold it all together” can quietly affect how people show up at work.

The tricky part?
A lot of struggling employees do not look like they are struggling.

They still show up.
They still smile in meetings.
They still get the work done.

But underneath the surface, they may be losing sleep, feeling distracted, or wondering how they are going to stay on top of everyday life.

This is not just a personal issue. It is a workplace issue too.

The hidden impact of financial pressure

When an employee is stressed about money, it rarely stays neatly at home.
It follows them into the workday.

Financial stress can affect:

  • concentration
  • confidence
  • energy levels
  • productivity
  • decision-making
  • mental wellbeing
  • workplace engagement

And when it goes unaddressed for too long, people often do not just want more money.
They want relief.
They want stability.
They want support.

Sometimes, that means they leave.
When an employee is stressed about money, it rarely stays neatly at home.
It follows them into the workday.

Why a pay rise is not always the answer

This is where many employers get caught off guard.

They assume financial stress is only about income, so they respond with a pay rise when possible. While higher income can help, it does not automatically solve poor money habits, lack of structure, debt overwhelm, or financial anxiety.

Because financial wellbeing is not just about how much people earn.
It is also about how confidently they manage what they have.

That is why some employees can get a raise and still feel overwhelmed.
And why some workplaces offer perks, rewards, and recognition but still experience turnover, burnout, or disengagement.

People do not always leave for a bigger paycheck.
Sometimes they leave because they are chasing less stress.

What employees really need

In uncertain times, employees need more than surface-level support.
They need practical help that builds real confidence.

That can look like:

  • education that makes money feel less overwhelming
  • simple systems to manage spending and bills
  • tools to reduce financial chaos
  • strategies to tackle debt with a plan
  • guidance that helps them feel more in control
  • a safe, shame-free space to get support

When people feel financially stronger, they often feel emotionally stronger too.
And that changes how they show up in every area of life, including work.
The role employers can play

The role employers can play

Employers do not need to become financial advisers.
But they can become part of the support system.

A workplace that genuinely cares about financial wellbeing sends a powerful message:

“We see the pressure. We care about the person, not just the performance.”

That kind of support builds trust.
It strengthens loyalty.
And it helps create a workplace culture where people feel valued in a real way.

Simple ways employers can help include:

  • offering financial wellbeing education
  • normalising money conversations without stigma
  • providing access to coaching or structured support
  • recognising the connection between financial stress and performance
  • focusing on prevention, not just crisis response

Why this matters for business outcomes too

Supporting employee financial wellbeing is not just kind. It is smart.

When employees feel less stressed about money, businesses often benefit from:

  • improved focus
  • better productivity
  • lower turnover
  • stronger morale
  • healthier workplace culture
  • more trust between staff and leadership
When employees feel less stressed about money, businesses often benefit

In other words, supporting financial wellbeing is not a “soft” benefit.
It is a practical one.

And in times of uncertainty, practical support is exactly what people remember.

Comfort matters too

There is one more piece that deserves attention.

People do not just need solutions. They need reassurance.

Many employees are currently feeling shame about money. They may feel embarrassed that they are stressed. They may think they “should” have it sorted. They may stay silent because they would rather not look incapable.

That is why comfort matters.

It helps to remind people:

  • they are not alone
  • financial pressure is affecting many households
  • struggling does not mean failing
  • support is available
  • change is possible with the right tools and guidance

Sometimes the most powerful first step is simply helping someone feel seen.

Creating a more supportive workplace

If you are an employer, leader, or HR decision-maker, this is your opportunity to think bigger about what support really means.

Financial wellbeing is no longer a “nice to have”.
It is one of the most practical and human ways to support your team.

And it does not require overcomplicating things. It starts with awareness.

Then it moves into education, tools, and support that help people take back a sense of control.

A better path forward

The world feels heavy for many people right now. That is real. But so is the opportunity to respond differently.

Instead of waiting for burnout, disengagement, or unexpected resignations, employers can choose to act earlier.


They can offer support that helps employees feel steadier, calmer, and more capable. And when that happens, everybody wins.

If you want to support your team in a practical, meaningful way, my Financial Wellbeing Program helps employees build confidence, reduce money stress, and create healthier financial habits with real tools and support.

Because sometimes the best staff benefit is not another perk.
It is helping your people feel safer, stronger, and more in control of their lives.
Financial Wellbeing Program

#HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings 
 

The Foundations First: Why Small Business Owners Can’t Afford to Wing It Anymore

The Foundations First: Why Small Business Owners Can’t Afford to Wing It Anymore

If you’re a small business owner, tradie, franchisee, coach, or self-employed professional, chances are you didn’t start your business because you love spreadsheets, cashflow forecasts, or sorting out your accounts.

You started because you’re good at what you do.

You solve problems. You build things. You coach people. You create results. But somewhere along the way, many business owners find themselves working harder than ever and still feeling like they’re falling behind.

Money comes in.
Then it disappears.
Tax time rolls around and suddenly it feels personal.
You’re busy every day, yet you’re not fully sure whether your business is actually performing well.

Sound familiar?

Here’s the truth: being busy is not the same as being profitable.

And in today’s business world, “winging it” is no longer a strategy.

Why foundations matter more than ever

Strong businesses are not built on hustle alone. They are built on foundations.

That means knowing:

  • what money is coming in
  • what money is going out
  • what your pricing needs to be
  • whether your profit is real or just temporary relief
  • how much you can actually afford to pay yourself
  • what your numbers are telling you before problems get bigger

Without those foundations, growth gets messy fast.

More sales can actually create more pressure.
More clients can create more chaos.
More team members can expose weak systems.
And more revenue can still leave you with less cash than expected.

This is the trap so many business owners fall into. From the outside, things can look successful. Inside, it feels like stress, uncertainty, and constant financial firefighting.

Strong businesses are not built on hustle alone. They are built on foundations.

The Hidden Cost of Weak Foundations

When your financial systems are weak, everything takes more energy.

You make decisions based on gut feel instead of facts.
You underprice because you’re scared of losing work.
You mix personal and business spending and hope it all works out.
You avoid looking at reports because they feel overwhelming.
You stay in operator mode instead of stepping into your role as CEO.

The result?
You work harder, worry more, and enjoy your business less.

And let’s be honest, that is not why you started.

A business should support your life, not swallow it whole.

What Solid Business Foundations Actually Look Like 

Getting your foundations right does not mean making things more complicated.

It means making things clearer.

It looks like:

  • a simple cashflow structure you actually understand
  • separate systems for business and personal money
  • confidence around pricing, profit, wages, and expenses
  • a weekly and monthly rhythm for checking the right numbers
  • stronger boundaries around spending and decision-making
  • knowing where your money is leaking and how to plug it

When these basics are in place, something powerful happens.

You stop guessing.
You start leading.
You stop reacting.
You start planning.
You stop feeling behind.
You start building momentum.

You do not need more motivation. You need structure.

Many business owners think they need to feel more disciplined, more focused, or more inspired.

But often, that’s not the real issue.

The issue is that the business has grown beyond the systems holding it up.

You don’t need another pep talk.
You need a better framework.

You need simple tools that help you:

  • understand your cashflow
  • pay yourself consistently
  • price with confidence
  • stop tax shock before it happens
  • make decisions from a place of control

That is where real confidence comes from.
Not from hoping, but from knowing.

You don’t need another pep talk.
You need a better framework.

The Difference Between Surviving and Scaling

If your foundations are shaky, growth can break you.

That might sound dramatic, but it’s true.

A bigger business with poor systems often creates:

  • higher stress
  • tighter cashflow
  • more team issues
  • greater tax pressure
  • slower decision-making
  • more burnout

On the other hand, when your business foundations are strong, growth becomes more sustainable.
You can see what is working.
You can fix what is not.
You can make better decisions faster.
You can lead with more confidence and less panic.

That is the difference between surviving the month and building a business that genuinely funds your life.

    A Quick Self-Check for Business Owners

    Ask yourself:

    • Do I know exactly where my money is going each month?
    • Am I paying myself properly and consistently?
    • Do I understand the difference between revenue and profit in my business?
    • Do I have simple systems for cashflow, tax, and expenses?
    • Do I look at my numbers regularly, or only when I’m forced to?
    • Am I leading my business like a CEO, or just trying to keep up?


    Discomfort is not failure. It is feedback.

    If those questions feel a little uncomfortable, that’s okay.
    That discomfort is not failure.
    It is feedback.

    And it might be the exact sign that now is the time to strengthen your foundations.

    Your next step

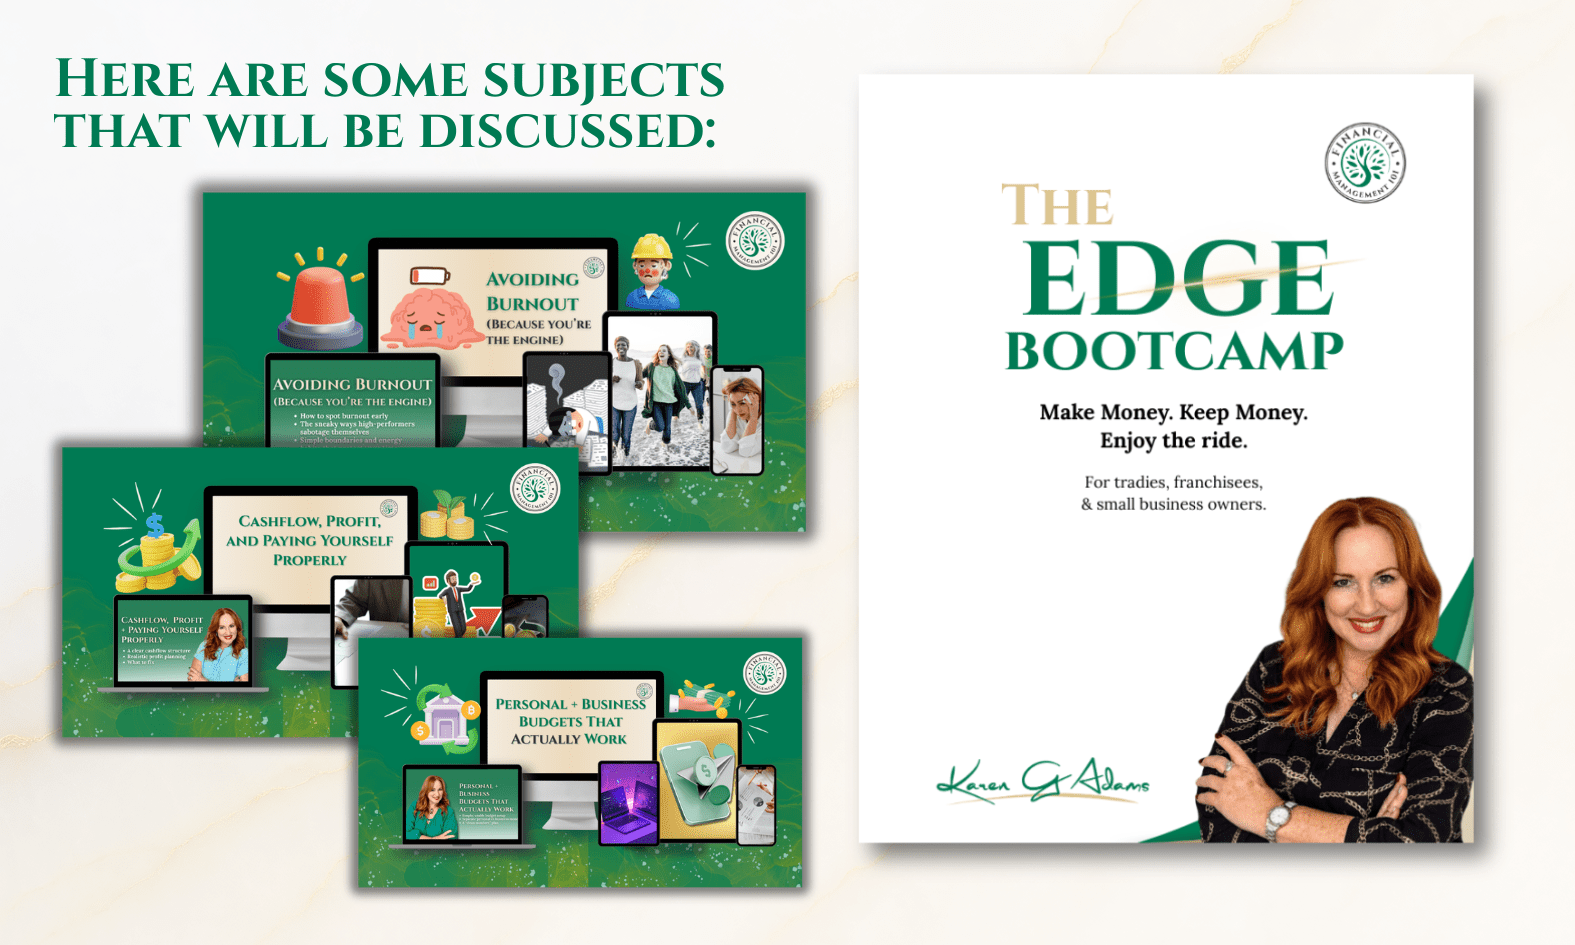
    If you’re done with money disappearing, messy systems, and feeling like you’re working too hard for too little clarity, this is exactly why I created The Edge Bootcamp.

    This is not fluff, theory, or feel-good motivation.
    It is practical training for tradies, franchisees, coaches, small business owners, and self-employed professionals who want to stop winging it and start running their business like a CEO.

    Inside the Bootcamp, we cover the foundations that matter most – cashflow, profit, pricing, paying yourself properly, budgets that actually work, business setup, reading your numbers with confidence, and building stronger systems for sustainable growth.

    Join me at The Edge Bootcamp in May and build the financial and business foundations your growth actually needs.


    Because the goal is not to be busier.
    The goal is to be stronger, smarter, and more profitable.

    Note: This event provides education and general information, not personalised financial, accounting, legal, tax, investment, or health advice. Seek advice specific to your circumstances from qualified professionals.

    The Edge Bootcamp

    #HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings 
     

    The Emergency Fund Isn’t Optional – How to Build One Without Feeling Broke (and why it changes everything)

    The Emergency Fund Isn’t Optional – How to Build One Without Feeling Broke (and why it changes everything)

    Let’s talk about the one money habit that turns chaos into calm faster than almost anything else:

    An emergency fund.

    Now before you roll your eyes and think, “Karen, I knowww… but I can barely afford groceries,” stay with me.

    Because I’m not about to tell you to magically save three months of expenses overnight, live on rice and sadness, and stop enjoying life.

    That’s not financial education – that’s financial punishment. 😅

    What I am going to do is show you how to build an emergency fund in a way that feels doable, realistic, and actually sticks… even if money is tight.

    And here’s why this matters:

    An emergency fund isn’t just “money in an account.”
    It’s peace, options, and less stress when life does what life does best… surprise you at the worst possible time.

    So let’s get your financial house in order by building the foundation that stops everything from wobbling.

    Why the Emergency Fund Is Non-Negotiable (Even If You Have Debt)

    I want you to imagine your finances like a house.

    If your foundation is cracked, everything else feels unstable:

    • you can’t plan properly
    • you can’t relax
    • you’re constantly bracing for impact
    • and one unexpected bill can knock you sideways

    An emergency fund is the foundation.

    It stops you from:

    • using credit cards “just this once”
    • grabbing BNPL for essentials
    • borrowing from family
    • draining your savings every time something happens
    • feeling like you’re always behind

    Even if you’re paying down debt, you still need a buffer.
    Because without one, every emergency becomes more debt… and that cycle is exhausting.

    An Emergency Fund Is Non-Negotiable Even If You Have Debt

    The Biggest Myth: “I’ll Start When I Have More Money”

    This is the #1 reason people delay emergency savings.

    They think:

    • “I’ll start when I get a pay rise.”

    • “I’ll start when the kids are older.”

    • “I’ll start when the cost of living calms down.” (lol… remember calm?)

    • “I’ll start when things settle.”

    But here’s the truth:

    Things don’t settle.
    You just get stronger and more organised.

    And you don’t get stronger by waiting.
    You get stronger by starting small and building consistency.

    You don’t need a massive emergency fund to change your life.
    You need the habit of saving, the system that supports it, and the confidence that you can handle surprises.

    What Counts as an “Emergency”? (Let’s Be Clear)

    If we don’t define “emergency,” your emergency fund gets eaten by:

    • sales

    • convenience spending

    • spontaneous “self-care” shopping

    • and that “it’s been a week” moment at Target 😄

    An emergency is:
    ✅ urgent
    ✅ necessary
    ✅ unexpected
    ✅ not in the budget

    Examples:

    • car repairs

    • urgent medical/dental

    • last-minute travel for family reasons

    • job loss or reduced income

    • essential home repairs

    • unexpected vet bills (pets are adorable little financial liabilities)

    Not emergencies:
    ❌ a holiday
    ❌ Christmas (it’s predictable, we plan for it)
    ❌ a new phone because your current one is “annoying”
    ❌ a birthday gift (also predictable)
    ❌ a sale (I don’t care how good the sale is)

    For those predictable costs, we use sinking funds (we’ll talk about that shortly).

    Emergency Fund vs Sinking Funds (The Difference That Changes Everything)

    This is a game-changer for getting your financial house in order.

    Emergency fund:

    For true, unexpected emergencies.

    Sinking funds:

    For expected expenses that don’t happen weekly or monthly but absolutely happen:

    • car rego and insurance
    • school expenses
    • rates
    • Christmas
    • birthdays
    • holidays
    • annual subscriptions
    • car servicing

    When people don’t have sinking funds, they call predictable bills an “emergency”… and then their emergency fund never grows.

    So yes, we want both. But we start with a buffer first.

    Step One: Build a “Stress Buffer” (The First Goal)

    Forget “3 months of expenses” for a second.

    Your first goal is what I call a Stress Buffer:

    • $500 if you’re starting from scratch
    • $1,000 if you have a bit more breathing room

    This amount won’t solve everything, but it will stop the small stuff from turning into drama.

    And you know what? When you see that balance grow, something shifts.

    You start trusting yourself. You feel less panicked. You stop living on the edge of your bank balance.

    That’s financial muscle building in real time.

    “But I Can’t Save” – Yes You Can (Here’s How)

    I’m going to say this kindly:

    Most people can save something.
    They just haven’t had a system that makes it automatic and non-negotiable.

    Here are practical ways to start, even if you’re on a tight budget.

    1) The Micro-Save Method

    Start with:

    • $10 a week

    • or $25 a fortnight

    • or $2 a day

    Yes, it feels small. But small done consistently becomes powerful.

    The goal is not the amount at the start.
    The goal is building the identity of: “I’m someone who saves.”

    2) The “Pay Yourself First” Transfer

    This is the most important strategy of all:

    Set up an automatic transfer on payday into a separate account called:

    • “Emergency Fund”

    • “Stress Buffer”

    • “Do Not Touch” 😄

    • “Future Me’s Peace”

    When it’s automatic, you don’t have to think about it.

    And thinking less about money is the dream, isn’t it?

    3) The Round-Up Hack

    Many banks let you round up purchases and move the difference into savings.

    It’s not life-changing on its own, but combined with automation?
    It’s a lovely little boost.

    4) The “Found Money” Rule

    Any unexpected money goes to the emergency fund until you hit your first goal:

    • tax returns

    • bonuses

    • cashback

    • refunds

    • gifts

    • overtime

    You can still enjoy some of it – I’m not a monster – but Future You gets first dibs until your foundation is built.

    Where to Put Your Emergency Fund (So You Don’t Accidentally Spend It)

    This part matters because if your emergency fund is sitting next to your spending money… it will be treated like spending money.

    Human brains do not like temptation.

    Here’s the rule:
    ✅ separate account
    ✅ not linked to your everyday card
    ✅ easy enough to access in an emergency, but not instant-grab easy

    A high-interest savings account is often a good option for many people, but the key isn’t the interest rate – it’s the separation.

    If you have to take one extra step to access it, you’ll be less likely to raid it for non-emergencies.

    How Much Should Your Emergency Fund Be?

    Once you’ve built the Stress Buffer, you can level up.

    Here are the common tiers:

    Tier 1: $500–$1,000 Stress Buffer

    Stops small emergencies becoming debt.

    Tier 2: 1 month of essential expenses

    Covers short-term hiccups.

    Tier 3: 3 months of essential expenses

    A solid safety net for most households.

    Tier 4: 6 months of essential expenses

    Great if you’re self-employed, commission-based, or in an industry with variable work.

    Important: You don’t have to build this in a week. You build it steadily and that’s what makes it sustainable.

    The “Life Is Lifey” List: Why Emergencies Keep Happening

    Here are just a few things I see all the time:

    • the car decides it’s done with life
    • unexpected house repair
    • the hot water system taps out
    • the dog eats something it shouldn’t (again)
    • a dentist visit becomes a “how is this $800?” moment
    • your kid needs something for school tomorrow
    • your income changes unexpectedly


    These aren’t rare events. They’re predictable unpredictables.

    And when you have an emergency fund, you stop being shocked and start being prepared. That is the point.

    Life Emergencies Keep Happening

    What If You’re Paying Off Debt?

    Here’s my professional but real-life approach: If you have debt, you still build a Stress Buffer first.

    Why? Because without it, you’ll keep going back into debt every time something happens.

    A simple strategy is:

    1. Build $500 – $1,000 buffer
    2. Focus on debt payoff
    3. Build 1 month expenses
    4. Continue debt payoff + build sinking funds
    5. Build to 3 months expenses

    This is balanced. Realistic. And it reduces stress.

    How to Make Saving Feel Less Painful (Because Yes, It Can)

    Saving can feel like deprivation when your brain believes money is scarce.

    So we make it feel lighter by doing two things:

    1) Make it automatic

    If you’re relying on motivation, you’ll save only when you feel inspired.

    And motivation is… inconsistent. Automation builds wealth quietly.

    2) Give your savings a purpose

    Calling it “Savings” is boring. Calling it “Freedom Fund” or “Peace Buffer” hits differently.

    Name it like it matters, because it does.

    The Secret to Getting Your Financial House in Order: One System That Runs Without You

    Here’s the truth:

    Most people don’t fail at money because they don’t care.
    They fail because they don’t have a system, they’re doing everything manually, with willpower, while stressed.

    And that’s like trying to carry groceries without bags. Possible… but messy and exhausting.

    A system looks like:

    • separate accounts
    • automatic transfers
    • sinking funds for predictable costs
    • a weekly 10-minute money check-in
    • clear rules for what is/isn’t an emergency

    This is what creates calm.

    Want Help Building This (So It Actually Sticks)? Join the Membership.

    If you’ve read this and thought:

    “I want this, but I need help setting it up.” or “I’ve tried to save before and it disappears.” or “I need a plan that’s realistic for my life.”

    That’s exactly why I created my Membership.

    Inside the Membership we don’t just talk about emergency funds – we build the whole system:
    ✅  Your Stress Buffer plan (based on your income and expenses)
    ✅  Automated transfers so saving happens without willpower
    ✅  Sinking funds so predictable expenses stop feeling like emergencies
    ✅  Amoney map so your cash flow has structure
    ✅  Support and guidance so you don’t fall off track

    You don’t need to “try harder.” You need the right strategy and ongoing support.

    If you’re ready to stop living one unexpected bill away from stress, join the Membership.
    Let’s build your emergency fund, get your financial house in order, and help you feel calm with money again for good.

    Join The Membership at Financial Management 101

    #HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings 
     

    Why Do Most People Fail at Their New Year’s Resolutions and How Can I Actually Stick to My Financial Goals This Year?

    Why Do Most People Fail at Their New Year’s Resolutions and How Can I Actually Stick to My Financial Goals This Year?

    New Year, Same Resolutions? Let’s Talk About It.

    Ahhh January the month of green smoothies, gym selfies, and freshly purchased planners that are definitely going to change your life this time, right?

    If you’re like most people, you’ve probably made a few New Year’s resolutions that sounded amazing on January 1st… but by February? They’re long forgotten, buried under Uber Eats receipts and good intentions.

    And when it comes to money goals? Ohhh, this is where the guilt hits hard.

    So let’s break it down: Why do New Year’s resolutions fail and what can you do instead to actually stick to your financial goals this year?

    Spoiler: It’s not about willpower. It’s about building financial muscle and that’s what I help people do every day.

    The Stats Don’t Lie – Most Resolutions Don’t Last

    According to research:

    • 43% of people expect to fail their resolutions by February
    • Only 9% actually feel successful by the end of the year
    • The most common failed resolutions? Diet, fitness… and yes — money

    Why? Because most resolutions are made in the heat of a moment – not rooted in a system, a strategy, or support.

    We say things like:

    • “I’m going to save $5,000 this year!”
    • “I’m cutting up ALL my credit cards!”
    • “I’ll never spend money on takeout again!”

    …but we don’t have a real plan behind it. Just hope, hype, and maybe a pretty notebook.

    New Year’s Resolutions

    Why Financial Resolutions Fail: The Real Talk

    Here’s what I’ve seen in my coaching practice over and over:

    1. The goal is too vague.
      “Get better with money” isn’t a goal – it’s a wish. Your brain doesn’t know what to do with that.
    2. There’s no timeline.
      Saving “someday” or “this year” doesn’t create urgency or clarity.
    3. You try to do too much, too fast.
      Going from zero to “never spending a dollar unless it’s pre-budgeted” is like deciding to run a marathon when you haven’t walked around the block in months.
    4. No accountability.
      When you’re the only one who knows your goals… it’s easy to quit. Life gets busy, bills pile up, and suddenly, your “big resolution” is a tab you closed weeks ago.
    5. Shame gets in the way.
      One slip-up, and your inner critic screams, “See?! You always mess this up!” And so you give up again.

    Sound familiar?

    So What Actually Works? (This Is Where It Gets Fun)

    Instead of setting rigid resolutions, try this instead:

    ✅ Set Clear Financial Intentions – Not Punishments

    Financial intentions focus on who you want to become and how you want to feel – not just what you want to do.

    For example:

    • “I want to feel peaceful when I check my bank account.”
    • “I want to be someone who saves consistently.”
    • “I want to feel proud of my money decisions.”

    From there, we build small, tangible goals that align with that intention. That’s the sweet spot.

    ✅ Build Micro Goals That Stack Into Momentum

    Instead of “Save $5,000 this year,” try:

    • “Transfer $100 every payday to my savings account.”
    • “Do 1 no-spend weekend per month.”
    • “Track my spending daily for 30 days.”

    These small actions feel doable and when done consistently, they change everything.

    ✅ Have a System – Not Just a Goal

    Anyone can write a goal. But what’s your system to get there?

    Here’s a basic system I teach inside my Financial Muscle Coaching:

    1. Weekly money check-ins (10 minutes)
    2. Monthly budget reviews
    3. Track 1 habit at a time (like spending or debt payments)
    4. Celebrate progress every month.

    Have a Money Budgeting System

    Systems create structure and structure creates success. Don’t wait – join the membership now and start living your best life from today.

    Join Financial Muscle Coaching Now

    #WhyDoResolutionsFail #HowToStickToFinancialGoals #WhyCantIKeepNewYearGoals #NewYearMoneyResolutionHelp #HowToMakeMoneyGoalsThatLast #MoneyGoalsNotResolutions #HowToStayMotivatedWithMoney #BreakTheCycleWithMoney #SmartFinancialGoals2025 #BuildBetterMoneyHabits #NewYearsResolutionFail #MoneyGoals2025 #FinancialGoalsThatStick #BudgetGoals #MoneyHabits #ResolutionReset #MoneyCoaching #FinancialMuscle #GoalSettingTips #SmartMoneyMoves 

    From Fear to Freedom: Rewiring Your Money Beliefs for Good (How to Break Free from Financial Anxiety and Finally Take Control)

    From Fear to Freedom: Rewiring Your Money Beliefs for Good (How to Break Free from Financial Anxiety and Finally Take Control)

    Let’s Talk About Fear…

    We don’t like to admit it… But fear is driving way more of our financial decisions than we realise.

    • Fear of not having enough


    • Fear of messing it up


    • Fear of making the wrong choice


    • Fear of looking stupid, selfish, or irresponsible


    • Fear of repeating past mistakes


    Fear whispers, “You’ll never get ahead.”
    Fear says, “Better play it safe.”
    Fear convinces us that we’re not smart enough, disciplined enough, or lucky enough to get it right.

    But here’s the truth: Fear doesn’t protect your finances – it paralyses them.

    Where Fear-Based Money Beliefs Come From

    You weren’t born afraid of money. You learned fear – often without even knowing it.

    Maybe you grew up watching your parents fight about bills. Or maybe money was tight, and you internalised the message: “There’s never enough.” Maybe a big mistake left you feeling ashamed, and now you avoid money altogether.

    Whatever the story, the result is the same: You’re stuck making decisions from a place of fear, not freedom.

    The Cost of Financial Fear

    Fear shows up in sneaky ways:

    • You avoid opening bills
    • You put off financial planning
    • You overspend to feel better (hello, retail therapy)
    • You say yes when you mean no – because you’re afraid to “miss out”
    • You hoard money and still feel unsafe
    • You stay small, stuck, and stressed

    It’s not because you’re lazy or irresponsible. It’s because fear is running the show.

     And here’s the breakthrough: You can reprogram your fear-based beliefs  and unlock a completely new financial reality.

    Beliefs = Behaviors = Bank Balance

    In Master Your Money, I teach that your beliefs create your results. Full stop! Let’s look at a few common fear-based beliefs and what they lead to:

    Fear-Based Belief Behavior Result
    “I’m not good with money.” Avoid finances altogether Confusion & anxiety
    “Money is never enough.” Scarcity mindset, hoarding Constant stress
    “I always mess it up.” Self-sabotage Lack of progress
    “People like me don’t build wealth.” Low risk tolerance Missed opportunities

    If you want to change your behaviour, you have to start with the belief that’s fueling it.

    How to Rewire Fear Into Empowerment

    Here’s the 3-step belief flip framework we use in the program and you can try it right now.

    ✍️ Step 1: Name the Fear

    What’s the thought that’s been keeping you stuck?

    “I’ll never be financially secure.”

    Step 2: Flip the Belief

    Ask yourself, What’s a more empowering version of this belief?

    “I am learning how to create financial security – one step at a time.”

    Step 3: Speak It Daily

    Say your new belief out loud every day. Especially when fear creeps in.

    “I am creating safety and stability through intentional choices.”

    “I am learning how to create financial security - one step at a time.”<br />

    Powerful Affirmations to Rewire Fear-Based Thinking

    Start repeating these daily and feel the shift begin:

    1. “I trust myself to make wise financial decisions.”


    2. “It is safe for me to grow, earn, and invest.”


    3. “I am not my past – I create my financial future.”


    4. “I welcome abundance into my life with confidence.”


    5. “Every decision I make brings me closer to financial peace.”

    These aren’t fluffy phrases, they are neural rewiring tools backed by the science of neuroplasticity.

    How to Handle Fear in Real Time

    Here’s what to do when fear pops up (because it will):

    1. Pause – Don’t make the decision immediately. 
    2. Name the fear – “I’m afraid I’ll mess this up.” 
    3. Breathe and ground – Get back to the present. 
    4. Ask – “What would future-me, who trusts herself, do right now?”
    5. Act with intention – Even a small move toward courage shifts everything.

    Client Story: From “I Can’t” to “I’m In Control”

    When Mel joined the Master Your Money program, she was terrified of looking at her finances. She hadn’t opened a credit card bill in 6 months.

    “I just kept telling myself I was bad with money,” she said. “I felt frozen.”

    Together, we rewrote that belief. Her new mantra? “I’m learning to lead my finances with courage.”

    She committed to one 10-minute financial action a day. Within 30 days, she’d:
    ✅ Paid off two lingering bills
    ✅ Set up automated savings
    ✅ Felt confident opening her banking app

    Her financial situation didn’t change overnight – but her mindset did. And that changed everything.

    The Transformation: From Fear to Freedom

    When you start making money decisions from a place of empowerment, you begin to:

    • Trust yourself
    • Take consistent action
    • Let go of shame
    • Step into the driver’s seat of your financial future

    This is the shift we make in the Master Your Money program. Because real transformation doesn’t happen through guilt or hustle. It happens through mindset + habits + belief.

    Ready to Ditch Financial Fear for Good?

    Inside the 30-Day Master Your Money program, we walk step-by-step through:
    ✅ Identifying and rewiring limiting beliefs
    ✅ Shifting from scarcity to abundance
    ✅ Creating emotional safety around money
    ✅ Replacing fear with confidence, clarity, and calm

    Whether you’re paying off debt, growing your income, or just trying to feel good about your bank account again, this program gives you the tools to stop reacting and start rising.

    “Freedom begins the moment you stop letting fear make your decisions.”

    Final Thoughts

    You are not broken.
    You are not bad with money.
    You are not behind.

    You’ve just been living with fear-based programing that no longer serves you.
    And today – you get to choose something better.

    You get to choose freedom.

    Click here to join Master Your Money and start rewriting your money story.

    Your Financial Freedom Breakthrough™<br />