Father’s Day and the Business Owner Who Can’t Switch Off

Father’s Day and the Business Owner Who Can’t Switch Off

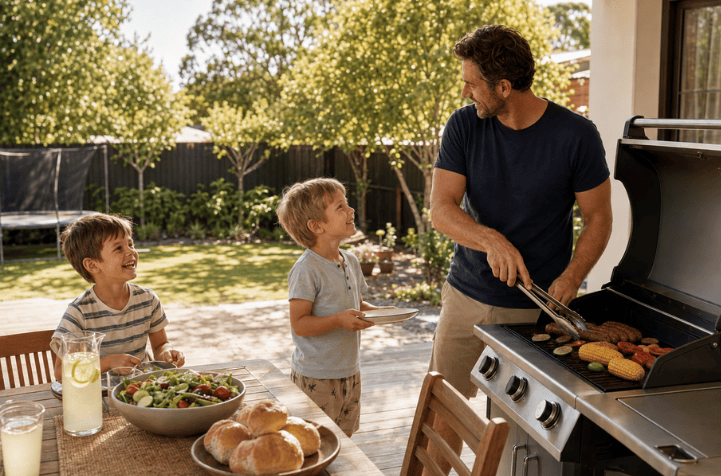
Happy Father’s Day to every business owner who “just needs to check one email” during the barbecue.

You know the scene. Phone face-down on the table, out of principle. Two minutes later, face-up again. “Just checking something quick.” Forty-five minutes later, still checking, while someone’s asking if you want another sausage and you’re not entirely sure you heard them the first time.

Here’s the bit nobody says out loud; if you genuinely can’t switch off for one Sunday, it’s not because you’re dedicated, it’s because something in the business is relying entirely on you being switched on, all the time. That’s not commitment. That’s a business that hasn’t had its systems built yet, quietly telling on itself every time your phone lights up at a family lunch.

I say this with love, because I’ve been that person too. There’s a particular kind of guilt that creeps in when you’re not checking, like something’s about to fall over the second you look away. Sometimes it will. That’s actually useful information, not a personality flaw. It tells you precisely where the weak point is, rather than leaving you to vaguely feel like you should “be better at switching off,” which is advice with nothing practical underneath it.
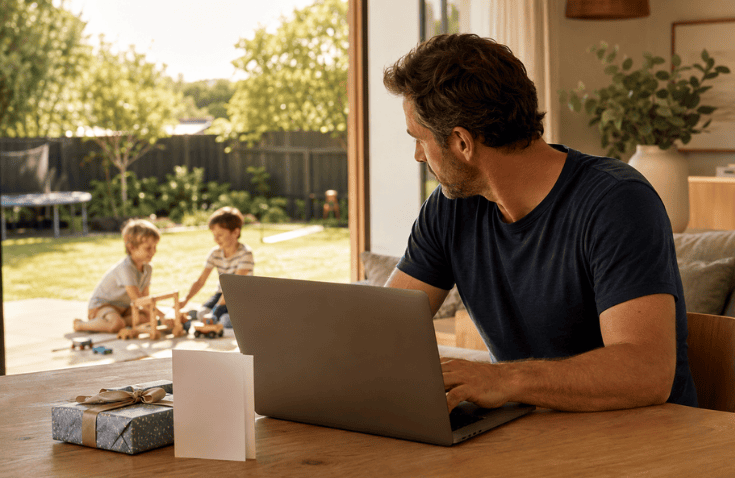
Happy Father's Day to every business owner who "just needs to check one email" during the barbecue.

It’s not a discipline problem

Most business owners think the fix is “just try harder to unplug.” Buy a nicer phone case, set a screen time limit, promise yourself Sunday is sacred. And then Sunday arrives and none of it holds, because the willpower was never the actual problem.

You can’t discipline your way out of a business with no systems, no visibility, and nobody else who knows where anything lives. If you’re the only one who knows the client’s login, the only one who knows how the invoicing actually works, the only one who can answer “did that order go out,” then of course you can’t switch off – you’re not being undisciplined, you’re being the entire operations department in one exhausted human body.

The phone-checking isn’t the actual problem. It’s just the symptom you can see. Fixing the symptom without fixing the cause is like taking the batteries out of a smoke alarm because the beeping is annoying.

What it costs, quietly

There’s a cost to this that doesn’t show up on the profit and loss but shows up everywhere else. It shows up in the conversation you half-listened to. The moment with the kids you were technically present for but not really in. The mate who stopped inviting you to things because you always seemed distracted, or cancelled at the last minute, or spent the whole time with one eye on your phone. None of that gets tracked anywhere. It just quietly accumulates until one day you notice the gap.

The real question to ask

The more useful question isn’t “how do I switch off more.” It’s “what would genuinely happen today if I didn’t check my phone at all?” If the honest answer is “everything would fall apart”, that tells you exactly where the gaps are. Not a criticism. A map.

Sit with that answer for a second. Is it really everything, or is it one or two specific things? Usually, when people actually write it down, the list is shorter than the panic suggested. There’s something almost funny about how big the fear feels compared to how short the actual list turns out to be once it’s on paper instead of in your head.

Building the buffer, one piece at a time

You don’t need to overhaul the whole business in a weekend to get some breathing room back. Start with the smallest, most repeated interruption, the thing that pulls you out of family time most often and ask what it would take to hand even part of that off. A simple checklist someone else can follow. A shared login instead of a personal one. An automated reminder instead of you personally remembering. None of these are big, dramatic fixes. They’re small, boring, unglamorous changes, and they’re exactly the ones that actually stick.

One small fix before the next family day

Before your next family day, try this. Write down the three things that would actually need you if they went sideways. Then ask yourself, honestly, whether one of those three could be handled by a simple checklist, a bit of automation, or someone else entirely, instead of by you personally, every single time. Fix one. That’s next Father’s Day a little more sorted than this one and the one after that, a little more sorted again. This isn’t a one-weekend fix. It’s a habit of slowly handing things off until your presence isn’t the only thing holding the whole operation together.

A better business creates a better life and a better life includes actually being at the barbecue, present for the conversation, not just physically there while mentally reconciling last month’s invoices.

The version of success worth aiming for

There’s a version of business success that gets celebrated a lot, the one measured in revenue, growth, how many staff you’ve got, how big the operation’s gotten. It’s a fine measure, as far as it goes. But it misses something important, which is whether the person who built all of that can actually enjoy a Sunday without their phone glued to their hand.

I’d argue the better measure of success is this – can you take a full day off, properly off, and come back to a business that’s still standing, without having spent the whole day half-present because part of you never left? That’s a much harder thing to build than revenue, and it’s a much better thing to have.
Building the systems that let you switch off isn't a luxury add-on. It's kind of the whole point of doing this in the first place.

Kids notice more than we think

There’s a particular moment a lot of business-owner parents have at some point; a kid saying something like “you’re always on your phone,” delivered completely matter-of-factly, no drama attached, which somehow makes it land harder than if they’d shouted it. Kids don’t measure your love by how hard you’re working for their future. They measure it by whether you were actually there when they wanted to tell you something, show you something, or just have you sitting next to them doing nothing in particular.

That’s not a guilt trip, plenty of us are working exactly because we want a better life for them. It’s just worth remembering that the “better life” bit doesn’t only mean money down the track. It means you, actually present, more often than not.

Building the systems that let you switch off isn’t a luxury add-on. It’s kind of the whole point of doing this in the first place.

If you want help working out exactly where your business is leaning on you too hard, The CEO Dashboard is built for precisely that, a clear look at what’s actually relying on you, and what could run perfectly well without you for a Sunday afternoon.
The CEO Dashboard

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess
#EntrepreneurMindset
 

Your Team Might Look Fine – But Financial Stress Could Be Costing More Than You Think

Your Team Might Look Fine – But Financial Stress Could Be Costing More Than You Think

“They seem fine.”

It is one of the most common assumptions leaders make.
And to be fair, it is an easy one to make.

Most employees are not walking into work announcing that they are worried about bills, debt, interest rates, or the rising cost of everyday life.

They keep going.
They keep performing.
They keep pushing through.

But financial stress has a way of showing up quietly.

It can look like a distraction.
Low energy.
Mood changes.
Reduced confidence.
Increased absenteeism.
Burnout.
Or eventually, a resignation that seems to come out of nowhere.

The employee looked fine.
But they were not fine.

The silent pressure many employees are carrying

The current financial climate is affecting people in deeply personal ways.
Even capable, high-performing employees can be under enormous pressure.

When money stress builds, people can feel:

  • mentally overloaded
  • emotionally flat
  • ashamed to ask for help
  • trapped in a cycle of stress and avoidance
  • worried about keeping up with household costs
  • fearful about debt, repayments, or unexpected expenses

And because money is still a sensitive topic, many employees suffer in silence.

That silence can be expensive.

The current financial climate is affecting people in deeply personal ways.
Even capable, high-performing employees can be under enormous pressure.

Why this is bigger than employee perks

Free lunches, social events, and workplace rewards all have their place.
But they do not solve financial anxiety.

When someone is lying awake worrying about bills, a pizza party is not going to restore their peace of mind.

This is why financial wellbeing deserves more attention inside workplaces.
It addresses a real problem that affects people’s everyday lives and their capacity to function well at work.

It is practical. It is human. And right now, it is incredibly relevant.

What financial wellbeing support actually does

A strong financial wellbeing approach helps employees move from stress and confusion to clarity and confidence.

That might involve helping them:

  • understand where their money is going
  • create simple systems that reduce overwhelm
  • identify savings opportunities they have missed
  • tackle debt with a clearer plan
  • improve money habits and mindset
  • feel more hopeful and less stuck

Notice that this is not about judgement. It is about support.

Financial pressure can affect anyone. The goal is not to shame people for needing help. The goal is to give them tools that genuinely make life feel more manageable.

What employers gain when they take this seriously

When businesses support staff with financial wellbeing, the impact can ripple through the whole workplace.

You may see:

  • better focus and engagement
  • increased productivity
  • lower staff turnover
  • stronger trust and loyalty
  • reduced burnout risk
  • a more supportive workplace culture

People remember employers who support them through hard seasons.
Not just with words, but with meaningful action.

Reassurance is part of support

Let’s pause here for something important.

If you are an employee feeling the pressure right now, please hear this:

You are not weak.
You are not bad with money just because things feel hard.
You are not the only one feeling stretched.

This season may be challenging, but it does not define you.
With the right support, practical tools, and small consistent changes, things can improve.

And if you are an employer reading this, never underestimate how powerful it is to create a workplace where people feel safe to get support before they hit breaking point.

    Reassurance is part of support

    Support before crisis is the smarter move

    Too often, workplaces respond after the damage is done.
    After the burnout.
    After the resignation.
    After the drop in performance.
    After the personal crisis spills into professional life.

    But early support changes that.

    When businesses proactively offer financial wellbeing resources, they help staff build resilience before the pressure becomes overwhelming.
    That is better for the employee and better for the organisation.

    A more compassionate and practical workplace benefit

    There is a reason financial wellbeing is becoming such an important conversation.
    It sits at the intersection of performance, retention, mental wellbeing, and culture.

    It is not about fixing everything overnight.
    It is about giving people a starting point.
    A plan.
    A sense that they are not alone.
    A pathway back to confidence.

    And in uncertain times, that kind of support matters more than ever.

    My Financial Wellbeing Program helps workplaces support staff with practical money tools, confidence-building education, and real guidance that reduces stress and strengthens wellbeing.

    Because when your people feel better about money, they often feel better at work too.

    And that is good for everyone.

    Financial Wellbeing Program

    #HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings 


    Tax Time Without the Panic – The Simple Systems That Keep More of Your Hard-Earned Money

    Tax Time Without the Panic – The Simple Systems That Keep More of Your Hard-Earned Money

    Tax Time Shouldn’t Feel Like a Horror Movie

    If “BAS” makes your eye twitch or tax time feels like a jump scare, you’re not alone.

    For many business owners, tax time looks like:

    • digging through email for receipts
    • trying to remember what that transaction was
    • realising GST money has been accidentally spent
    • asking your accountant, “Is this bad?” 😅
    • promising yourself (again) that you’ll get organised next year

    Whether you’re a tradie, franchisee, coach, consultant, or self-employed professional, it’s easy for tax to become the thing you avoid… until you can’t.

    But here’s the thing:
    Tax panic isn’t a personality trait. It’s a system issue.

    And the solution isn’t “try harder.”
    It’s: build foundations that make tax time boring.

    Boring is the goal.
    Boring means organised.
    Boring means you’re in control.

    The Real Reason Tax Time Feels So Stressful

    Most tax stress comes from one (or more) of these:

    1) You’re spending money that isn’t actually yours

    If GST/tax isn’t separated, the bank balance lies.

    It looks like there’s cash available… but a chunk of that cash belongs to the ATO (or will soon). So when BAS hits, it feels like a crisis.

    2) Your numbers aren’t clean

    Mixed transactions, personal spending from business accounts, inconsistent invoicing, missing receipts – these all make reporting harder.

    And when reporting is hard, you avoid it.

    3) You don’t have a simple routine

    If you only look at your money when something is due, you’ll always be reacting.

    4) You’re not clear on what’s “normal”

    Many owners don’t know what to expect from their obligations (GST, PAYG, super, income tax, etc.). That uncertainty turns into anxiety.

    The fix is not complicated, but it does require a shift from reactive to proactive.

    Owner Pay Is the Cornerstone of a Healthy Business

    The “Tax Calm” Blueprint (Simple, Practical, Repeatable)

    Let’s build tax calm from the ground up.

    Step 1: Separate business and personal (because clarity = calm)

    This is the first domino.

    When business and personal are mixed:

    • profit looks different than it really is
    • expenses get miscategorised
    •  your accountant has to untangle it (costly + time-consuming)

    •  BAS reporting becomes messy

    • tax estimates become unreliable

    When you separate them, your numbers get clearer fast. Even if you’re not ready to overhaul everything, start with this:

    • separate bank accounts (or at least strict allocation “buckets”)
    • a clear rule: business expenses only from business, personal only from personal
    • owner pay transferred as owner pay (not random withdrawals)

    This one change reduces stress massively.

    Step 2: Quarantine GST/tax weekly (so it never surprises you again)

    If you do nothing else after reading this blog, do this one thing.

    When GST and tax are quarantined weekly:

    • you stop “accidentally spending” future obligations
    • BAS becomes a planned payment
    • your cash flow becomes more reliable
    • you feel calm because you know the money is there

    A simple habit: Each week (or each time income lands), transfer a percentage into a tax/GST bucket

    The right percentage depends on your structure and circumstances (and this is where your accountant or qualified adviser can guide you). But the foundation is non-negotiable:

    Set aside first. Spend second.

    Step 3: Create a weekly money routine (30 minutes that changes everything)

    You don’t need a full day of admin.

    You need a repeatable routine.

    Pick one day per week – your “money check-in.”

    On that day, you:

    1. review what came in
    2. allocate GST/tax set-aside
    3. check bills due in the next 7 – 14 days
    4. confirm owner pay
    5. quickly check that transactions are being categorised correctly
    6. look at ONE key number (margin, break-even, or cash runway)

    That’s it.

    This is how tax time becomes boring, because you’ve been managing it in small pieces all year.

    Step 4: Keep records simple (no one’s trying to win an admin award)

    Receipts and records are one of the biggest stress points, so let’s make it easy.

    Your goal is not “perfect bookkeeping.”
    Your goal is “good enough that nothing becomes a disaster.”

    Simple record habits that help:

    • snap receipts immediately (or forward them to a dedicated email)
    • keep a consistent filing approach (even if it’s just “by month”)
    • reconcile regularly (weekly or fortnightly)
    • don’t leave it until BAS is due

    Future you will thank you.

    Step 5: Understand the 3 reports that remove the fear

    You don’t need to become an accountant, but you do need to feel confident in the basics.

    These three reports reduce stress instantly:

    1. Profit & Loss (P&L): tells you if the business is making money
    2. Balance Sheet (basic understanding): tells you what the business owns/owes
    3. Cash Flow position: tells you what’s actually available and what’s coming

    You’ll build confidence understanding key reports, including Xero if you use it (and the principles still apply if you use other systems).

    Confidence with these reports is what stops tax time feeling like a mystery.

    The Hidden Cost of Tax Panic (It’s Not Just the Bill)

    Tax panic doesn’t only cost you money. It costs you:

    • time (scrambling, chasing receipts, fixing mistakes)
    • stress (constant background anxiety)
    •  decision fatigue (avoiding choices because you don’t trust your numbers)

    • opportunity (hesitating to invest, hire, grow, or take time off)


    When your numbers are clean and your system is simple:

    • you price more confidently
    • you choose better clients 
    • you stop discounting out of fear
    • you plan ahead instead of catching up 
    • you keep more of what you earn (because you stop leaking money through chaos)

    Common “Tax Time Traps” (and how to avoid them)

    Here are the patterns I see all the time:

    Trap #1: “I’ll sort it out when it’s quieter”

    If you’re a tradie or franchisee, it might never get quieter.
    If you’re a coach/consultant, the quiet seasons are often when you’re building the next offer.

    Solution: a weekly rhythm. It’s small enough to do even when busy.

    Trap #2: “My accountant will handle it”

    Your accountant is essential, but they shouldn’t be your emergency clean-up crew.

    Solution: you handle the foundation; they handle the strategy and compliance.

    Trap #3: “I’m scared to look”

    Avoidance creates bigger problems.

    Solution: start with one number, one routine, one week at a time.

    Trap #4: “I don’t use Xero so I can’t get organised”

    Tools help, but tools aren’t the solution.

    Solution: the system works regardless of platform. (Xero is just a tool; your habits are the strategy.

    What “Tax Calm” Looks Like in Real Life

    When you’ve built foundations, tax time becomes:

    • “Yep, that’s due – money’s already set aside.”
    • “My reports make sense.”
    • “My accountant has what they need.”
    • “I’m not guessing.”
    • “I’m not panicking.” 

    And here’s the best part: When tax becomes calm, you stop running your business from stress. You start running it from strategy.


    When tax becomes calm, you stop running your business from stress.
You start running it from strategy.

    How The Edge Bootcamp Supports This (and why it’s perfect before EOFY planning)

    The Edge Bootcamp is designed for business owners who want more profit, better systems, cleaner numbers, and less overwhelm.

    You’ll walk away with:

    • a simple money system
    • clearer separation between business and personal finances
    • confidence understanding Xero and key reports
    • and a clear 90-day implementation plan so you know what to do first, next, and next

    Tickets include:

    • the 2-day live bootcamp
    • digital resources
    • templates
    • 90-day action plan tools

    And yes, recordings are provided after the event for ticket holders.

    If you’re thinking, “I’m behind and embarrassed,” this is a practical and judgement-free event – designed to help you build confidence step-by-step.

    You can attend:

    So whether you’re based in Perth, Fremantle, East Fremantle, regional WA, interstate, or juggling a packed schedule, you can still get the foundations in place.

    Want Tax Time to Be Boring (In the Best Way)?

    If you’re ready to stop the stress spiral and build a simple system that makes tax time calm, cash flow predictable, and owner pay consistent…

    ✅ Join The Edge Bootcamp (2-day live event)
    ✅ Attend in person at East Fremantle Yacht Club or live online
    ✅ Get templates + digital resources + your 90-day action plan tools included
    ✅ Receive recordings after the event so you can rewatch while you implement

    CTA: Book your spot for The Edge Bootcamp and walk away with the foundations to manage your business and finances with clarity, confidence, and a plan.

    Note: This is general education only, not personalised financial, tax, accounting, legal, health, or investment advice. Please seek advice from qualified professionals for your specific circumstances.

    Join The Membership at Financial Management 101

    #HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings 


    The Financial House Inspection: 10 Sneaky Money Leaks (And How to Plug Them Fast)

    The Financial House Inspection: 10 Sneaky Money Leaks (And How to Plug Them Fast)

    Let me ask you something… if your financial house was a real house, would you invite guests over right now?

    Or would you do that frantic pre-visit panic clean where you shove everything into the laundry or the spare room and pray nobody opens that door?

    Because that’s what most people are doing financially.
    Not because they’re “bad with money” (you’re not), but because life is busy, expensive, and full of sneaky little costs that quietly set up camp in your bank account like they pay rent.

    And the truth is… you don’t always need a bigger income to feel more in control.
    Sometimes you just need to find the leaks.

    Today, we’re doing a Financial House Inspection – warm cuppa in hand, no shame, no judgement, and definitely no stiff “financial coach voice.”  You’ll walk away with practical fixes, a clearer head, and probably a few “WAIT… WHAT?!” moments.

    Let’s inspect your money house.

    Why “Money Leaks” Matter (Even If You Earn Good Money)

    A money leak is not a big, dramatic purchase you remember forever (like buying a car or going on a holiday).

    A money leak is the “small stuff” you don’t notice… until you look at your bank statement and think:

    “Excuse me, where did my money go?”

    Leaks are dangerous because they:

    • feel harmless in the moment
    • happen repeatedly
    • add up faster than you think
    • make you feel like you’re always behind even when you’re trying

    And here’s the kicker: leaks are often emotionally driven, not logically driven. They’re convenience, comfort, habit, exhaustion, reward, stress, or just not having a system in place.

    So let’s find them and plug them like the financially strong legend you are.

    The Financial House Inspection Checklist: 10 Common Money Leaks

    1) The Subscription Graveyard

    This one is so common it deserves its own memorial plaque.

    Streaming services, apps, software, gym memberships, delivery memberships, random “productivity tools,” audiobooks, meditation apps, cloud storage…

    And you know what makes subscriptions sneaky?
    They don’t hurt enough to notice. It’s just $9.99 here… $14.99 there… $24.99 for something you “might use.”

    Until suddenly you’re donating $300 a month to the Subscription Graveyard.

    Quick Fix:

    • Go through your bank statements and highlight every recurring payment.
    • Ask: “Would I buy this again today?”
    • Cancel anything that isn’t a HELL YES.

    Pro tip:
    If cancelling makes you panic (“but what if I need it one day?”), that’s not logic, that’s fear. And fear is expensive.

    2) Lazy Renewals (Insurance, Utilities, Phone Plans)

    Lazy renewals are like leaving a tap dripping for years and being shocked your water bill is high.

    Insurance companies love loyal customers… because loyal customers often don’t check the price.

    Phone plans creep up. Internet deals expire. Electricity rates change. Suddenly you’re paying premium pricing for basic service.

    Quick Fix:

    1. Put a recurring reminder in your calendar every 6–12 months:
      • car/home insurance
      • health insurance
      • electricity/gas
      • phone/internet
    2. Compare and renegotiate.

    Money mindset note:
    Being financially responsible is not being “cheap.” It’s being strategic.

    3) Bank Fees and “Oops” Charges

    Account keeping fees. International transaction fees. ATM fees. Late payment fees. Overdraft fees.

    These aren’t “just the cost of banking.” They’re often the cost of not having the right account setup or system.

    Quick Fix:

    • Review your bank accounts and credit cards.
    • Ask your bank: “Is there a fee-free option?”
    • Set up alerts for low balances and bill due dates.
    • Automate minimum payments to avoid late fees.

    You don’t need to pay $10 – $30 a month in fees just to have a bank account. Your money deserves better.

    4) Convenience Spending (AKA “I’m Too Tired” Tax)

    This is the one people don’t want to admit because it’s so relatable.

    Convenience spending is:

    • takeaway because you’re exhausted
    • Uber because parking feels like emotional warfare
    • delivery apps because “I’ll just get one thing”
    • pre-made meals because you can’t face thinking

    And honestly? Sometimes it’s worth it. Life is busy. You’re human. But if it’s happening on autopilot, it becomes a leak.

    Quick Fix:

    • Create a weekly “convenience budget”  –  guilt-free, planned.
    • Have one or two “emergency meals” at home (freezer meals, eggs, wraps, anything easy).
    • Decide your rules before you’re tired.

    This isn’t about perfection. It’s about awareness + boundaries.

    Convenience Spending includes food delivery services.

    5) Supermarket Drift (The “Just One More Thing” Trap)

    You go in for milk and bread. You come out with:

    • fancy dips
    • a plant you didn’t need
    • snacks for “school lunches” (even though you don’t have kids)
    • and a candle because self-care.

    The supermarket is designed to separate you from your money with maximum efficiency.

    Quick Fix:

    • Shop with a list (yes, like a grown-up, annoying but effective).
    • Eat before you shop.
    • Do click-and-collect if you’re an impulse buyer.
    • Track your weekly grocery spend for 4 weeks and be honest about what’s happening.

    Groceries are one of the easiest leaks to tighten without feeling deprived.

    6) The Servo Snack & Coffee Leak

    The little daily habits: coffee, snacks, “just grabbing something,” the quick drink on the way home, the “treat” because the day was hard.

    And let me be clear: you’re allowed joy. But when joy is unplanned and daily, it becomes a leak.

    Quick Fix:

    • Choose what’s worth it.
    • If café coffee is your thing, keep it, but make it intentional.
    • Set a weekly allowance for treats and stick to it.

    The goal isn’t to become a finance robot. The goal is to stop accidentally overspending.

    7) Lifestyle Inflation (The “I Deserve It” Spiral)

    This one is sneaky because it feels like progress. You earn more… so you spend more. New car. Nicer clothes. More dinners out. Better holidays. Upgraded everything.

    And you might still feel broke. Lifestyle inflation isn’t about being irresponsible. It’s about missing the moment where you lock in your future before upgrading your present.

    Quick Fix:

    1. When income increases, decide in advance:
      • what percentage goes to lifestyle
      • what percentage goes to savings/investing
      • what percentage goes to debt reduction
    2. Automate “Future You” first.

    Future You is not asking for everything.
    Future You is asking for something.

    8) “Buy Now Pay Later” (BNPL) and Payment Splitting

    BNPL is basically like inviting little debts into your house and then being shocked they’re eating all your groceries.

    It doesn’t feel like debt because it’s broken up into payments.
    But it still reduces your future cash flow and adds mental load.

    Quick Fix:

    • List every BNPL account and total outstanding.
    • Pause new purchases until the balances are cleared.
    • Rebuild a sinking fund for things you commonly use BNPL for (clothes, gifts, school costs, etc.

    BNPL is not evil. But it is dangerous if it becomes your normal.

    9) Unused Memberships and “Aspirational Spending”

    This is spending money on the version of you who:

    • goes to the gym 5 days a week
    • does yoga at sunrise
    • reads 2 business books a week
    • meal preps like a wellness influencer
    • uses that online course “soon”

    We’re funding our aspirational selves while our current selves are just trying to get through Tuesday.

    Quick Fix:

    • Keep one “growth” commitment at a time.
    • If you’re not using it, pause it.
    • Choose what actually fits your life right now.

    The goal is to build financial muscle, not financial guilt.

    10) The “No System” Leak (The Biggest One)

    This is the mother of all leaks. Because even if you fix everything above, if you don’t have a system, the leaks come back.

    A system is what creates calm. It tells your money where to go before life grabs it first.

    Quick Fix:
    Start with these basics:

    • a separate bills account
    • automatic transfers on pay day
    • a weekly money check-in (10 minutes)
    • clear spending categories (not 47 categories… just the ones that matter)

    Most people don’t have a money problem. They have a money flow problem.

    And that is fixable.

    Your Mini Action Plan: Plug Leaks in 30 Minutes This Week

    If you want to feel immediate relief, do this:

    1. Print your last 30 days of transactions (or pull them up on your banking app).
    2. Highlight anything that surprised you.
    3. Circle:
      • subscriptions
      • takeaway/coffee
      • shopping
      • fees
    4. Choose 3 leaks to plug this week.
    5. Move the money you save into a separate “Future Me” account.

    That last step matters. If you don’t redirect the savings, it disappears into new spending. Money is like that. It loves momentum.

    Print your last 30 days of transactions (or pull them up on your banking app). Then, highlight anything that surprised you.

    The Real Truth: You Don’t Need More Willpower – You Need Support + Structure

    I want to say something kindly but clearly:

    If you’ve tried to “get on top of money” before and it didn’t stick, it’s not because you’re hopeless. It’s because you’ve been trying to do it alone, in between work, kids, stress, bills, and exhaustion… with zero structure and a lot of pressure.

    And that’s not a character flaw. That’s a strategy gap.

    Come Into the Membership (Because This Is What We Do Together)

    If reading this has you thinking, “Okay… I can see the leaks, but I need help making this a real system,” then babe – this is exactly why I created my Membership.

    Inside the Membership, we don’t just talk about money. We build financial muscle.

    ✅ We identify your personal leaks (not generic ones).
    ✅ We set up a simple money system that actually fits your life.
    ✅ We make progress without shame, overwhelm, or perfection.
    ✅ You get guidance, structure, education, and support – so you’re not constantly starting over.

    Because getting your financial house in order isn’t about a one-time clean-up.
    It’s about building habits and systems that keep it running smoothly long-term.

    If you’re ready to stop guessing and start feeling in control, join the Membership.
    Let’s plug the leaks, create a plan, and turn your financial house into a place you feel proud to live in.

    #HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney Discover 10 sneaky money leaks draining your bank account and simple fixes to plug them fast. Get your financial house in order without the guilt. financial house in order, stop overspending, budgeting without stress, cash flow tips reduce financial stress, personal finance Australia spending habits save money fast, subscriptions costing me money, how to manage money better


    How Can I Rebuild My Confidence After Making a Financial Mistake or Falling Behind on My Budget?

    How Can I Rebuild My Confidence After Making a Financial Mistake or Falling Behind on My Budget?

    We’ve all had that moment.

    You check your bank account… and it’s lower than you thought.
    You open your credit card bill… and it’s higher than you expected.
    You look at your budget… and realse you haven’t followed it for two weeks.

    Cue the shame spiral.

    If you’ve recently made a money mistake – or you just feel behind – I want you to know this:

    You are not alone.
    You are not a failure.
    And you are absolutely capable of bouncing back stronger.

    This blog will walk you through how to move from guilt to growth, and rebuild your confidence one step at a time.

    1. Separate Your Self-Worth from Your Net Worth

    First and foremost: you are not your bank balance.

    Your financial missteps don’t make you “bad with money.” They make you human.

    Whether you overspent, ignored your budget, or slipped back into old habits, it doesn’t define who you are. It’s a moment – not a life sentence.

    Start here:

    • Remind yourself: “I am capable of change.”
    • Reflect on a past financial win, no matter how small

    Say out loud: “I forgive myself. I’m ready to move forward.”

    2. Get Honest (Without the Shame)

    Let’s name what happened – not to beat yourself up, but to take your power back.

    Ask yourself:

    • What did I spend that I hadn’t planned for?
    • Did I avoid tracking or checking in with my money?
    • Did I say “yes” to things I couldn’t afford?

    Write it all down. You’re not here to judge yourself – just to gain clarity so you can move forward with purpose.

    3. Understand What Triggered the Slip-Up

    There’s always a “why” behind every money misstep mand understanding it is key to change.

    Common triggers:

    • Emotional spending (boredom, stress, celebration)
    • People-pleasing (saying yes to things out of guilt)
    • Lack of planning (unexpected expenses you didn’t prep for)
    • Old money stories (like “I’ll never get ahead anyway”)

    Identifying the trigger gives you a new layer of awareness and that’s when real change begins.

    4. Reset with a Micro-Goal

    When your confidence is shaken, the best thing you can do is create a tiny win that rebuilds momentum.

    Here are some examples:

    • Track your spending for the next 3 days
    • Create a mini budget just for this week
    • Make one extra payment toward your credit card
    • Pause one subscription and save the money instead

    Success is a series of small, intentional steps. Start with one.

    Create a mini budget for this week

    5. Watch Your Words (They Matter More Than You Think)

    Your internal dialogue becomes your financial reality.

    Let’s flip the script:

    ❌ “I’m terrible with money.”
    ✅ “I’m learning how to manage my money better every day.”
    ❌ “I’ll never get out of debt.”
    ✅ “Every payment I make moves me closer to freedom.”
    ❌ “I can’t stick to a budget.”
    ✅ “I’m figuring out a system that works for me.”

    Language matters. Speak like someone who’s growing because you are.

    6. Track Progress, Not Perfection

    You don’t have to get everything right to be making progress. Celebrate the fact that:

    • You noticed the slip-up
    • You chose to stop and reflect
    • You’re taking action now

    That’s what winning with money actually looks like.

    Make a habit of reflecting each month:

    • What went well?
    • Where did I struggle?

    • What can I adjust?

    And remember: even showing up for your finances when it’s hard is worth celebrating.

    7. Lean Into Support – Don’t Do This Alone

    Shame thrives in isolation. Confidence grows in community.

    Find a space where:

    • You can ask questions without feeling judged
    • You can share your wins and struggles
    • You can be held accountable to your goals

    That’s exactly what Financial Muscle Coaching is a coaching and accountability space, where we normalise setbacks and celebrate bounce-backs.

    Inside the membership, you’ll find structure, strategy, and support – all in one place.

    8. Build Your Financial Muscle, One Rep at a Time

    Rebuilding financial confidence is like building physical strength – it happens one rep at a time.

    One decision to check your balance.
    One habit of tracking your spending.
    One conversation where you ask for help instead of hiding.
    One payment that moves you forward.

    You don’t need to leap – you just need to lift. And every lift makes you stronger.

    Final Thoughts

    Mistakes are part of the journey – not the end of it.

    You are not behind. You are not bad with money. And you don’t have to do this perfectly to make progress.

    Every time you choose to come back – to review, reflect, and reset – you’re rebuilding your confidence.

    You’re showing yourself what you’re made of.
    And you’re writing a new money story that’s rooted in self-trust, resilience, and growth.

    You’ve got this. And I’m right here cheering you on.

    ? Join Financial Muscle Coaching

    If you’re tired of navigating your money alone – or beating yourself up every time you slip – Financial Muscle Coaching is the place for you.

    In this weekly coaching space, you’ll get:
    ✅ Encouragement instead of criticism
    ✅ Clear, doable action plans that meet you where you are
    ✅ Real accountability to build habits and confidence that last

    No more shame. No more silence. Just strength, strategy, and steady growth.

    Join Financial Muscle Coaching Now

    #HowToChangeMoneyMindset #ResetMyMoneyBeliefs #BuildFinancialConfidence #MoneyMindsetHelp #FinancialMindsetCoaching #HowToFeelBetterAboutMoney #WhyDoIFeelStressedAboutMoney #NewYearMoneyMindset #MoneyMindsetReset2025 #PositiveMoneyBeliefs #MoneyMindset #FinancialFreedomJourney #MoneyCoach #BudgetMindset #AbundanceMindset