Are You Ignoring Your Financial Safety Net? Why Wills & Estate Planning Matter (Even If You’re Young!)

Are You Ignoring Your Financial Safety Net? Why Wills & Estate Planning Matter (Even If You’re Young!)

Alright, friend… it’s time we talk about something that everyone needs, but almost no one wants to deal with.

Wills. Estate Planning. Life insurance.

Did your eyes just glaze over?

Did you suddenly feel an overwhelming urge to click away or scroll to the fun stuff on Instagram?
Stay with me, because this may just be one of the most important money conversations you’ll ever have. Here’s the hard truth:

If you’re ignoring estate planning because you think it’s “only for rich people” or “something I can figure out later,” you’re playing a dangerous game with your financial future, and the people you love most.
In this post, I’m going to:

  • Bust the biggest myths about wills and estate planning.
  • Show you why everyone (yes, even you!) needs a plan.
  • Break down exactly what you need to do – without confusing legal jargon.
  • Help you take simple, meaningful action to protect your future.

And don’t worry, this isn’t going to be dry or boring.

We’re going to make this approachable, empowering, and (dare I say?) a little fun. Because protecting your future should feel like an act of love and self-respect, not something you dread.

? Myth #1: “Estate Planning Is Only for Rich People”

Let’s start here, because this myth is everywhere. When most people hear the phrase “estate planning,” they picture wealthy people with sprawling mansions, yachts, and family fortunes that need protecting. But here’s the truth: If you own anything – even a car, a bank account, or a pet – you have an estate.

Estate planning isn’t just for millionaires. It’s for:

  • The young professional with a growing savings account.
  • The parent who wants to protect their kids.
  • The small business owner with assets tied to their company.
  • The renter with a car loan and a retirement fund.

If you have money, possessions, dependents, or even digital assets – estate planning applies to you.

If you own anything - even a car, a bank account, or a pet - you have an estate.

? Why Avoiding Estate Planning Could Cost You (Big Time)

I get it – thinking about wills, death, and “what ifs” isn’t exactly a fun Friday night activity. But here’s the thing… Avoiding estate planning doesn’t make it go away. It just creates more chaos for the people you care about most. Without a will or estate plan in place:

  • The courts decide who gets your assets – and it may not align with your wishes.
  • Your loved ones could be tied up in legal battles for months (or even years).
  • Minor children could end up with a guardian chosen by the court – not you.
  • Your hard-earned money could get eaten up by legal fees, taxes, or other costs.

In short, not planning can create stress, delays, and heartache at the worst possible time.

But when you take just a little time to set up your financial safety net? You give your loved ones clarity, protection, and peace of mind.

? “But I’m Too Young for a Will!”

Another common myth? Thinking you’re too young to need a will. Here’s a little truth bomb:

Wills aren’t about age – they’re about responsibility.

You may not think you need one yet, but ask yourself:

  • Do you have savings, retirement accounts, or life insurance?
  • Do you have pets who rely on you?
  • Do you own a car, home, or business?
  • Do you have people who depend on your income?
  • Do you have strong opinions about where your money should go if something happens to you?

If you answered yes to any of those, it’s time to start planning. Remember—estate planning isn’t about expecting the worst. It’s about being prepared for whatever life throws your way.

✨ Estate Planning: It’s Not Just About Death – It’s About Life, Too!

One of the most overlooked parts of estate planning? It’s not just about what happens after you’re gone. It also protects you while you’re alive, especially if you ever:

  • Become seriously ill.
  • Get injured and can’t manage your finances or healthcare decisions.

Your estate plan can include documents like:

  • Power of Attorney: Designating someone you trust to manage your finances if you can’t.
  • Healthcare Directive: Outlining your wishes for medical treatment and end-of-life care.
  • Guardianship Designations: Naming who will care for your minor children if you’re unable to.

These documents ensure your voice is heard – no matter what.

? What’s Actually Included in a Basic Estate Plan?

Let’s strip away the legal jargon and break this down simply. Here’s what most people need in their estate plan:

1. A Will

This legal document spells out:

  • Who will inherit your assets (money, property, belongings, etc.).
  • Who will take care of your children or dependents (if applicable).
  • Who will manage your estate (called an executor)

What To Include in A Basic Estate Plan

2. Power of Attorney (POA)

This gives someone legal authority to:

  • Handle your finances if you’re incapacitated.
  • Make decisions on your behalf if you can’t.

3. Healthcare Directive (Living Will)

This outlines your medical wishes if you’re unable to communicate them.

4. Beneficiary Designations

Certain accounts (like life insurance, retirement accounts, and some bank accounts) allow you to name a beneficiary directly. These override your will, so it’s crucial to keep them updated.

5. Guardianship Designations (If Applicable)

If you have minor children, this document names who you want to raise them if you’re unable to.

Bonus: Trusts (Optional for Some)

While not necessary for everyone, trusts can:

  • Help avoid probate (the legal process of validating a will).
  • Provide additional control over how and when assets are distributed.
  • Offer potential tax benefits.

? How to Get Started with Estate Planning (Without Feeling Overwhelmed)

Deep breath – this doesn’t have to be complicated! Here’s how to start, step by step:

Step 1: Take Inventory

List all your:

  • Bank accounts
  • Retirement accounts
  • Investments
  • Properties
  • Vehicles
  • Insurance policies
  • Personal belongings of high value
  • Digital assets (crypto, social media, etc.)

Step 2: Clarify Your Wishes

Think about:

  • Who should inherit your assets?
  • Who do you trust to handle your finances and healthcare if needed?
  • Who would you want to care for your kids or pets?
  • Are there any charitable causes you’d like to support?

Step 3: Get Legal Help (If Needed)

While you can create simple wills online for a low cost, it’s often wise to consult an estate attorney, especially if:

  • You have significant assets.
  • You own a business.
  • You have a blended family or complex situation.

Step 4: Communicate Your Plan

This is the step most people skip, but it’s essential! Let your loved ones know:

  • That you’ve created an estate plan.
  • Where they can find the documents.
  • Who has been designated for certain roles.

Transparency now avoids confusion later.

Step 5: Review & Update Regularly

Life changes – your estate plan should too. Revisit your documents anytime you:

  • Get married or divorced.
  • Have children.
  • Move to a new state (laws vary).
  • Experience major financial changes.

? But What If You Don’t Have Much to Leave Behind?

Here’s a powerful truth: Estate planning isn’t just about leaving behind money – it’s about leaving behind clarity. Even if your financial picture feels “small” right now, your loved ones will still need to:

  • Handle your debts and bills.
  • Access your accounts.
  • Close out your digital presence.
  • Make healthcare decisions if needed.

Having a clear plan ensures they can do so smoothly. Plus, it sends a strong message: “I respect myself and the people I care about enough to plan ahead.”

? Estate Planning = Empowerment, Not Fear

I get it – this can all feel heavy. But here’s how I want you to reframe it:

Estate planning isn’t about preparing for doom and gloom.

It’s about:

  • Taking ownership of your life.
  • Protecting your family.
  • Making your wishes known.
  • Creating peace of mind, for you and for those you love.

It’s one of the most profound acts of love and responsibility you can make.

? How This Connects to Your Financial Breakthrough

In my Your Financial Freedom Breakthrough™ – 90 Day Money Makeover program, we don’t just focus on day-to-day money tasks like budgeting and debt. We go deeper, because true financial empowerment covers everything. That includes:

  • Building your savings.
  • Tackling your debt.
  • Creating an intentional spending plan.
  • AND making sure your financial house is in order with estate planning.

Most programs skip this step, but I refuse to. Why? Because I’ve seen firsthand how having a financial safety net changes lives.

In the program, you’ll:

  • Learn exactly what legal documents you need.
  • Get simple checklists to help you start (even if you’re a total beginner).
  • Be guided through tough but important questions with compassion and clarity.

It’s all about making this process approachable, doable, and even empowering.

? Ready to Take Action? (Mini Challenge!)

Let’s get you started today with a bite-sized action step.

Estate Planning Mini Challenge:

Make a list of ALL your current accounts and assets. Check the beneficiaries on your bank accounts and retirement funds. Update them if needed.

Choose ONE document to tackle this month:

  • Will
  • Power of Attorney
  • Healthcare Directive

Start with the easiest one for you. This tiny step will start creating massive peace of mind, and it’s easier than you think.

? Final Thoughts: Your Legacy Starts Now

Here’s what I want you to remember: Estate planning isn’t just for “older” or “wealthy” people – it’s for everyone who wants to protect their future.

You don’t need to do it all at once, but starting somewhere is powerful. This isn’t about fear – it’s about empowerment, peace of mind, and love.

And if you’re ready to take this even further to finally build a money plan that covers everything from budgeting to wills and beyond, get ready. My Your Financial Freedom Breakthrough™ – 90 Day Money Makeover opens on September 10th, and it’s designed to help you:

  • Create lasting financial change.
  • Build a money system that works for your life.
  • Feel empowered, organised, and confident with your finances – once and for all.

You’ve got this, and I’m cheering you on every step of the way.

Your Financial Freedom Breakthrough™
Your Financial Freedom Breakthrough™ - Scope
Budgeting Without Deprivation: Why Your Budget Isn’t Working (Yet!)

Budgeting Without Deprivation: Why Your Budget Isn’t Working (Yet!)

Raise your hand if you’ve ever tried to stick to a budget…

…only to find yourself breaking it faster than you can say “unexpected Amazon purchase.”

Yep, I see you. And you’re not alone.

Budgets have gotten a bad rap over the years.

For many people, the word “budget” feels about as appealing as:

  • Giving up your daily coffee runs.
  • Saying “no” to dinners out with friends.
  • Counting every single penny and feeling like you’re constantly falling short.

But here’s the truth nobody talks about:

Your budget isn’t failing because you’re bad with money.

It’s likely failing because it wasn’t built to work for you in the first place. Today, I’m going to show you:

  • Why most budgets backfire (and it has nothing to do with willpower).
  • How to reframe budgeting as a freedom tool – not a punishment.
  • My favorite tips to create a budget that actually sticks (without feeling deprived!).

By the end of this post, you’ll feel empowered to take control of your money in a way that feels personal, realistic, and – dare I say it – fun. Ready? Let’s dive in.

? The Real Reason Most Budgets Fail

Here’s the million-dollar question:

Why do so many budgets start with excitement… but crash and burn within weeks?

Simple:

Most people create budgets from a place of restriction, not intention.

Think about it.

When people sit down to “get serious” about money, they often whip out a budgeting app or spreadsheet and immediately start slashing everything they love:

  • No more takeout.
  • No more fun shopping.
  • No more travel.

It’s like putting your money on a crash diet. And just like a crash diet, it’s unsustainable. You might stick with it for a week or two. Maybe even a month. But eventually, you’ll start to feel suffocated. Deprived. Frustrated.

And then? You rebel.

Suddenly, you’re splurging on things you “shouldn’t” buy, feeling guilty, and thinking, “I just suck at budgeting.”

Sound familiar?

? Why Budgeting Doesn’t Have to Feel Like Deprivation

Here’s the mindset shift that changes everything: Your budget isn’t a punishment. It’s a permission slip.

Let me say that again, louder for the people in the back: Your budget is a tool that gives you permission to spend on what truly matters to you.

Budgeting isn’t about cutting everything out of your life. It’s about:

  • Getting clear on your values.
  • Prioritising what brings you joy and security.
  • Being intentional with every dollar.

It’s the ultimate act of self-respect and self-care. Because when you create a budget that aligns with your goals, you’re telling yourself: “I trust myself with money. I’m creating a life that feels good today and tomorrow.”

    Your budget isn’t a punishment. It’s a permission slip.

    Your budget isn’t a punishment. It’s a permission slip. Your budget is a tool that gives you permission to spend on what truly matters to you.

    ✨ The 3 Most Common Budget Mistakes (And How to Fix Them!)

    Let’s get specific. Here are the biggest budgeting mistakes I see over and over and how you can fix them starting today.

    Mistake #1: You’re Budgeting for a Fantasy, Not Your Real Life

    So many people create their budget based on what they wish their life looked like, not how they actually live. You might be thinking:

    • “I’ll just cut my grocery spending in half.”
    • “I’ll stop eating out completely.”
    • “No more personal spending for the next three months!”

    But here’s the problem:

    • You still have to eat.
    • You still want to enjoy your life.
    • You’re not going to suddenly become a minimalist monk overnight.

    Solution: Budget for your real life, not your fantasy version.

    Ask yourself:

    • What are my non-negotiables? (Coffee, takeout, hobbies, etc.)
    • Where am I willing to cut back (for now)?
    • How can I adjust slowly instead of all at once?

    Mistake #2: You’re Not Building in Flexibility

    Life happens. Unexpected expenses come up. Surprise celebrations pop onto the calendar. Your car decides to remind you it needs repairs (usually at the worst possible time).

    Most budgets fail because they’re too rigid. Every dollar is assigned perfectly… until reality hits.

    Solution: Build in buffer zones.

    In your budget, always include:

    • A miscellaneous category for unexpected expenses.
    • A “fun money” allowance—even if it’s small—to spend guilt-free.
    • A savings cushion for bigger unexpected costs over time.

    This way, your budget can bend without breaking.

    Tie every budgeting choice to a goal that lights you up.

    ? How to Create a Budget You’ll Actually Stick To (Without Feeling Deprived)

    Let’s get into the practical part! Here’s my step-by-step process for creating a feel-good, flexible, empowering budget that works for real people with real lives.

    Step 1: Know Your Numbers (Without Shame!)

    You can’t improve what you don’t measure. Start by gathering:

    • Your monthly income (after taxes).
    • Fixed expenses (rent, utilities, insurance, subscriptions).
    • Variable expenses (groceries, gas, dining out, etc.).
    • Minimum debt payments.

    Remember, this isn’t about judging yourself. It’s about getting honest with where you’re at.

    Step 2: Identify Your Financial Priorities

    Ask yourself:

    • What matters most to me right now?
    • Which goals am I working toward over the next 3–6 months?

    Examples:

    • Paying off credit card debt.
    • Saving for a vacation.
    • Building an emergency fund.

    Rank them in order of importance.

    Step 3: Allocate Your Income (The Empowered Way!)

    Now it’s time to assign your dollars. Start with this simple formula:

    • Fixed Expenses – Cover your essentials first.
    • Savings & Debt Goals – Direct money toward your top priorities.
    • Variable Expenses – Budget realistically for your daily life.
    • Fun Money & Flex Funds – Yes, this is non-negotiable!

    Every dollar should have a job, but make sure some of those jobs bring you joy!

    Step 4: Automate Where You Can

    Take the mental work out of budgeting by automating:

    • Bill payments
    • Minimum debt payments
    • Savings contributions (even small ones!)

    Automation reduces decision fatigue and makes it easier to stay on track.

    Step 5: Check In Weekly (Not Just Monthly!)

    Most people only check their budget once a month… or never. That’s like driving with your eyes closed until you crash. Instead, commit to a weekly money date with yourself.

    Ask:

    • What went well this week?
    • Where did I overspend or underspend?
    • Do I need to adjust anything for the week ahead?

    This keeps you engaged and in control, without feeling overwhelmed.

    ? Yes, You Can Still Have Lattes and Takeout (Here’s How!)

    Let’s address the elephant in the room. Do you have to give up your favorite things to succeed financially? Absolutely not.

    Here’s the trick:

    • Budget for them intentionally.
    • Scale back elsewhere if needed.
    • Enjoy them guilt-free.

    Maybe that means fewer takeout nights… but keeping your Friday sushi ritual. Maybe it means making coffee at home most days… but savoring your weekend café visits.

    It’s about balance, not restriction.

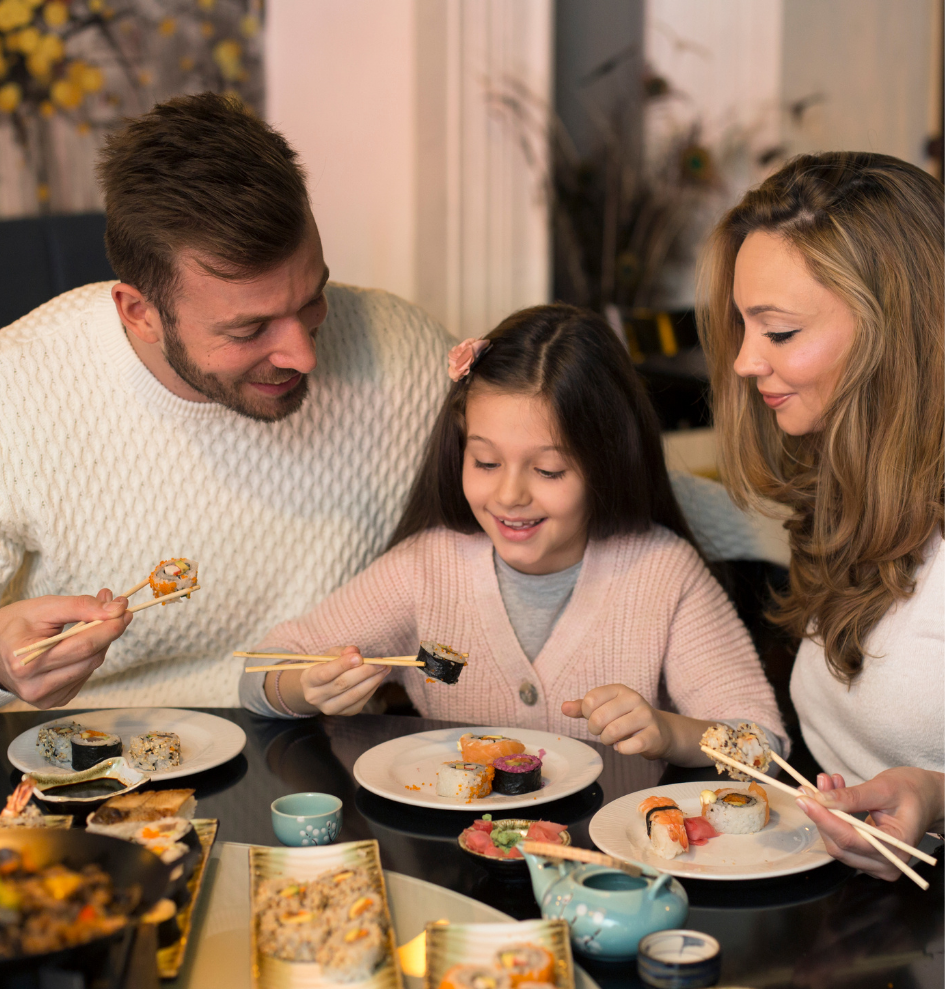
    You can still keep your Friday sushi ritual with the fam!

    If you budget intentionally, you can still keep your Friday sushi ritual with the fam without the guilt!

    It’s about balance, not restriction.

    ? How This Ties Into the Your Financial Freedom Breakthrough™ – 90 Day Money Makeover

    This is exactly why I spend a full section of my Your Financial Freedom Breakthrough™ – 90 Day Money Makeover guiding people through budgeting in a whole new way. We don’t just talk numbers – we talk values:

    • What makes you feel secure?
    • What experiences light you up?
    • How can your money fuel the life you want, both today and in the future?

    You’ll learn how to:

    • Build a flexible budget that supports your goals.
    • Ditch the guilt around spending.
    • Create a money plan that feels empowering—not restrictive.

    And the best part? You’ll have support, accountability, and expert guidance every step of the way.
    ? Ready to Take the First Step? (Mini Challenge!)

    Here’s a quick exercise to get you started today:

    The Budget Clarity Challenge:

    • Write down your top 3 financial goals for the next 90 days.
    • Review your last month of spending (no judgment!).
    • Highlight every purchase that didn’t align with your goals.

    Ask yourself:

    What can I adjust next month to better support my goals, without cutting out everything I enjoy?

    Choose one small change you’ll make this week. This simple process can open your eyes to how you’re currently spending, and show you just how much power you have to shift it.

    ? Final Thoughts: Budgeting Is About Freedom, Not Frustration

    Here’s what I want you to remember:

    Budgeting isn’t about deprivation – it’s about designing a life you love. Your money can support your dreams, your joy, and your future security – all at the same time.

    You don’t need to be “perfect” with your budget. You just need to stay consistent and flexible.

    And if you’re ready to dive deeper into this work, to finally build a money system that sticks – keep your eyes open. My Your Financial Freedom Breakthrough™ – 90 Day Money Makeover program opens for enrollment on September 10th.

    Together, we’ll build a budget that works with your life, not against it, and set you up for financial freedom that lasts.

    Your Financial Freedom Breakthrough™ - 90 Day Money Makeover
    Cash Flow is King: Why Every Small Business Owner  Needs a Financial Plan (Not Just More Work)

    Cash Flow is King: Why Every Small Business Owner  Needs a Financial Plan (Not Just More Work)

    If you’re a tradie, Franchisee or small business owner, chances are you’ve said this before:

    “I just need more work.”
    “If I can land that next big job, I’ll be sweet.”
    “Once I get through this month, I’ll finally get on top of things.”

    Sound familiar?

    We’ve been sold this idea that working more hours or taking on more jobs is the key to financial stability.

    But here’s the truth…

    More work won’t fix your money problems if your financial plan is broken.

    Let me say that again: More work won’t fix broken cash flow.

    In fact, working harder without a system can actually worsen your money stress – leading to burnout, resentment, and a business that runs you, instead of the other way around.

    In this blog, I’ll break down why cash flow is king, how small business owners end up in the trap of “more jobs = more chaos”, and what you can do to take control of your money (without working yourself into the ground).

    The Myth of “More Work = More Money”

    Let’s say you take on 3 new clients this month as a tradie. Awesome, right?
    But then:

    • You buy more materials
    • You spend more hours on-site
    • You hire a subbie to help out
    • You juggle more admin
    • You forget to invoice someone
    • And suddenly – you’re busier than ever… but your bank account doesn’t show it

    That’s because revenue doesn’t equal profit, and being busy doesn’t equal being financially fit.
    You can be flat-out all month and still feel broke.

    That’s the trap, and I see it every week with tradies, franchisees and business owners who are absolutely brilliant at what they do… but never learned how to manage the money side of things.

    So What’s the Real Problem?

    It comes down to one powerful truth:

    Cash flow – not just income – is what makes or breaks your business.

    Cash flow is the movement of money in and out of your business.

    Not just how much you make, but:

    • When you get paid
    • How consistently money comes in
    • What goes out each week
    • Whether you’re left with a profit (or just scraping by)

    If you don’t have control over your cash flow, you’re always reacting. You’re playing catch-up. And that stress leaks into everything – your health, your relationships, and even the quality of your work.

    Here’s What Cash Flow Chaos Looks Like

    If you’ve ever experienced any of these, you’re in a cash flow crunch:

    • You avoid checking your account because you’re afraid of what you’ll see
    • You wait until BAS is due to realise you owe thousands
    • You struggle to pay your own wage regularly
    • You’re always chasing late invoices
    • You can’t take time off because you’re constantly hustling to “keep up”
    • You’ve had to dip into your personal savings more than once

    Sound familiar? You’re not alone. But the good news is – it’s fixable.

    The Solution: A Simple, Small Business – Friendly Financial Plan

    You don’t need a finance degree or a fancy accountant to get this sorted. You just need a clear plan for how money flows through your business. Here’s how to start building one.

    1. KNOW YOUR BREAK-EVEN POINT

    This is the minimum amount of money you need to earn each month to cover:

    • Business expenses (tools, fuel, phone, materials, subs, etc.)
    • Your personal wage
    • Tax and super
    • Any loan or debt repayments

    Without knowing your break-even, you’re guessing. You’re flying blind. Once you’ve nailed this number, everything becomes clearer.

    Now, you can set targets based on facts – not hope.

    2. PAY YOURSELF A WAGE – YES, YOU!

    This is the game changer. Every time income hits your account, it should be split into different buckets. That way, you’re not tempted to spend what should’ve gone to tax, bills, or your own pay.

    Here’s a simple version that works great for small business owners:

    ✅ Income Account
    Where all your payments land. This is your holding zone.

    ✅ Owner’s Pay Account
    Your regular wage. Non-negotiable. You work hard, you deserve to be paid consistently.

    ✅ Expenses Account
    Materials, suppliers, fuel, subscriptions, etc.

    ✅ Tax & BAS Account
    Put aside 25 – 30% of every payment for Tax plus the GST portion. No more panic come BAS time.

    ✅ Profit Account
    Even just 5% of each job. This is for rainy days, growth, or peace of mind.

    You can set this up in 30 minutes through online banking. Once you do? You’ll sleep better knowing your money is finally working for you.

    3. TRACK YOUR MONEY CASH FLOW

    Once a week, check in on your numbers. This doesn’t need to be a 2-hour admin marathon. I’m talking 20–30 minutes to:

    • See what came in
    • Check what went out
    • Update your numbers
    • Chase unpaid invoices
    • Move money into your buckets

    Make this a weekly ritual (I call it a Money Date) and watch your confidence skyrocket. Because the more you look at your money, the less power it holds over you.

    4. TRACK YOUR MONEY CASH FLOW

    You can have all the work in the world, but if your prices don’t reflect the true cost of running your business – you’ll never get ahead.

    Too many small business owners undercharge because they’re afraid of losing the work.

    But if you’re not charging for:

    • Admin time
    • Quote prep
    • Travel
    • Time off tools
    • Overheads
    • Profit margin

    …then you’re not building a business. You’re building a time bomb.

    You should be pricing with confidence, knowing that it covers everything – not hoping for the best.
    Inside The Edge, I teach you a simple pricing calculator so you know exactly what to charge and why.

    5. BUILD A BUFFER FUND

    We all know some work can be seasonal or unpredictable.

    A job gets delayed. A client pays late. You get sick. And suddenly your cash flow takes a hit. That’s why a buffer fund is crucial.

    Aim to build up 1–3 months’ worth of business expenses in a separate account. This gives you breathing space and avoids making panic-driven decisions like slashing prices or taking on crappy jobs just for quick cash.

    Start small – $50 a week adds up. Automate it. Make it part of your money system. 

    Build a Buffer Fund

    The Truth? You Don’t Need More Work. You Need a Better Money Plan.

    You don’t need to hustle harder. You don’t need to take every job that comes your way. You need to manage your money better so the work you’re already doing actually pays off. Imagine this:

    • Getting paid consistently – even in quiet months
    • No more panicked BAS seasons
    • Knowing exactly what your business needs to earn each week
    • Saying YES to time off without financial stress
    • Watching your bank account grow, not shrink

    That’s what happens when cash flow becomes your king, and your systems support you, not sabotage you.

    And That’s Exactly What We Do Inside THE EDGE

    THE EDGE is a 6-week coaching program for tradies, franchisees and small business owners who are ready to stop guessing and start owning their business money. We’ll help you:

    ✅ Set up a cash flow system
    ✅ Price for profit
    ✅ Get your BAS and tax sorted
    ✅ Pay yourself consistently
    ✅ Build a buffer
    ✅ Plan for growth (without working more hours)

    It’s simple, structured, and built for people who are great at their trade, not spreadsheets.

    Final Thoughts: Work Smarter. Get Paid Properly. Stress Less.

    You didn’t go into business to work 24/7 and still worry about money.

    You started your business for freedom, flexibility, and a better life. And the path to that life isn’t more work. It’s better cash flow.

    So if you’re ready to take the pressure off and finally feel in control of your business money…

    Join THE EDGE: 6-Week Coaching Program

    Your business doesn’t need to change, it just needs a plan. Let’s build it together.

    THE EDGE - 6-WEEK PROGRAM