How Do I Build A Business That Runs Without Me?

How Do I Build A Business That Runs Without Me?

If the business relies on you for everything, you don’t own a business – you own a job!

Here’s how clearer systems and financial visibility create a business that can operate without you.

We hear a version of this from almost every business owner: “I can’t even take a week off without everything falling apart.” Or worse, “I did take a week off, and I’m still cleaning up the mess.”

If that’s familiar, please hear this: it’s not because you haven’t worked hard enough. It’s usually the opposite. You’ve worked so hard, for so long, that the business has quietly built itself around you being everywhere, all the time.

By the end of this, you’ll know the real reason most businesses stay dependent on their owner, and the two things; systems and financial visibility that actually change it.

1. In the beginning, you being everywhere was the right call

When a business starts, the owner touching everything isn’t a flaw. It’s often the only way to survive the early years; you’re the salesperson, the delivery, the bookkeeper and the decision-maker because there’s nobody else.

The problem isn’t that this happened. It’s that it kept happening long after the business could have supported something different.

The shift to make: recognise that what got the business started isn’t what will let it grow past you. Those are two different jobs.

2. Without documented systems, you’re the system

If a process only exists in your head, you are the process. Every new hire has to learn it directly from you, every exception gets escalated to you, and every “how do I…” question lands on your desk.

Systems don’t need to be complicated to work. They need to be written down, consistent, and followable by someone who isn’t you.

Check this: pick one task you do weekly. Could someone else follow written steps to do it the same way, without asking you a single question?
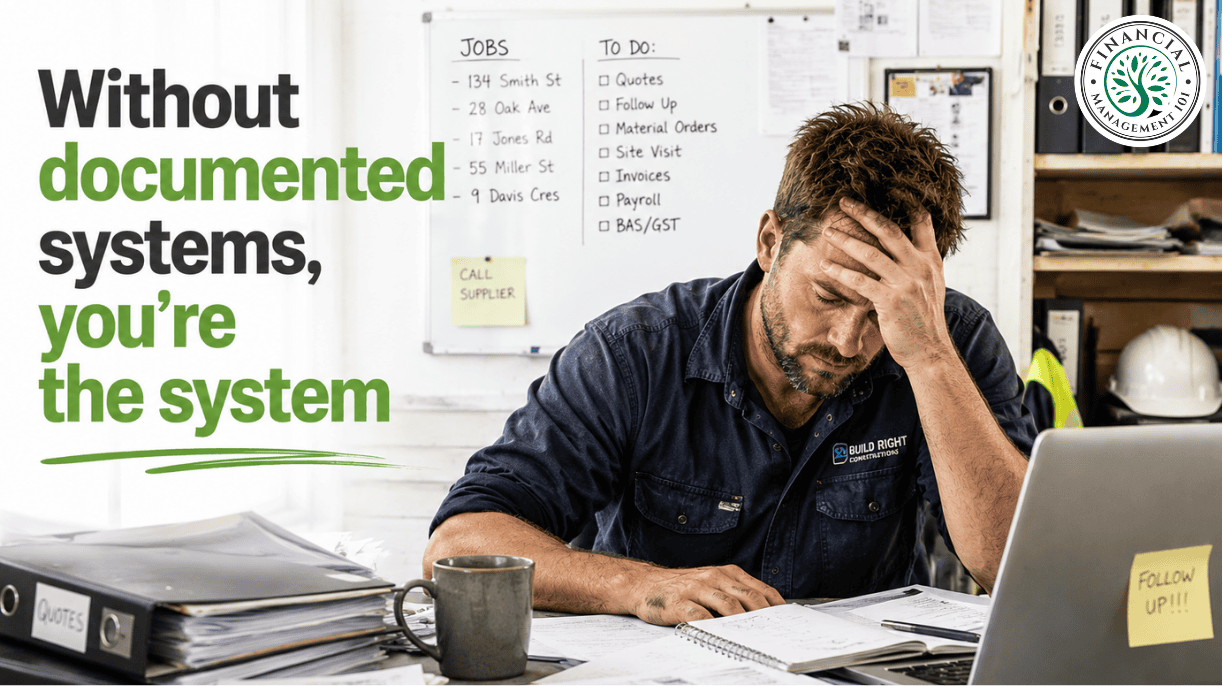
Without documented systems, you're the system

3. Delegating tasks isn’t the same as delegating decisions

Many owners delegate the doing but keep every decision for themselves. The team executes, but nothing moves without a final check from you, which means you’re still the bottleneck, just a busier one.

Real delegation means someone else has both the task and the authority to make the calls that go with it, within limits you’ve set.

Check this: notice how often your team’s questions could have been answered by them, if they’d had the context and the authority to decide.

4. If only you understand the numbers, the business still needs you

This is the piece most owners miss. Even with a great team and solid systems, if you’re the only one who can read the financial position of the business, every meaningful decision still funnels back through you.

Financial visibility – clear, regular, easy-to-read numbers – lets the right people make good decisions without needing you in the room. That might mean a manager, a bookkeeper, or simply you, on a rhythm that doesn’t require putting out fires to find the answer.

Check this: if you were unreachable for two weeks, could someone in your business still tell whether it was having a good month or a bad one?

5. Test it before you need it

The real test of a business that runs without you isn’t a plan, it’s a genuine trial. A few days away, phone down, seeing what actually breaks.

What breaks tells you exactly where the next system, the next handover of authority, or the next piece of financial visibility needs to go.

The Takeaway

A business that runs without you isn’t built by working harder or trusting your team more and hoping for the best. It’s built deliberately by documented systems, real decision-making authority for the people around you, and financial visibility that doesn’t depend on you being the only one who understands it.

Owning a business, not a job, comes down to whether it can function while you’re not in it. That’s not a one-off project. It’s a different way of building.

If you want a clear, structured path to building this kind of business, that’s exactly what The Edge is designed for.

My recommendation starts with doing a Business Health Check.

The EDGE Business Health Check in less than 20 minutes will help you uncover the blind spots, bottlenecks and hidden opportunities affecting your business.
The Edge Business Health Check

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess
#EntrepreneurMindset
 

What Numbers Should A Small Business Owner Track?

What Numbers Should A Small Business Owner Track?

You don’t need a full accounting degree to run a profitable business. But you do need to know which numbers reveal the real story. These are the few that matter most.

We get it, most business owners didn’t start their business because they love spreadsheets. You started it because you’re good at what you do, and somewhere along the way, “run the numbers” got added to the job description without anyone asking if you wanted it.

The good news is you don’t need dozens of reports or a finance degree. You need a small handful of numbers, checked regularly, that tell you the truth about how the business is really going.

By the end of this, you’ll know exactly which numbers to look at first, and why each one matters more than revenue alone.

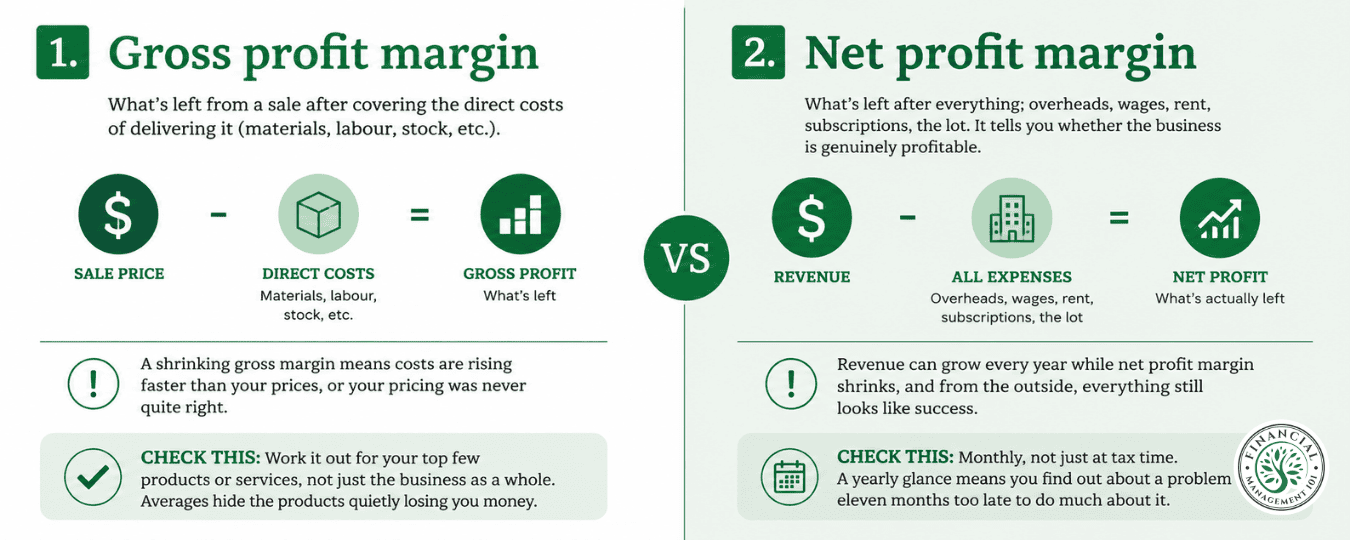
1. Gross profit margin

This is what’s left from a sale once the direct cost of delivering it is covered; materials, trade labour, stock, whatever it takes to physically deliver your product or service.

It’s the clearest early warning system in your business. A shrinking gross margin means either your costs are rising faster than your prices, or your pricing was never quite right to begin with.

Check this: work it out for your top few products or services, not just the business as a whole. Averages hide the products quietly losing you money.

2. Net profit margin

This is what’s actually left after everything; overheads, wages, rent, subscriptions, the lot. It’s the number that tells you whether the business is genuinely profitable, not just busy.

Revenue can grow every year while net profit margin shrinks, and from the outside, everything still looks like success.

Check this: monthly, not just at tax time. A yearly glance means you find out about a problem eleven months too late to do much about it.

Gross Profit Margin vs Net Profit Margin

3. Cash position versus profit

Your bank balance and your profit are two different stories, even though they feel like they should match. A healthy bank balance can be sitting on unpaid tax, a big supplier bill due next week, or a loan repayment about to land.

We business owners tend to use the bank balance as our main scoreboard, simply because it’s the number we see most often. It’s useful – it’s just not the whole picture.

Check this: look at your profit and loss statement alongside your bank balance, not instead of it.

4. Overheads as a percentage of revenue

Overheads rarely blow out all at once. They creep in like; a new subscription here, a rent increase there, a “temporary” extra cost that becomes permanent.

Tracking overheads as a percentage of revenue, rather than a raw dollar figure, shows you whether your costs are growing in proportion to the business or quietly outpacing it.

Check this: list every recurring cost and total it as a percentage of that month’s revenue. Watch the trend over a few months, not just one snapshot.

5. Debtor days – how long it takes to get paid

This is the one most owners forget to track, and it’s often the one causing the most stress. Debtor days measure the average time between sending an invoice and the money landing in your account.

The longer that gap, the more your own cash is quietly funding someone else’s business while yours waits.

Check this: if your debtor days are creeping up, it’s usually a sign your payment terms, follow-up process, or invoicing timing need a look, not that you need more sales.

The Takeaway

You don’t need to track everything. You need to track the right few things, consistently. Gross profit margin, net profit margin, cash position, overheads as a percentage of revenue, and debtor days together, these five numbers tell you far more about the health of your business than revenue ever will on its own.

Clarity here isn’t about becoming an accountant. It’s about finally being able to see your business as clearly as you run it.

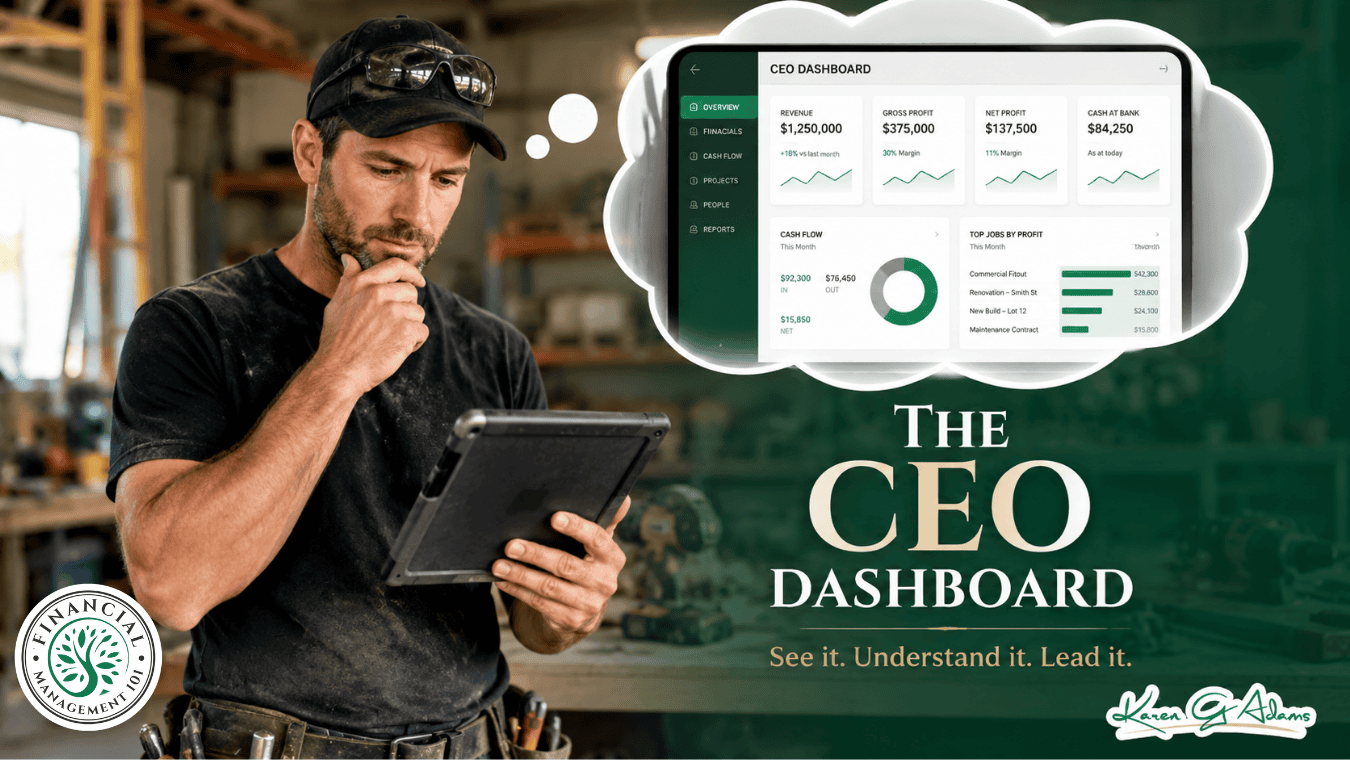
If you’d like these numbers tracked and visible for you automatically, that’s exactly what the CEO Dashboard is built for.

Watch the 2 minute video on how it works HERE

The CEO Dashboard™ gives small business owners a clear, visual snapshot of what’s really happening inside their business – so you can stop operating on gut feel alone and start making confident, data-driven decisions.

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess #EAP #EmployeeAssistanceProgram
#EntrepreneurMindset


Is Money Stress the Missing Piece in Your Wellbeing Strategy?

Is Money Stress the Missing Piece in Your Wellbeing Strategy?

You provide mental health support, but money is often part of the stress employees are carrying. Here’s how practical financial wellbeing education complements your EAP, without straying into personal advice.

We know how much thought goes into a wellbeing strategy. The EAP is in place. The mental health training has been rolled out. Leaders have been coached to check in on their people.

And still, something doesn’t quite add up. Engagement scores plateau. Absenteeism doesn’t shift the way you’d expect. People say they’re “fine” and clearly aren’t.

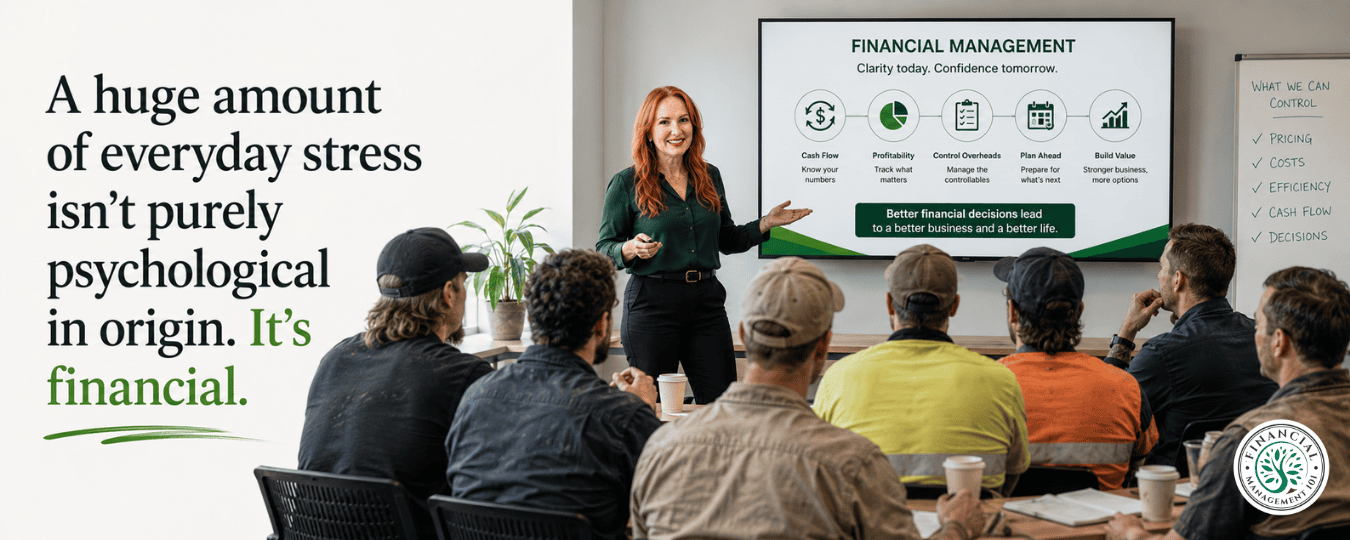
Here’s what often gets missed: a huge amount of everyday stress isn’t purely psychological in origin. It’s financial. And most wellbeing strategies aren’t built to touch it.

By the end of this, you’ll know why financial stress behaves differently to other workplace stressors, and how practical financial education sits alongside your EAP rather than competing with it.

Your employees don’t need another financial webinar.
They need personal, practical support that actually changes how they feel and what they do with their money.

Money stress doesn’t look like a “money” problem at work

Financial stress rarely walks into HR and announces itself. It shows up as distraction, short tempers, disengagement, or someone quietly declining opportunities that would help their career because the timing feels too risky.

It’s also one of the few stressors that follows people to work every single day, rather than arriving as a one-off event. A restructure or a difficult client eventually resolves. A mortgage rate rise, or not knowing where next month’s numbers land, doesn’t switch off at 9am.

Why your EAP alone doesn’t close this gap

Your EAP is doing exactly what it’s designed to do; professional, confidential support for people in genuine distress. That matters, and it isn’t in question here.

What an EAP isn’t built for is teaching everyday financial capability. Counselling can help someone process the anxiety money is causing them. It generally isn’t set up to help them understand their pay structure, build a spending plan, or feel confident having a money conversation with a partner.

That’s a different kind of support, practical, skill-based, and preventative rather than crisis-response.

Where financial wellbeing education fits

This is where financial wellbeing education does its work: building everyday money confidence and capability, in plain English, before things reach crisis point.

It’s general education, not personal advice. Nobody’s reviewing an individual’s mortgage or telling them what to do with their super. It’s giving people the foundations; how budgeting actually works, how debt behaves, how to read their own numbers, so they can make their own informed decisions.

Layered with an EAP, you get both ends covered: support for people who are already struggling, and education that helps prevent financial stress building into something bigger in the first place.

What this can look like in practice

Financial wellbeing education for workplaces can sit alongside existing programmes in a few different ways:

  • A standalone session or short series, run like any other professional development topic.
  • Content woven into an existing wellbeing calendar, alongside mental health and physical health initiatives.
  • A resource employees can return to in their own time, for privacy around a genuinely personal topic.

Done well, it’s positioned the same way physical or mental health education is a normal, non-judgemental part of supporting people, not a red flag that something’s wrong.

The Takeaway

A strong wellbeing strategy supports the whole person, and for most people, money is part of that picture whether it’s named or not. An EAP handles the crisis. Financial wellbeing education handles the everyday end, building the confidence and capability that helps prevent the crisis in the first place.

Together, they give your people a genuinely complete safety net, not just a mental health one.

If you’d like to explore what financial wellbeing education could look like for your team, we’d love to talk it through with you.

The Financial Wellbeing Solution Your People Deserve — and Your Workplace Needs

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess #EAP #EmployeeAssistanceProgram
#EntrepreneurMindset


Why Is My Business Making Revenue, But No Profit?

Why Is My Business Making Revenue, But No Profit?

Revenue is the headline. Profit is the real story. If your sales are growing but the bank account never reflects it, here’s what the numbers are really telling you and what to do about it.

We hear this from business owners more than almost anything else. The invoices are going out. The sales are climbing. Clients are saying yes.

And yet, at the end of the month, there’s nothing left over. No breathing room. No reward for the hours going in.

If that’s you right now, we want you to hear this first: you’re not behind, and you’re not bad with money. You just haven’t had visibility on what’s actually happening between “money in” and “money left”. That’s a numbers problem, not a you problem and it’s fixable.

By the end of this, you’ll know the five most common reasons revenue and profit stop matching up, and exactly where to look first in your own business.

1. You’re pricing on gut feel, not margin

Most small business owners set their prices once, early on, based on what felt fair or what a competitor charged. Costs have moved since then supplies, wages, software, fuel, but the price hasn’t.

Every sale can look like a win on paper while quietly making you less than you think. Growing revenue with a shrinking margin doesn’t build a more profitable business. It just makes the problem bigger, faster.

Check this first: work out your gross profit margin on your top three products or services. If you don’t know that number off the top of your head, this is where to start.

2. Overheads have crept up quietly

Subscriptions renew. Rent increases. A “temporary” extra cost becomes permanent. None of these show up as one big decision, they show up as a hundred small ones, none of which felt worth questioning at the time.

Revenue can grow 20% while overheads grow 25%, and the business will still feel busier and further behind at the same time.

Check this first: list every recurring cost and ask, honestly, whether it’s still earning its place.

Your Overheads Didn’t Explode. They Quietly Crept Up.

3. You’re paying yourself last, or not consistently

Many owners take whatever’s left after everything else is paid, rather than a set wage. When there’s nothing left, that becomes the norm.

The trouble is, “whatever’s left” isn’t profit. It’s just what happened to survive the month. Without a wage built into your costs, you can’t actually see whether the business itself is profitable, because you’re the buffer absorbing the gap.

Check this first: build a wage for yourself into your cost base, even if you can’t take the full amount out yet. It changes what your numbers are really telling you.

4. Cash flow timing is hiding the truth

Cash in the bank and profit are not the same thing, even though they feel like they should be. A big invoice landing this week can make things look healthy, while a supplier payment or tax bill due next week tells a different story.

We business owners often read our bank balance as our scoreboard. It’s an important number, it’s just not the whole picture.

Check this first: look at your profit and loss statement, not just your bank balance, to see the real trend over the last three to six months.

5. You don’t have regular visibility on your numbers

This is the one underneath all the others. If you’re not reviewing your numbers on a consistent rhythm, small issues stay invisible until they’re big ones. Most owners find out something’s wrong months after it started, simply because nobody was looking.

Clarity doesn’t come from working harder. It comes from a regular, honest look at what the numbers are actually saying.

The Takeaway

Revenue growing while profit stalls is almost never one dramatic mistake. It’s usually five small, ordinary things happening at once; pricing, overheads, your own wage, cash timing, and visibility.

The good news is that each one is a decision you can revisit, not a personality flaw you have to fix. A better business creates a better life, and that starts with seeing clearly what’s really going on in yours.

If you want a clear, honest read on where your own numbers stand, that’s exactly what the Business Health Check is for.

The Edge Business Health Check

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess
#EntrepreneurMindset
 

Pay Yourself Like a Boss – The Owner Pay System That Builds Profit (Not Burnout)

Pay Yourself Like a Boss – The Owner Pay System That Builds Profit (Not Burnout)

If You’re Not Getting Paid Consistently… Your Business Is Giving You a Job (Not Freedom)

Let’s talk about the thing almost every small business owner quietly tolerates for way too long:

You run around all week making everyone else’s life easier…
…then you look at your bank balance and think:

“Cool. So when do I get paid?”

If you’re a tradie, franchisee, coach, consultant, or self-employed professional, this can show up as:

  • you take random “owner draws” when there’s money (then nothing for weeks)
  • you avoid paying yourself because you’re “being responsible”
  • you feel guilty taking money out of the business
  • you tell yourself it’ll be better “next month”
  •  

  • you have revenue… but no reliable income


And here’s the hard truth:
If you can’t pay yourself consistently, the business isn’t stable yet.

That doesn’t mean you’re failing.
It means your business needs foundations.

Because paying yourself isn’t a luxury. It’s a system.

Why Owner Pay Is the Cornerstone of a Healthy Business

Owner pay affects everything:

  • your stress levels
  • your relationships
  • your confidence
  • your decision-making
  • your ability to take time off
  •  

  • and your long-term wealth


When you’re not paying yourself properly, you’re more likely to:

  • undercharge (because you’re desperate for cash)
  • say yes to the wrong work
  • delay tax payments
  • overwork (to make up for low profit)
  •  

  • resent the business you built


Owner pay isn’t just a financial issue. It’s a sustainability issue.

And it’s one of the biggest reasons business owners burn out – even when they’re doing “well” on the outside.

Owner Pay Is the Cornerstone of a Healthy Business<br />

The Two Biggest Mistakes That Keep Owners Underpaid

Mistake #1: “I’ll Pay Myself What’s Left”

This is the most common trap:
Pay expenses first… and if anything is left, that’s owner pay.

But if your costs aren’t tightly controlled and your pricing isn’t profit-based, there’s rarely much left.
So owner pay becomes inconsistent, emotional, and reactive.

Better approach: owner pay becomes part of the plan, built into your weekly rhythm.

Mistake #2: Confusing Revenue with Profit

Revenue is vanity. Profit is sanity.

You can have a $25k month and still feel broke if:

  • your margin is thin
  • your overheads are high
  • tax isn’t set aside
  • you’re carrying too much unbillable time
  • your pricing doesn’t match reality

Profit is what creates stable owner pay.
Stable owner pay is what creates calm leadership.

The “Pay Yourself Like a Boss” Framework (Simple + Realistic) 

Here’s a practical approach that works across industries.

Step 1: Decide what “consistent” looks like (start smaller than you want)

Most owners try to jump straight to “I want $2,500/week.”

Love that energy. But consistency beats big numbers that don’t stick.

Start with a baseline that feels achievable and repeatable:

  • $600/week
  • $800/week
  • $1,000/week
  • Whatever makes sense based on current reality.

Your first win is not “highest possible.” Your first win is reliable.

Step 2: Pay yourself on a schedule (not on a feeling)

Choose a pay day. Weekly is often simplest. Fortnightly can work too.

The point is: You get paid like an employee of your business.
Because you are.

This alone changes your mindset from:
“I take money when I can…”
to:
“My business is responsible for paying me.”

Step 3: Create a money allocation structure

This can be with separate accounts or “buckets” you allocate within one account (separate accounts usually create stronger boundaries).

At minimum, you’re allocating income into:

  • Operating expenses (wages, tools, rent, subscriptions, fuel, etc.)
  • Tax/GST
  • Owner pay 
  • Buffer

When owner pay is allocated intentionally, it stops competing with every expense in your business.

Step 4: Use a weekly “money check-in” to stay in control

A weekly check-in prevents that “oops we spent it” moment.

Your weekly money check-in might include:

  • what came in this week
  • what bills are due soon 
  • what needs to be allocated to tax
  • confirm owner pay 
  • quick look at one key metric (margin, break-even, runway)

This process doesn’t need to be long. It needs to be consistent.

The Missing Link: You Can’t Pay Yourself Properly Without Pricing for Profit

Let’s say your owner pay target is $1,200/week.

If your pricing doesn’t include enough margin to fund that, you’ll keep “robbing Peter to pay Paul”:

  • borrowing from tax money
  • delaying supplier payments
  • stressing about the next invoice
  • doing more work to make up the shortfall

If you want reliable pay, you need reliable profit.,

You Can’t Pay Yourself Properly Without Pricing for Profit<br />

Pricing problems often look like this:

Tradies:

  • quotes don’t include enough for time + overheads + margin
  • variations aren’t priced clearly
  • you underestimate labour hours
  • you price to win jobs, not to make profit

Franchisees:

  • margins are tight and you need tighter systems
  • wages creep and overheads creep
  • stock management impacts cash 
  • owner pay gets squeezed when costs rise


Coaches/consultants:

  • pricing based on what feels “fair,” not what’s sustainable
  • not charging for delivery time (prep, comms, admin)
  • too much customised work for too little revenue
  • discounts and freebies that quietly eat margin

Profit-focused pricing means you understand these 3 basics:

  1. Your direct costs (materials, labour, subcontractors, platform fees, etc.)
  2. Your overheads (insurance, fuel, rent, tools, admin, software, marketing)
  3. Your required margin (profit + owner pay + buffer + tax readiness)


    You don’t need to be perfect. But you do need to stop guessing.

    The 5 Numbers That Make Owner Pay and Pricing Easier (and Less Emotional)

    You don’t need “all the numbers.” You need these:

    1) Gross Margin

    What’s left after direct costs.
    If this is too low, you’re working for nothing.

    2) Net Profit

    What you keep after overheads.
    This is what funds growth, buffer, and wealth.

    3) Break-Even Point

    The minimum revenue you must earn to cover costs.
    This is your “must hit” number.

    4) Owner Pay Baseline

    The amount you pay yourself consistently.

    5) Cash Runway

    How long you can operate with current cash.

    When you track these, owner pay stops being a debate.
    It becomes a decision based on reality.

    “But I Feel Guilty Taking Money Out of the Business”

    Let me say this plainly:

    If your business can’t pay you, it’s not a business. It’s a hobby with invoices.

    Owner pay isn’t selfish. It’s responsible. Because when you’re financially stable:

    • you make better decisions
    • you lead better
    • you stop panicking 
    • you build a business that supports your life


    And yes, sometimes the answer is:
    “We need to tighten costs.”
    Sometimes the answer is:
    “We need to raise pricing.”
    Sometimes the answer is:
    “We need better systems so we’re not bleeding time and money.”

    But it starts with telling the truth:
    I deserve to get paid for running this thing called “MY BUSINESS”.

    A Quick “Pay Yourself Properly” Audit

    If you answered “yes” to two or more of these, your foundations need attention:

    • Do you take owner drawings randomly instead of consistently?
    • Do you avoid looking at your numbers because it feels overwhelming?
    • Do you feel nervous when a big bill is due (even in a busy month)?
    • Do you “borrow” from GST/tax set-aside to cover expenses?
    • Do you underquote or discount because you’re worried you won’t win the job?
    • Do you feel like you’re working harder than ever but not getting ahead?

    No judgement. This is common. But it is changeable.

    This Is Exactly Why I’m Running The Edge Bootcamp

    You’ll leave with:

    • a simple money system
    • clearer separation between business and personal finances
    • confidence understanding Xero and key reports
    • and a clear 90-day implementation plan so you know what to do first, next, and next

    Also – important for busy business owners:

    • All tickets include digital resources, templates, and 90-day action plan tools
    • And yes, recordings are provided after the event (for personal use)

    So you can attend live, learn the system, then rewatch sections while you implement.

    By the way – you don’t need Xero – you’ll get extra value if you use it, but the principles apply across tools (MYOB, QuickBooks, spreadsheets, or still figuring it out).

    The Bootcamp is:

    • In person at East Fremantle Yacht Club
    • or you can attend live online

    It’s designed for real-world business owners, practical, step-by-step, and judgement-free, even if you feel behind.

    Want to Pay Yourself Consistently and Increase Profit?

    If you’re ready to stop guessing and start paying yourself like a CEO (with pricing and profit to back it up), then The Edge Bootcamp is your next step.

    It’s built for small business owners, tradies, franchisees, coaches and self-employed professionals who want more profit, better systems, cleaner numbers, and less overwhelm.

    ✅ 2-day live bootcamp
    ✅ In person (East Fremantle Yacht Club) or live online
    ✅ Templates + digital resources + 90-day action plan tools included
    ✅ Recordings provided after the event

    Join The Edge Bootcamp and walk away with a simple money system + a clear plan to pay yourself properly, price for profit, and build a business that supports your life.

    Note: This event provides education and general information, not personalised financial, accounting, legal, tax, investment, or health advice. Seek advice specific to your circumstances from qualified professionals.

    Join The Membership at Financial Management 101

    #HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings