Investing in Your Child’s Future – Beyond the Piggy Bank

Investing in Your Child’s Future – Beyond the Piggy Bank

Investing in your child’s future is often a top priority for parents in their 35s to 50s. While the traditional piggy bank is an excellent way to teach children to save, there are more substantial ways to ensure their financial security and educational future.

1. START WITH A PLAN

Begin by outlining your goals for your child’s future. Is it a college fund, seed money for a business venture, or financial support for a creative pursuit? Having clear goals aids in selecting the best investment strategy.

2. EDUCATION SAVINGS ACCOUNT

Consider opening an education savings account; there are many options depending on where you live. These accounts, which are specifically designed for educational expenses, frequently offer tax advantages.

3. DIVERSIFY WITH MUTUAL FUNDS

Mutual funds can be a great way for parents to diversify their portfolio without having to pick individual stocks. They allow you to invest small amounts on a regular basis.

4. BONDS: A SAFER BET

Government and municipal bonds can be safer investment options. They can be a good choice if you prefer a low-risk path to grow your child’s future fund.

5. TEACH FINANCIAL LITERACY

Involving your children in age-appropriate financial discussions is invaluable. Teach them about money management, saving, and investing. This education is just as important as the financial investment you are making in their future.
Teach your children about money management, saving, and investing.

6. CONSIDER REAL ESTATE INVESTMENTS

Real estate investing can provide long-term returns for those who are financially capable. This could be through purchasing a rental property or investing in a real estate investment trust. Ensure that you first seek financial advice if you are not experienced in property investing.

7. THE POWER OF A TRUST FUND

Setting up a trust fund for your child can provide financial security and is particularly useful for larger estates or specific family circumstances. It can also assist with tax planning. Seek financial and tax advice before setting up any trust to ensure it is suitable for your financial circumstances.

8. LIFE INSURANCE AS A FINANCIAL TOOL

A life insurance policy can be used to secure your child’s financial future in addition to providing protection. Some policies accumulate cash value over time, which can be used to fund your child’s education.

9. REGULAR REVIEWS AND ADJUSTMENTS

As with any investment, it is critical to review and adjust your strategies on a regular basis. This ensures that your investments are in sync with changing market conditions and educational costs.

10. INSTILLING THE VALUE OF MONEY

Encourage your child to save for the future, whether through part-time work or saving gifts. This instills a sense of responsibility and an appreciation for money.
Encourage your child to save for the future, whether through part-time work or saving gifts.

Investing in your child’s future requires more than just financial commitment; it’s about making informed decisions, taking a diversified approach, and instilling in them the value of financial responsibility. It’s a journey that goes well beyond the piggy bank, setting the stage for a brighter, more secure future for your children.

For any of the above strategies, I would encourage you to seek out professional advice first to ensure it aligns with your values, goals, and financial position.

Remember, it starts with you. Learning about money can give you the power to make smart financial decisions and reduce money-related stress over time. That’s where the LEARNING HUB helps you gain more financial knowledge, while providing you with the support and help you need.
Join the Learning Hub - Financial Management 101 by Karen G Adams
Debt Consolidation: A Midlife Financial Tune-Up

Debt Consolidation: A Midlife Financial Tune-Up

As we navigate our 30s, 40s, and early 50s, managing multiple debts can be like juggling with too many balls in the air. Whether it’s credit card debts, personal loans, or car payments, keeping track can be overwhelming. This is where debt consolidation comes in as a practical financial strategy, providing a much-needed tune-up for your finances.

1. UNDERSTANDING DEBT CONSOLIDATION

Debt consolidation is the process of combining multiple debts into a single loan with a lower interest rate. This simplifies payments and may save you money on interest, making debt management easier and less stressful.

2. ASSESS YOUR DEBTS

Begin by making a list of all your debts, including their balances, interest rates, and monthly payments. This exercise provides you with a clear picture of your overall debt, which is essential for effective debt consolidation.

3. FINDING THE RIGHT CONSOLIDATION LOAN

Look for a consolidation loan with a lower interest rate than the one you have now. Consider the loan term as well; a longer term may result in lower monthly payments but higher interest over time.

4. BEWARE OF HIDDEN COSTS

Keep an eye out for any fees associated with debt consolidation. Origination fees, balance transfer fees, and early repayment penalties can sometimes cancel out the benefits of a lower interest rate.

5. BUDGETING POST-CONSOLIDATION

It is critical to adjust your budget after consolidating. The goal is not only to effectively manage the new loan, but also to avoid incurring new debt.

6. BUILDING HEALTHY FINANCIAL HABITS

Debt consolidation is an excellent way to establish better financial habits. To avoid falling back into debt, commit to spending within your means and saving for emergencies.

It is critical to adjust your budget after consolidating. The goal is not only to effectively manage the new loan, but also to avoid incurring new debt.

7. CREDIT SCORE CONSIDERATIONS

Understand how debt consolidation may affect your credit score. Initially, it may cause a dip due to the hard inquiry from applying for a new loan. However, consistent payments can improve your credit score over time.

8. AVOIDING THE DEBT TRAP AGAIN

Consolidating debt should not be seen as a green light to rack up more debt. Avoid using credit cards or taking out new loans unless absolutely necessary.

9. SEEKING PROFESSIONAL ADVICE

Consult with a financial advisor to determine the best debt consolidation strategy for your unique situation and long-term financial goals.

10. CELEBRATIONG FINANCIAL MILESTONES

Track your progress and celebrate when you reach significant milestones in your debt repayment journey. This keeps you motivated and focused on your financial goals.

Debt consolidation, when done right, can be a game-changer in your financial journey. It’s not just about easing the burden of multiple debts but also about setting the stage for a more secure and stress-free financial future.

The LEARNING HUB at Financial Management 101 aims to help you gain more financial knowledge, while providing you with the support and help you need. Join the Learning Hub today for only $79 per month.
Join the Learning Hub - Financial Management 101 by Karen G Adams
Navigating Your Mortgage in Your Prime Years

Navigating Your Mortgage in Your Prime Years

If you are between the ages of 35 and 50, chances are you have a mortgage. It is an important part of your financial picture, but it does not have to be overwhelming. Navigating your mortgage during these prime years can be both empowering and financially rewarding if you take the right approach.

 UNDERSTANDING YOUR MORTGAGE

The first step in mastering your mortgage is understanding the terms of your loan – the interest rate, the type of rate (fixed or variable), the term, and any associated fees or penalties for early repayment. Knowledge is power, and understanding these basics is key.

2. CONSIDERING REFINANCING

The world of interest rates is ever-changing. If interest rates have fallen since you took out your mortgage, refinancing could save you a lot of money. But refinancing is not just about lower rates; it can also help you pay off your mortgage faster or free up cash for other investments.

3. EXTRA PAYMENTS: A LITTLE GOES A LONG WAY

Making extra mortgage payments can significantly reduce the amount of interest you pay over the life of the loan and shorten your payment term. Even small additional payments can add up over time.

4. BALANCING MORTGAGE WITH OTHER DEBTS

If you have other high-interest debts, such as credit cards or personal loans, it may be more advantageous to pay these off before making additional mortgage payments. It all comes down to prioritising your debts according to interest rates and financial impact.

5. UTILISING MORTGAGE OFFSET ACCOUNTS

Take advantage of any offset accounts that your mortgage may provide. Money in these accounts is used to offset the balance of your mortgage, lowering your interest payments while not committing to a longer repayment schedule.

Balancing Mortgage with Other Debts

6. EXPLORING MORTGAGE BREAK OPTIONS

Life can be unpredictable, and financial situations can change. Know your options for deferring mortgage payments if you ever need to, whether due to job loss, illness, or other major life events.

7. BE MORTGAGE-SAVVY WITH TAX

Learn how your mortgage affects your tax situation. There may be tax benefits associated with your mortgage for some people, particularly those who own investment properties.

8. SEEK PROFESSIONAL ADVICE

As a mortgage broker, we can be a valuable resource for you. We can provide tailored advice, assist you in understanding your options, and even assist you in obtaining a better mortgage deal.

9. PLAN FOR THE FUTURE

While you are focused on your current mortgage, do not forget to plan ahead. How will your financial situation look as you approach retirement? What role does your mortgage play in this picture?

Karen G Adams - Perth Mortgage Broker

10. CELEBRATE MILESTONES

Paying off your mortgage is a marathon, not a sprint. Celebrate the milestones, like reaching the halfway point or getting below a certain balance. It’s important to recognise and celebrate your financial achievements.

Managing your mortgage during your prime years requires a combination of strategy, knowledge, and foresight. You can transform your mortgage from a financial burden to a key component of your financial success by understanding your options and making informed decisions.

If you want to know whether your home loan is working effectively for you and your personal finances contact me at karen@harkenfinance.com for a chat.

Kickstart 2024 - Journey to a New You & New Year
New Year – New Financial Goals

New Year – New Financial Goals

Smart Money Management and Mortgage Strategies for 2024

As we welcome the year 2024, it’s the perfect time to reflect on our financial journeys and set new goals. For many, this means re-thinking our money management habits and looking at our mortgage options. Let’s dive into some key strategies that can help you achieve financial success in the New Year.

Reviewing Your Budget for 2024

The foundation of effective money management is a solid budget. This year, take a fresh look at your income and expenses. Could you allocate more funds to savings or investments? Are there any expenses you could trim or cut back on? Consider using budgeting apps or tools to track your finances more efficiently. I do have an easy spreadsheet that calculates your net position, so feel free to download this and link is at the bottom of this post.  Remember, a budget isn’t just about restricting expenses; it’s about making your money work effectively for your goals.

Invest in Financial Education

Knowledge is power, especially when it comes to finances. Dedicate time this year to educate yourself about investment options, market trends, and updated mortgage products. Whether it’s through books or joining my Learning Hub to access the online courses, coaching, and live events, enhancing your financial knowledge can lead to more informed decisions and better outcomes. 

Review and Refinance Your Mortgage

Interest rates fluctuate, as do your financial circumstances. It might be a good idea to review your current mortgage this year. Could you possibly get a better deal? Are there better mortgage products available to meet your current needs? Consulting with a mortgage broker like myself can provide insights into refinancing options that could save you money in the long run. Mortgages are not set-and-forget product.. This year, it’s crucial to review your current mortgage terms in light of the changing economic landscape.

Embrace Technology in Money Management

Technology is transforming the way we manage money. There are numerous tools at your disposal, ranging from online banking to investment apps. Explore how technology can help you simplify your financial management this year, whether it is setting up automatic savings, tracking investments, or managing mortgage payments.

Set Clear Financial Goals

What are your financial goals for this year? Maybe it is paying off a certain amount of debt, saving for a large purchase, or investing in real estate. Set clear, achievable goals and create a plan to reach them. Remember, goals are more effective when they are specific, measurable, and time-bound.  Goal setting for some is not an easy task, so getting support and having someone that can keep you on track is important.  More information and support can be found in the Learning Hub to get you started.

Join the Learning Hub - Financial Management 101 by Karen G Adams

Work with Professionals

Finally, don’t hesitate to seek professional advice. Money management and mortgage broking are both complicated fields, and working with someone like myself and a financial advisor can provide tailored advice specific to your own situation.

In conclusion, 2024 presents a new chapter in your financial journey. By reevaluating your budget, enhancing your financial knowledge, optimising your home loan, embracing technology, setting clear goals, and seeking professional advice, you can take control of your finances and make informed decisions that pave the way to financial stability and success.  Let’s make this year your best financial year yet!

Struggling with the high cost of living?

Struggling with the high cost of living?

Here are 9 ways to make your dollar go further and relieve some stress.

If you are looking for ways to tackle the rising cost of living, here are some things you can do TODAY to put money back into your pocket. Every dollar saved can make a difference!

As life changes, you need to review the major expenses in your household and see if you’re paying for things that you needed years ago but don’t now.

1. Take a look at your major costs.

When times are tight, it can make a world of difference to take a look at your subscriptions, recurring payments, gym memberships, and even your home, car, and health insurance. We recently went through the process of reviewing all our insurance policies, and we were actually surprised that we were able to save money and cut down on areas where we were over insured.  As life changes, you need to review the major expenses in your household and see if you’re paying for things that you needed years ago but don’t now. 

2. Look at how you’re paying for things.

You could save money in the short term by switching some of your subscriptions or payments from monthly to yearly, or you could temporarily reduce your spending by putting these items on hold to free up some cash in the short term.  Once you have more surplus cash, go back to yearly payments for subscriptions, as you can get a deal or save by paying for the full year.

3. Check your home loan rate.

If you want to save money, your home loan is a great place to start. Now is the time to review your home loan if you haven’t already. There are many features within your home loan that can make a BIG difference to the interest portion your bank or lending institution charges at the end of the month.  One example is that if you have an offset or redraw facility, learn how to maximise to take full advantage of how using these can save you money on your regular mortgage repayments.

4. Review your online streaming services.

I often review my online streaming services to see if we’re using them as often as we think and a month back cancelled those that I barely used.  There are so many out there, and do you really need them all?  By cutting down on one or two, you could save up to $20 – $30 per month, and that’s a big saving when money is tight. So think about canceling subscriptions to some of the streaming services you no longer regularly use.

By cutting down on one or two subscriptions, you could save up to $20 - $30 per month, and that’s a big saving when money is tight.

5. Cut down on take-away food

One of the biggest expenses for most households is buying takeout.  Take away food outlets are a time saver for busy people, but they are one of the biggest expenses in many households.  By saving $50 – $100 per month and not buying takeaway food, this can make a huge difference to your bank balance and can be used to pay down potential credit cards or other debt, which in the end will enable you to have more cash flow.

6. Plan your meals and think outside the box.

Sorry to be the bearers of bad news, but it is true: sticking to a reasonable meal plan can save you dollars at the checkout. Make a week long menu with everything from breakfast to dessert planned out, and include the family in what they’d like to eat. By getting them involved in the process, they are more likely to enjoy the food you’re cooking.  Make it a family event and teach your kids the power of saving by preparing and cooking meals the whole family will enjoy. Cook a little extra and freeze it, so on the days when you don’t feel like cooking and want to order take away, you can grab what you cooked the week earlier for dinner or lunch.

7. Shop for groceries online.

You can stick to your budget and meal plan when you shop for groceries online. Wednesday is a good day to shop at the supermarket because that is when many stores update their weekly specials.

8. Look at separate spending and savings accounts.

With your regular bills, put aside a set amount for your ongoing expenses into a separate account and have them directly debited from that account so they are paid automatically without you having to think about it.  All you need to do then is put regular money into that account at payday to ensure the amount is in there when the bills are due.

By having a separate spending account for bills, this stops you regularly dipping into your savings for non-essentials  

I have more information on how to manage your spending and savings and you can find this in the “Learning Hub” at financialmanagment101.com.au

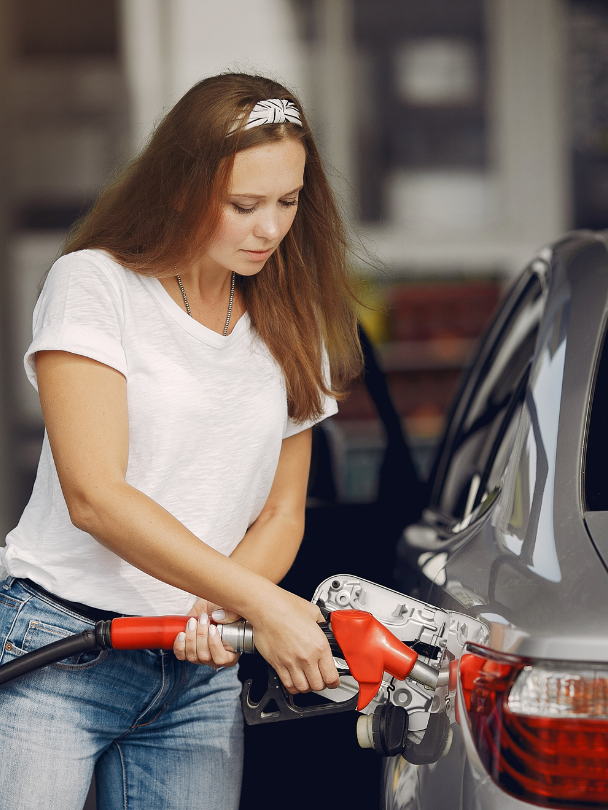
9. Compare petrol prices

And last but not least, the costs of fuel today are so high that it’s sucking every dollar from you just to fill up your tank today!  

There are apps that you can get on your smart phone to check daily fuel prices, so I would encourage you to do this when your tank is around ¼ – ½ left to go, so you don’t fill up at the last minute and have to pay a higher price.

Want more help managing your money?  Then check out this course that helps you budget and save your hard earned money.

Use apps that you can get on your smart phone to check daily fuel prices.