R U OK? (The Question You Never Ask Yourself)

R U OK? (The Question You Never Ask Yourself)

On September 10, most of Australia will be asking each other “R U OK?” Workplaces will run morning teas. There’ll be yellow everywhere. It’s a genuinely good day, and I’m glad it exists – it’s done a lot for getting these conversations out into the open where they belong, after years of them staying firmly behind closed doors.

But here’s the question I actually want to ask you, business owner to business owner… when’s the last time you asked yourself that?

We’re brilliant at checking in on everyone else. Staff, clients, family, that one supplier who always sounds a bit frazzled on the phone. But most business owners I talk to haven’t had an honest conversation with themselves in months. We’re too busy holding everything together to notice we might not be, ourselves. We’re the ones people come to when something’s gone wrong, which means we’ve quietly trained everyone around us, including ourselves to believe we don’t need checking on.

Running a business is one of the loneliest jobs going, if I’m honest. You’re the one everyone brings their problems to. There’s rarely anyone bringing you theirs, asking how you’re actually tracking underneath it all. Even the people who love you tend to ask “how’s the business going?” rather than “how are you going?” and those are very different questions with very different answers.

The performance of “fine”

There’s a particular skill business owners develop without meaning to, the ability to say “yeah, good, flat out” in a completely convincing tone while privately feeling anything but. It becomes automatic. Someone asks how you’re going at the school pickup, at the football, at a client meeting, and out it comes before you’ve even thought about it. Over time, that automatic answer starts to replace the honest one, even in your own head. You stop checking because you’ve gotten so good at performing that you don’t seem to need it.

So today, let’s flip it. Three questions, and actual permission to answer them properly, without the reflexive “yeah, good, flat out” that we all give without thinking.

Am I okay, or am I just coping?

There’s a real difference. Coping looks like getting through the week in one piece, ticking things off, keeping the wheels on. Okay looks like genuinely enjoying the thing you built, feeling proud of it, curious about where it’s going, energised rather than depleted by it. If you’ve been in coping mode for a while now, that’s worth noticing, not brushing off with “it’s just a busy season,” because busy seasons have a habit of becoming permanent if nobody names them.

There’s no shame in “coping” as an honest answer. It’s often the truest thing a business owner has said about themselves in months, once they finally stop and let themselves say it. The shame only comes from pretending otherwise for too long.
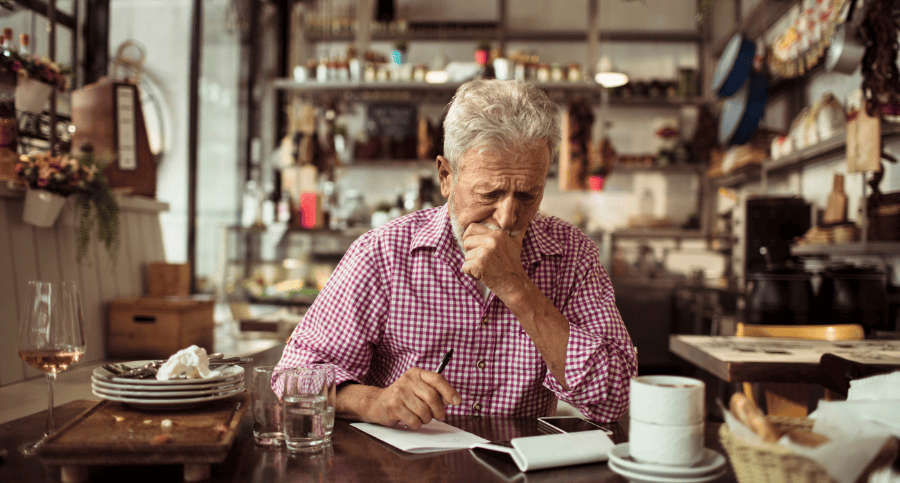
What am I carrying that I haven't said out loud?
For a lot of business owners, it's the money. The gap between what the business brings in and what it feels like it should be bringing in by now, given how hard you're working.

What am I carrying that I haven’t said out loud?

For a lot of business owners, it’s the money. The gap between what the business brings in and what it feels like it should be bringing in by now, given how hard you’re working. That gap is heavy to carry on your own, and you really don’t have to. I’ve had conversations with business owners who’ve been sitting on that particular worry for years, silently, because it felt embarrassing to say out loud, like admitting it meant admitting they’d failed at something. It’s not embarrassing. It’s incredibly common, and it’s fixable once it’s actually spoken about, usually far more fixable than the years of silent worry suggested.

Sometimes what people are carrying isn’t even the money itself, it’s the fear of what the money says about them. That’s a heavier load than the actual numbers ever are.

Who’s actually in my corner?

Not staff. Not clients. I mean the people who ask how you’re going, not just how the business is going. If that list is short, that’s your sign; a mentor, a community, or even just a standing coffee with someone who genuinely gets what this life is like. Business ownership can be surprisingly isolating even when you’re surrounded by people all day, because being surrounded by people isn’t the same as being known by them.

The physical signs worth noticing

Sometimes the “am I okay” question is easier to answer by looking at the body rather than the mind. Are you sleeping properly, or lying awake running through tomorrow’s problems? Are you short-tempered with people who don’t deserve it? Have you stopped doing the small things that used to recharge you – the walk, the round of golf, the Sunday paper, because there’s “no time”? These aren’t small details. They’re often the clearest signal available that the tank’s getting low, well before the mind is ready to admit it in so many words.

It’s okay to not have the answer yet

If you sat with those three questions and didn’t love your answers, that’s not a failure, that’s information. The whole point of asking is so you can actually do something with what you find, rather than carrying it around unexamined for another six months. Awareness on its own doesn’t fix anything, but it’s the step that has to come first, and it’s the step most business owners skip entirely because it’s uncomfortable.

You can’t run a healthy business from an empty tank. Checking in on yourself isn’t soft, whatever the old-school hustle crowd would have you believe, it’s strategy, plain and simple. A business owner who’s running on empty makes worse decisions, snaps more easily, and enjoys less of what they’ve built. None of that helps the business either – it’s not a trade-off between looking after yourself and looking after the business. They’re the same job.

And if part of what’s weighing on you is the money side of things, that’s exactly what The Edge exists for. A place where you’re not carrying it solo, surrounded by other business owners asking each other the real questions instead of the polite ones.

Join The Edge: https://financialmanagement101.com.au/work-with-karen/the-edge/

And if today’s the day you actually need to talk to someone, Lifeline is on 13 11 14, any hour, no appointment needed.

What to do once you’ve asked yourself

Asking the question is the easy part, once you’ve actually made yourself do it. The harder part is what comes next, because most business owners are excellent at identifying a problem and then filing it away under “deal with that eventually.” So if any of the three questions above landed a bit close to home, don’t let it end there.

Pick one small thing. Not a complete overhaul of your life, not a dramatic announcement to everyone that you’re “making changes.” One small thing; a call to a friend you’ve been meaning to make, an actual look at the money situation you’ve been avoiding, a boundary around one evening a week that’s just yours. Small, specific, doable this week, not “someday.”
Business owners checking in on business owners

Business owners checking in on business owners

There’s a particular kind of relief that comes from talking to someone else who genuinely understands what this life involves – the highs that nobody else quite gets excited about the way you do, and the lows that nobody else quite understands the weight of either. Friends and family love you, but unless they’ve run a business themselves, there’s a layer of it they simply can’t relate to, however much they try.

That’s part of why community matters so much here. Not a support group in the clinical sense, just other people in the same boat, who ask “how are you really going” and actually mean it, who’ve had the sleepless nights over cash flow and the quiet pride over a client win, and who get it without you having to explain the whole backstory first.
THE EDGE Membership

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess
#EntrepreneurMindset
 

How to Stop Feeling Overwhelmed by Your Finances in 2025

How to Stop Feeling Overwhelmed by Your Finances in 2025

Does the thought of opening your bank app make your stomach drop? Are you constantly worried about bills, debt, or whether you’ll ever have enough to get ahead? You’re not alone. Financial overwhelm is incredibly common, especially with the rising cost of living and competing demands on your paycheck. But here’s the good news: you don’t have to stay stuck in this cycle.

In this blog, we’ll explore why financial overwhelm happens and, more importantly, how you can overcome it. By following these practical steps, you can regain control, reduce stress, and create a plan to manage your money with confidence.

Why Do We Feel Overwhelmed by Money?

1. Too Many Unknowns

When you’re not sure where your money is going or how much debt you owe, it’s easy to feel out of control. The unknown creates anxiety, and avoidance becomes a coping mechanism.

2. Unrealistic Expectations

Social media and society often paint an idealised picture of what financial success looks like – think flashy cars, designer clothes, and lavish holidays. Trying to measure up can make you feel like you’re failing, even if you’re doing fine.

3. Emotional Baggage

Money is rarely just about numbers. It’s tied to emotions, past experiences, and even our self-worth. Financial stress can feel personal, making it harder to address objectively.

Money is rarely just about numbers. It’s tied to emotions, past experiences, and even our self-worth.

How to Stop Feeling Overwhelmed?

Step 1: Acknowledge Your Feelings

The first step to overcoming financial overwhelm is to acknowledge it. Pretending you’re fine or ignoring the problem only makes things worse.

How To Do This?

      • Take a moment to name your emotions: Are you feeling stressed, ashamed, or frustrated?
      • Write down your worries in a journal. Sometimes, seeing them on paper helps put them into perspective.
      • Remind yourself that financial challenges are common and not a reflection of your worth.

Step 2: Understand Your Starting Point

You can’t fix what you don’t measure. It’s time to face the numbers, even if it feels uncomfortable. Knowledge is power, and understanding your financial situation is the first step to regaining control.

How To Do This?

      • List Your Debts: Write down every debt you owe, including balances, interest rates, and minimum payments.
      • Track Your Spending: For 30 days, track every expense. This helps you understand where your money is going.
      • Calculate Your Net Worth: Add up your assets (savings, investments, property) and subtract your liabilities (debts).

This process might feel daunting, but remember: it’s just data. The goal is to understand your starting point, not to judge yourself.

Write down every debt you owe, including balances, interest rates, and minimum payments.<br />

Step 3: Simplify Your Finances

Complex financial systems add to the sense of overwhelm. Simplify your money management by automating as much as possible and consolidating accounts when appropriate.

How To Do This?

      • Automate Bill Payments: Set up automatic payments for recurring expenses like utilities, rent, or mortgage.
      • Streamline Accounts: Consider consolidating multiple credit cards or savings accounts to reduce confusion.
      • Set Up Automatic Savings: Even a small, consistent transfer to savings builds momentum and reduces the stress of “finding” money to save.

Step 4: Break Goals Into Bite-sized Steps

Big financial goals can feel intimidating. Instead of trying to tackle everything at once, break your goals into smaller, actionable steps.

Example:

      • Instead of “Pay off $10,000 in debt,” focus on paying an extra $100 a month toward your highest-interest debt.
      • Instead of “Save for a home deposit,” aim to save $50 a week into a designated savings account.
      • Instead of “Fix my finances,” commit to reviewing your budget once a week.

These small wins build confidence and momentum, making the larger goal feel achievable.

Break Goals into Bite-Sized Steps

Step 5: Focus On What You Can Control

Financial overwhelm often comes from focusing on things outside your control, like unexpected expenses or economic conditions. Shift your energy to what you can influence.

What You Can Control:

      • How you spend your money
      • How you budget and save
      • How you approach debt repayment

When you focus on actionable steps, you’ll feel more empowered and less overwhelmed.

Step 6: Build A Support System

You don’t have to navigate your financial challenges alone. Whether it’s a friend, family member, or myself as your financial coach, having someone to talk to can make a world of difference.

Ways To Build Support:

      • Join a Community: Online groups or forums can connect you with people facing similar challenges.
      • Work with a Coach: Programs like Master Your Money provide step-by-step guidance and accountability.
      • Talk to Your Partner: If you share finances, make sure you’re working together toward shared goals.

Step 7: Shift Your Money Mindset

Sometimes, financial overwhelm is more about mindset than numbers. Reframing how you think about money can reduce stress and help you approach challenges with clarity.

Mindset Shifts To Try:

      • Replace “I’ll never get out of debt” with “I’m taking small steps every day to reduce my debt.”
      • Replace “I’m bad with money” with “I’m learning how to manage money better.”
      • Focus on progress, not perfection.

Step 8: Celebrate Your Wins

Overcoming financial overwhelm doesn’t happen overnight, but every step you take is progress worth celebrating. Recognising your achievements – big or small, keeps you motivated.

Ways to Celebrate:

      • Treat yourself to a small reward, like a coffee or a movie night, when you hit a milestone.
      • Keep a “win journal” where you document every positive financial step.
      • Share your success with someone who will cheer you on.
Keep a “win journal” where you document every positive financial step

Why 2025 Can Be The Year You Break Free

This year is your opportunity to turn things around. With a clear plan, a supportive community, and the right mindset, you can overcome financial overwhelm and take control of your money. Programs like Master Your Money are designed to help you break through the noise and focus on what matters most: your financial peace of mind.

Conclusion

Feeling overwhelmed by your finances is common, but it’s not permanent. By taking small, intentional steps and focusing on what you can control, you can move from chaos to clarity. Remember, progress is better than perfection, and every step forward is a step closer to financial freedom.

Start today by choosing one action, whether it’s tracking your spending, automating a bill, or simply acknowledging your financial stress. Your future self will thank you for it.

The Master Your Money Program is FOR YOU if:

?? You’re earning good income but still feel stuck in a cycle of stress or overspending.
?? You want to break free from limiting beliefs like “I’m bad with money” or “There’s never enough.”
?? You’re ready to build wealth without sacrificing the things you love.
?? You dream of financial freedom and need the tools and mindset to make it happen.

This is more than a mindset shift—it’s a transformation that puts you on the path to lasting financial success! ?

The 90 Day Money Makeover

Financial Fitness: How to Get Your Money in Shape in Your 40s and 50s

Financial Fitness: How to Get Your Money in Shape in Your 40s and 50s

Welcome to the Financial Fitness Bootcamp, where we will whip your finances into shape while smiling and laughing along the way. Financial fitness, like physical fitness, requires discipline, consistency, and a sense of humour. So grab your sweatband and water bottle—we are about to get your money in great shape!

1. SET YOUR FINANCIAL GOALS: THE FITNESS PLAN

Every fitness journey starts with a goal, and your financial fitness is no exception. What are you hoping to achieve? Paying off debt? Building an emergency fund? Saving for retirement? Write down your goals and make them SMART—Specific, Measurable, Achievable, Relevant, and Time-bound. Having clear goals gives you direction and motivation to stay on track.

2. BUDGET: THE FINANCIAL WORKOUT PLAN

Consider your budget to be your financial exercise plan. It outlines how you’ll allocate your income to meet your goals. Start by keeping track of your income and expenses. Identify areas where you can cut back (for eg; unused gym membership) and reallocate those funds towards your goals. Use budgeting tools or apps to keep it simple. And remember, just like with a workout plan, consistency is key. Review your budget regularly and make adjustments as needed.

3. BUILD AN EMERGENCY FUND: YOUR FINANCIAL SAFETY NET

An emergency fund is like a spotter in the gym—it’s there to catch you when you fall. Aim to save 3-6 months’ worth of living expenses. Start with a small, achievable goal, like $1,000, and build from there. Automate your savings to make it easier. Having a financial safety net provides peace of mind and protects you from unexpected expenses.

4. DEBT REPAYMENT: THE CARDIO OF FINANCIAL FITNESS

Paying down debt is the cardio of financial fitness. It may not be fun, but it is necessary for a healthy financial life. List your debts and prioritise them. Use the avalanche method to pay off high-interest debt first, and the snowball method to tackle smaller debts and gain momentum. Celebrate every victory along the way, no matter how small. Remember, each payment brings you closer to financial freedom.

5. RETIREMENT SAVINGS: THE STRENGTH TRAINING OF FINANCE

Saving for retirement is similar to strength training in that it gradually increases your financial muscle. Make regular contributions to your retirement accounts. Take full advantage of any matching benefits provided by your employer. Increase your contributions whenever possible, particularly if you receive a raise or bonus. And remember to diversify your investments to reduce risk. The goal is to lay a solid financial foundation that will help you in your golden years.

6. INVESTING: THE PERSONAL TRAINER OF YOUR FINANCES 

Investing can be intimidating, but think of it like a personal trainer—it will help you achieve your goals faster. Start with basic investment accounts such as superannuation funds or retirement savings accounts. Learn about different investment options and strategies. Consider working with a financial advisor to create a personalised investment plan. The key is to start now and let the power of compound interest work in your favour.

7. FINANCIAL SELF-CARE: DON’T FORGET TO STRETCH 

Just as stretching is essential for physical fitness, so is financial self-care. Take the time to review your financial goals and progress on a regular basis. Celebrate your achievements, no matter how small. And don’t forget to reward yourself—within reason. Financial fitness is all about balance, so make sure to enjoy life along the way.

8. ACCOUNTABILITY: FIND YOUR FINANCIAL WORKOUT BUDDY

A workout buddy makes it easier to stay accountable, as does financial fitness. Share your goals with a trusted friend or family member. Join financial communities or forums to find support and motivation. Consider working with a financial coach or advisor to help you stay on track. Having someone to encourage you and hold you accountable can make all the difference. Join my monthly coaching program to stay motivated and on track with your financial goals, like a personal trainer does when you want to achieve your fitness goals.

9. KEEP LEARNING: FINANCIAL EDUCATION NEVER STOPS

The world of finance is constantly changing, and staying informed is crucial. Keep your knowledge up to date by reading books, taking courses, and following financial blogs. Consider subscribing to financial newsletters or podcasts for regular updates and tips. The more you know, the better equipped you are to make informed financial decisions. You can stay informed by subscribing to my regular podcast and newsletter – so be sure to check them out.

10. STAY FLEXIBLE: ADAPT AND ADJUST

Just like with physical fitness, your financial journey will have ups and downs. Stay flexible and be ready to adapt. Life happens—unexpected expenses, changes in income, or shifting priorities. The key is to stay focused on your goals and adjust your plan as needed. Remember, this is a marathon, not a sprint.

Congratulations, you’ve completed the Financial Fitness Bootcamp! By setting goals, creating a budget, building an emergency fund, paying off debt, saving for retirement, investing, practicing financial self-care, staying accountable, continuing your financial education, and staying flexible, you’re well on your way to financial health. Now, go ahead and achieve your financial goals—you have got this!

Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

Mastering Budget and Saving Techniques
Free Budgeting Spreadsheet

GRAB YOUR OWN COPY FOR FREE

YOUR MONEY eMagazine

Are you ready to take control of your finances and secure a brighter future?

Dive into “Your Money,” the premier e-magazine by Karen G Adams, the Founder of Financial Management 101.

Subscribe for FREE!