Father’s Day and the Business Owner Who Can’t Switch Off

Father’s Day and the Business Owner Who Can’t Switch Off

Happy Father’s Day to every business owner who “just needs to check one email” during the barbecue.

You know the scene. Phone face-down on the table, out of principle. Two minutes later, face-up again. “Just checking something quick.” Forty-five minutes later, still checking, while someone’s asking if you want another sausage and you’re not entirely sure you heard them the first time.

Here’s the bit nobody says out loud; if you genuinely can’t switch off for one Sunday, it’s not because you’re dedicated, it’s because something in the business is relying entirely on you being switched on, all the time. That’s not commitment. That’s a business that hasn’t had its systems built yet, quietly telling on itself every time your phone lights up at a family lunch.

I say this with love, because I’ve been that person too. There’s a particular kind of guilt that creeps in when you’re not checking, like something’s about to fall over the second you look away. Sometimes it will. That’s actually useful information, not a personality flaw. It tells you precisely where the weak point is, rather than leaving you to vaguely feel like you should “be better at switching off,” which is advice with nothing practical underneath it.
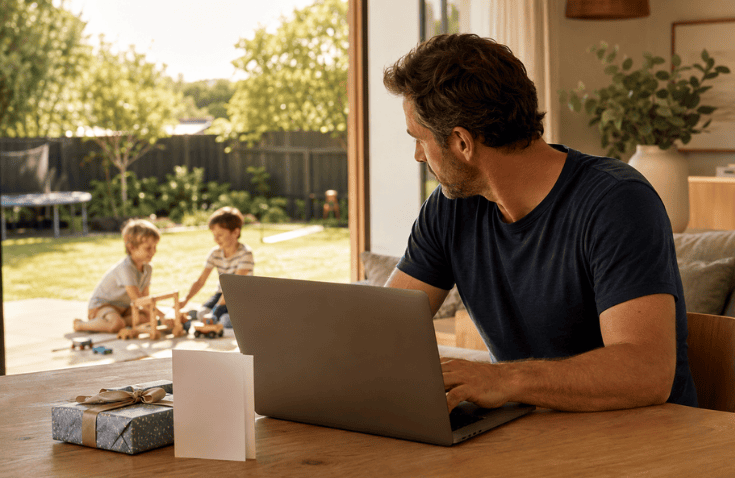
Happy Father's Day to every business owner who "just needs to check one email" during the barbecue.

It’s not a discipline problem

Most business owners think the fix is “just try harder to unplug.” Buy a nicer phone case, set a screen time limit, promise yourself Sunday is sacred. And then Sunday arrives and none of it holds, because the willpower was never the actual problem.

You can’t discipline your way out of a business with no systems, no visibility, and nobody else who knows where anything lives. If you’re the only one who knows the client’s login, the only one who knows how the invoicing actually works, the only one who can answer “did that order go out,” then of course you can’t switch off – you’re not being undisciplined, you’re being the entire operations department in one exhausted human body.

The phone-checking isn’t the actual problem. It’s just the symptom you can see. Fixing the symptom without fixing the cause is like taking the batteries out of a smoke alarm because the beeping is annoying.

What it costs, quietly

There’s a cost to this that doesn’t show up on the profit and loss but shows up everywhere else. It shows up in the conversation you half-listened to. The moment with the kids you were technically present for but not really in. The mate who stopped inviting you to things because you always seemed distracted, or cancelled at the last minute, or spent the whole time with one eye on your phone. None of that gets tracked anywhere. It just quietly accumulates until one day you notice the gap.

The real question to ask

The more useful question isn’t “how do I switch off more.” It’s “what would genuinely happen today if I didn’t check my phone at all?” If the honest answer is “everything would fall apart”, that tells you exactly where the gaps are. Not a criticism. A map.

Sit with that answer for a second. Is it really everything, or is it one or two specific things? Usually, when people actually write it down, the list is shorter than the panic suggested. There’s something almost funny about how big the fear feels compared to how short the actual list turns out to be once it’s on paper instead of in your head.

Building the buffer, one piece at a time

You don’t need to overhaul the whole business in a weekend to get some breathing room back. Start with the smallest, most repeated interruption, the thing that pulls you out of family time most often and ask what it would take to hand even part of that off. A simple checklist someone else can follow. A shared login instead of a personal one. An automated reminder instead of you personally remembering. None of these are big, dramatic fixes. They’re small, boring, unglamorous changes, and they’re exactly the ones that actually stick.

One small fix before the next family day

Before your next family day, try this. Write down the three things that would actually need you if they went sideways. Then ask yourself, honestly, whether one of those three could be handled by a simple checklist, a bit of automation, or someone else entirely, instead of by you personally, every single time. Fix one. That’s next Father’s Day a little more sorted than this one and the one after that, a little more sorted again. This isn’t a one-weekend fix. It’s a habit of slowly handing things off until your presence isn’t the only thing holding the whole operation together.

A better business creates a better life and a better life includes actually being at the barbecue, present for the conversation, not just physically there while mentally reconciling last month’s invoices.

The version of success worth aiming for

There’s a version of business success that gets celebrated a lot, the one measured in revenue, growth, how many staff you’ve got, how big the operation’s gotten. It’s a fine measure, as far as it goes. But it misses something important, which is whether the person who built all of that can actually enjoy a Sunday without their phone glued to their hand.

I’d argue the better measure of success is this – can you take a full day off, properly off, and come back to a business that’s still standing, without having spent the whole day half-present because part of you never left? That’s a much harder thing to build than revenue, and it’s a much better thing to have.
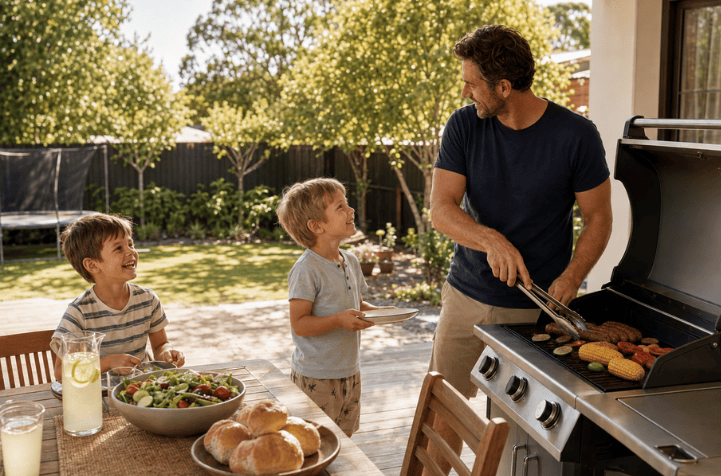
Building the systems that let you switch off isn't a luxury add-on. It's kind of the whole point of doing this in the first place.

Kids notice more than we think

There’s a particular moment a lot of business-owner parents have at some point; a kid saying something like “you’re always on your phone,” delivered completely matter-of-factly, no drama attached, which somehow makes it land harder than if they’d shouted it. Kids don’t measure your love by how hard you’re working for their future. They measure it by whether you were actually there when they wanted to tell you something, show you something, or just have you sitting next to them doing nothing in particular.

That’s not a guilt trip, plenty of us are working exactly because we want a better life for them. It’s just worth remembering that the “better life” bit doesn’t only mean money down the track. It means you, actually present, more often than not.

Building the systems that let you switch off isn’t a luxury add-on. It’s kind of the whole point of doing this in the first place.

If you want help working out exactly where your business is leaning on you too hard, The CEO Dashboard is built for precisely that, a clear look at what’s actually relying on you, and what could run perfectly well without you for a Sunday afternoon.
The CEO Dashboard

#HowToResetMyMoneyMindset #NewYearFinancialMindset #HowToStartFreshWithMoney  emergency fund australia, money management, family savings #SmallBusinessOwner #BusinessGrowth #CashflowManagement #BusinessSuccess
#EntrepreneurMindset
 

Breaking the Chains: How to Escape the Cycle of Living Paycheck to Paycheck

Breaking the Chains: How to Escape the Cycle of Living Paycheck to Paycheck

Do you feel like your money disappears as soon as you get paid? Are you constantly counting the days until your next paycheck? If so, you’re not alone – millions of people find themselves trapped in the cycle of living paycheck to paycheck. But here’s the good news: escaping this cycle isn’t just possible, it’s within your control.

Let’s break the chains and create a life where money works for you, not the other way around.

Step 1: Shift from Survival Mode to Financial Strategy

Most people stuck in the paycheck-to-paycheck cycle don’t have a spending problem, they have a strategy problem. Instead of reacting to financial emergencies, it’s time to start planning proactively.

Ask yourself:

  • What would financial stability look like for me?
  • How much money do I need to feel secure between paychecks?
  • What’s stopping me from breaking free?

By shifting your focus from surviving to strategising, you take back control of your finances.

Shift from Survival Mode to Financial Strategy

Step 2: Find Your Financial Leaks (and Plug Them!)

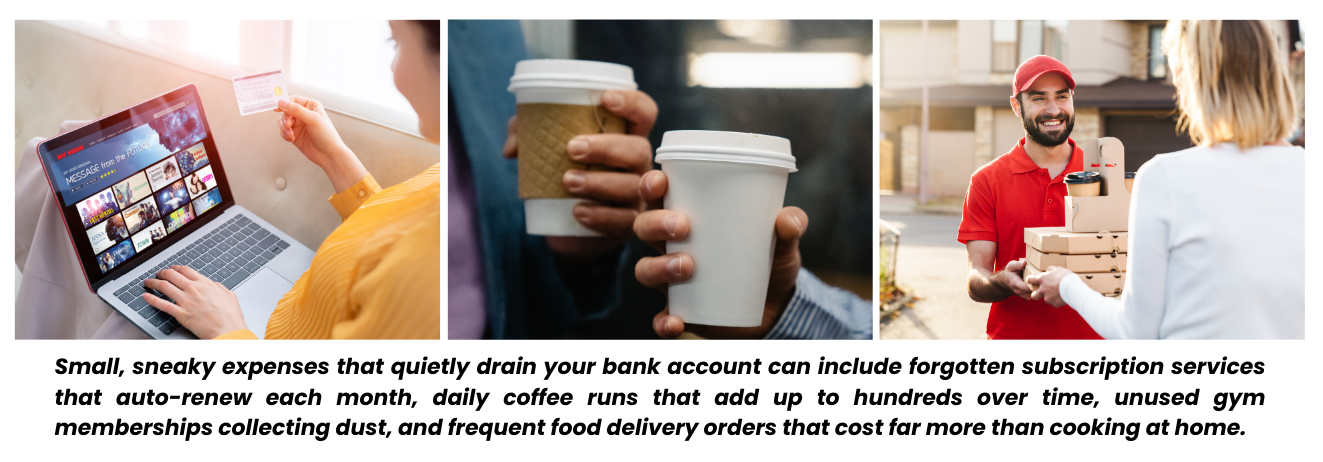
Ever wonder where all your money goes? It’s time to find out. Track your spending for a month and identify the small, sneaky expenses draining your bank account. These could be:

  • Subscription services you forgot about
  • Daily coffee runs that add up to hundreds a month
  • Unused gym memberships
  • Frequent food delivery orders

Plugging these leaks doesn’t mean cutting out all enjoyment – it means being intentional about where your money goes.

Small, sneaky expenses might be draining your bank account

Step 3: Pay Yourself First – Even If It’s Just $10

The key to breaking the cycle is creating a buffer between you and financial stress. Start by setting aside a small amount from every paycheck – yes, even if it’s just $10. The act of saving builds momentum and rewires your brain for financial growth.

Open a separate savings account and automate deposits. Over time, you’ll build a financial cushion that prevents you from relying on the next paycheck.

Step 4: Increase Your Income Without Working More Hours

If your expenses leave you with nothing to save, it’s time to boost your income. But before you assume that means working more hours, consider these options:

  • Ask for a raise – most employees don’t, and employers often have room to negotiate.
  • Sell unused items – your clutter could be someone else’s treasure.
  • Offer freelance or side gigs – platforms like Fiverr, Upwork, and Etsy offer ways to monetise your skills.
  • Rent out assets – if you have an extra room, parking space, or equipment, consider renting it out.

Small income boosts can create big shifts in your financial freedom.

Step 5: Use Your Credit Wisely (Not Recklessly)

Credit can be a tool or a trap – it all depends on how you use it. Instead of relying on credit cards to cover gaps, use them strategically:

  • Pay off balances in full to avoid high-interest debt.
  • Use credit card rewards for cash back or travel perks.
  • Build your credit score to access lower rates on future loans.

Mastering your credit is key to long-term wealth-building.

Step 6: Create a 3-Month Escape Plan

Breaking free isn’t about overnight miracles, it’s about consistent steps in the right direction. Create a 3-month plan with small, achievable goals:

  • Month 1: Cut financial leaks and save at least $50.
  • Month 2: Increase income by $200 through side gigs or negotiations.
  • Month 3: Use extra income to build a financial cushion and pay off high-interest debt.

By the end of 90 days, you’ll have proof that escaping the paycheck-to-paycheck cycle is possible.

FINAL THOUGHTS

Financial freedom isn’t just for the lucky, it’s for those who take action. You have the power to rewrite your financial story and create a life where money works for you.

If you’re ready for a deeper transformation and a complete guide to managing your money, my Master Your Money Program will provide the step-by-step tools to take control once and for all.

You deserve financial peace – start your escape plan today!

Your Money Story is Holding You Back: Here’s How to Rewrite It

Your Money Story is Holding You Back: Here’s How to Rewrite It

We all have a money story. It’s the narrative we’ve built over time based on our experiences, upbringing, and beliefs about money. Some of us grew up hearing, “Money doesn’t grow on trees,” while others were told, “You have to work hard for every penny.” These messages, whether spoken or unspoken, shape how we interact with money as adults.

But what if your money story is holding you back? What if deep down, you believe you’re not capable of financial success or that you’re destined to struggle? The good news is that your money story isn’t set in stone. You have the power to rewrite it.

Here’s how to break free from limiting beliefs and create a financial narrative that empowers you.

STEP 1: KNOW YOUR NUMBERS

Before you can change your money story, you need to understand what it is. Ask yourself:

    • What did I hear about money growing up?
    • How did my parents or caregivers handle money?
    • What emotions come up when I think about my finances?
    • Do I believe money is a source of stress, power, freedom, or something else?

Write down the recurring patterns you’ve noticed in your financial life. Have you always lived paycheck to paycheck, even when you earn more? Do you sabotage financial success out of guilt or fear? Awareness is the first step to transformation.

What did you hear about money growing up?

STEP 2: CHALLENGE THE BELIEFS THAT NO LONGER SERVE YOU

Many of our money beliefs were inherited, not chosen. But just because you grew up with certain financial patterns doesn’t mean you have to continue them.

Take a belief like, “I’m just bad with money.” Ask yourself: Is this actually true? Or have I just made mistakes in the past that I can learn from? Reframe it: “I am learning how to manage my money in a way that aligns with my goals.”

Your beliefs create your reality. If you constantly tell yourself you’ll never be wealthy, your actions will reflect that. Instead, adopt empowering beliefs like:

    • “I am capable of building wealth.”
    • “Money is a tool that supports my dreams.”
    • “I deserve financial abundance.”

STEP 3: REWRITE YOUR MONEY STORY

Now it’s time to create a new money story, one that aligns with your goals and values. Imagine your ideal financial future. What does it look like? How do you feel about money? How do you handle it?

Write down your new story as if it’s already true. For example: “I am financially confident. I make smart decisions with my money, and I attract opportunities for abundance. I feel secure, knowing that I am in control of my finances. Money flows to me easily, and I use it to create a fulfilling life.”

The more you affirm this new story, the more your subconscious mind starts to accept it as reality.

Take Actions That Support Your New Money Story

STEP 4: ELIMINATE DEBT STRATEGICALLY

Your environment shapes your mindset. If you’re constantly hearing negative messages about money, it’s harder to shift your beliefs. Seek out people, books, and resources that reinforce your new money story.

This is why I created my Monthly Coaching program, where you can access THE VAULT – a collection of financial courses, tools, and community support designed to help you step into financial empowerment. And if you’re ready for a full financial transformation, the Master Your Money program will guide you through everything you need to break free from financial limitations.

Ready to Master Your Money?

Your financial future isn’t dictated by your past. You have the power to rewrite your money story and create a new reality – one where you feel confident, in control, and financially free.

The question is: What story will you choose to tell yourself from today onward?

The pen is in your hands.

The 90 Day Money Makeover
Financial Fitness: How to Get Your Money in Shape in Your 40s and 50s

Financial Fitness: How to Get Your Money in Shape in Your 40s and 50s

Welcome to the Financial Fitness Bootcamp, where we will whip your finances into shape while smiling and laughing along the way. Financial fitness, like physical fitness, requires discipline, consistency, and a sense of humour. So grab your sweatband and water bottle—we are about to get your money in great shape!

1. SET YOUR FINANCIAL GOALS: THE FITNESS PLAN

Every fitness journey starts with a goal, and your financial fitness is no exception. What are you hoping to achieve? Paying off debt? Building an emergency fund? Saving for retirement? Write down your goals and make them SMART—Specific, Measurable, Achievable, Relevant, and Time-bound. Having clear goals gives you direction and motivation to stay on track.

2. BUDGET: THE FINANCIAL WORKOUT PLAN

Consider your budget to be your financial exercise plan. It outlines how you’ll allocate your income to meet your goals. Start by keeping track of your income and expenses. Identify areas where you can cut back (for eg; unused gym membership) and reallocate those funds towards your goals. Use budgeting tools or apps to keep it simple. And remember, just like with a workout plan, consistency is key. Review your budget regularly and make adjustments as needed.

3. BUILD AN EMERGENCY FUND: YOUR FINANCIAL SAFETY NET

An emergency fund is like a spotter in the gym—it’s there to catch you when you fall. Aim to save 3-6 months’ worth of living expenses. Start with a small, achievable goal, like $1,000, and build from there. Automate your savings to make it easier. Having a financial safety net provides peace of mind and protects you from unexpected expenses.

4. DEBT REPAYMENT: THE CARDIO OF FINANCIAL FITNESS

Paying down debt is the cardio of financial fitness. It may not be fun, but it is necessary for a healthy financial life. List your debts and prioritise them. Use the avalanche method to pay off high-interest debt first, and the snowball method to tackle smaller debts and gain momentum. Celebrate every victory along the way, no matter how small. Remember, each payment brings you closer to financial freedom.

5. RETIREMENT SAVINGS: THE STRENGTH TRAINING OF FINANCE

Saving for retirement is similar to strength training in that it gradually increases your financial muscle. Make regular contributions to your retirement accounts. Take full advantage of any matching benefits provided by your employer. Increase your contributions whenever possible, particularly if you receive a raise or bonus. And remember to diversify your investments to reduce risk. The goal is to lay a solid financial foundation that will help you in your golden years.

6. INVESTING: THE PERSONAL TRAINER OF YOUR FINANCES 

Investing can be intimidating, but think of it like a personal trainer—it will help you achieve your goals faster. Start with basic investment accounts such as superannuation funds or retirement savings accounts. Learn about different investment options and strategies. Consider working with a financial advisor to create a personalised investment plan. The key is to start now and let the power of compound interest work in your favour.

7. FINANCIAL SELF-CARE: DON’T FORGET TO STRETCH 

Just as stretching is essential for physical fitness, so is financial self-care. Take the time to review your financial goals and progress on a regular basis. Celebrate your achievements, no matter how small. And don’t forget to reward yourself—within reason. Financial fitness is all about balance, so make sure to enjoy life along the way.

8. ACCOUNTABILITY: FIND YOUR FINANCIAL WORKOUT BUDDY

A workout buddy makes it easier to stay accountable, as does financial fitness. Share your goals with a trusted friend or family member. Join financial communities or forums to find support and motivation. Consider working with a financial coach or advisor to help you stay on track. Having someone to encourage you and hold you accountable can make all the difference. Join my monthly coaching program to stay motivated and on track with your financial goals, like a personal trainer does when you want to achieve your fitness goals.

9. KEEP LEARNING: FINANCIAL EDUCATION NEVER STOPS

The world of finance is constantly changing, and staying informed is crucial. Keep your knowledge up to date by reading books, taking courses, and following financial blogs. Consider subscribing to financial newsletters or podcasts for regular updates and tips. The more you know, the better equipped you are to make informed financial decisions. You can stay informed by subscribing to my regular podcast and newsletter – so be sure to check them out.

10. STAY FLEXIBLE: ADAPT AND ADJUST

Just like with physical fitness, your financial journey will have ups and downs. Stay flexible and be ready to adapt. Life happens—unexpected expenses, changes in income, or shifting priorities. The key is to stay focused on your goals and adjust your plan as needed. Remember, this is a marathon, not a sprint.

Congratulations, you’ve completed the Financial Fitness Bootcamp! By setting goals, creating a budget, building an emergency fund, paying off debt, saving for retirement, investing, practicing financial self-care, staying accountable, continuing your financial education, and staying flexible, you’re well on your way to financial health. Now, go ahead and achieve your financial goals—you have got this!

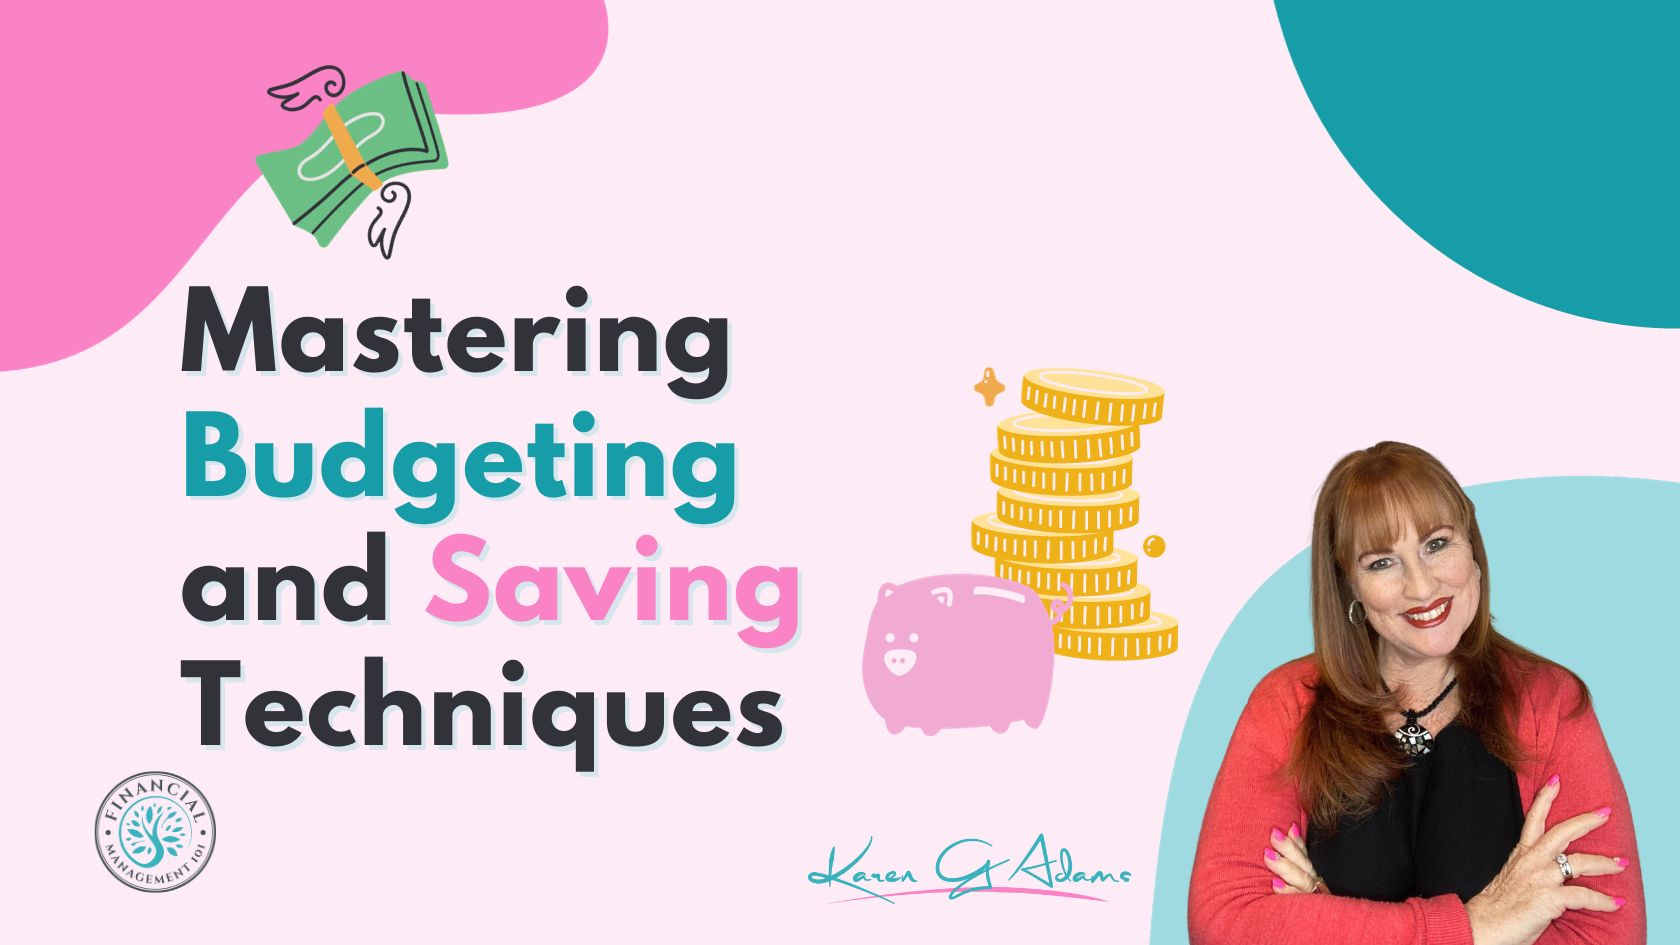
Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

Mastering Budget and Saving Techniques
Free Budgeting Spreadsheet

GRAB YOUR OWN COPY FOR FREE

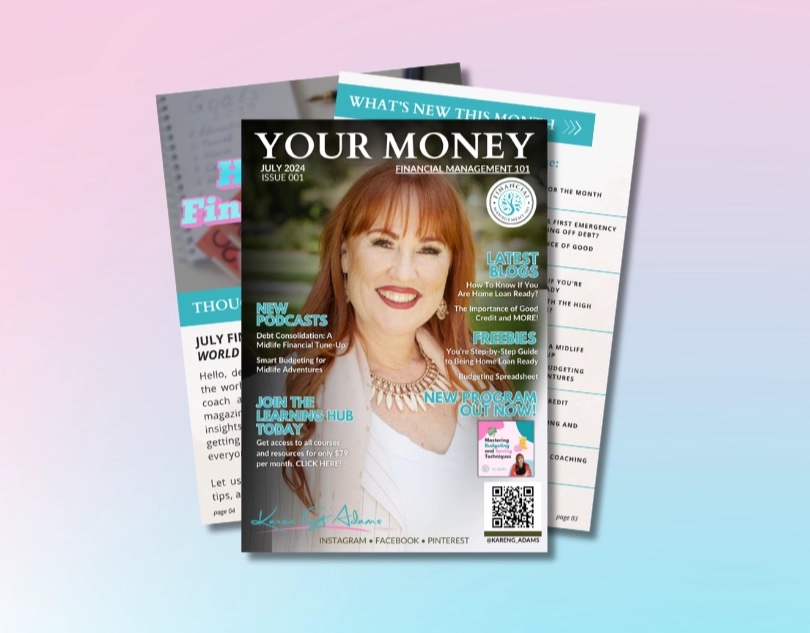
YOUR MONEY eMagazine

Are you ready to take control of your finances and secure a brighter future?

Dive into “Your Money,” the premier e-magazine by Karen G Adams, the Founder of Financial Management 101.

Subscribe for FREE!

The Great Balancing Act: Juggling Financial Goals and Family Life in Your 40s and 50s

The Great Balancing Act: Juggling Financial Goals and Family Life in Your 40s and 50s

Welcome to the circus, where you star in the world’s greatest balancing act! Between raising kids, saving for college, and planning for retirement, it’s easy to feel like you’re juggling flaming torches while riding a unicycle. Do not worry, my friend. Your financial coach is here to help you master the art of balance (with no singed brows).

1. PRIORITISE LIKE A PRO

When you’re juggling multiple financial goals, prioritisation is key. Start by listing all your financial goals—short-term, medium-term, and long-term. Then, rank them by importance and urgency. Focus on the top priorities first. For most people, this includes building an emergency fund, paying off high-interest debt, and contributing to retirement accounts. Once the essentials are covered, you can allocate funds to other goals like college savings or that dream vacation.

Use Budgeting Apps

Family Budget Meetings

Budget meetings do not have to be boring. Make them fun and engaging for the entire family. By involving the whole family, you’ll teach your kids valuable money management skills and ensure everyone is on the same page.

2. FAMILY BUDGET MEETINGS: THE FUN VERSION

Budget meetings do not have to be boring. Make them fun and engaging for the entire family. Set aside a regular time each month to review your budget, track progress towards goals, and discuss any changes. Get everyone involved. Use charts, graphs, and even stickers to make it more interactive. Do not forget the snacks; everything is better with them. By involving the whole family, you’ll teach your kids valuable money management skills and ensure everyone is on the same page.

3. COLLEGE SAVINGS: DON’T BREAK THE BANK

Saving for college can feel like a daunting task, but it doesn’t have to break the bank. Start by exploring funds, which offer tax advantages for education savings. Set up automatic contributions to make saving easier. If you’re getting a late start, don’t panic. Encourage your kids to apply for scholarships, grants, and work-study programs. And remember, there’s no shame in starting at a community college or attending a state school. The goal is to get an education without a mountain of debt.

4. RETIREMENT SAVINGS: THE LONG GAME

It can be difficult to balance college savings and retirement plans, but keep in mind that there are no retirement scholarships. Prioritise your retirement savings first. If you are falling behind, consider increasing your contributions, delaying retirement, or looking into part-time work in retirement. The key is to remain adaptable and focused on the long-term goal. And, if you end up working a little longer, consider it extra time to improve your golf game or finally finish that novel.

5. SMART SPENDING: THE ART OF SAYING NO

With kids, there’s always something new to spend money on—gadgets, sports, extracurricular activities, you name it. Learning to say no (or at least “not right now”) is essential. Teach your kids the value of money by involving them in budget decisions. Show them how saving for a big goal means making sacrifices in the short term. And lead by example. If they see you making smart spending choices, they’re more likely to follow suit.

Smart Spending

6. FAMILY FUN ON A BUDGET

Quality family time doesn’t have to come with a hefty price tag. Look for free or low-cost activities in your community. Parks, hiking trails, and local events can provide endless entertainment without breaking the bank. Get creative at home with game nights, DIY projects, or cooking together. The goal is to create memories, not rack up credit card debt.

7. SELF-CARE IS NOT SELFISH

Remember to take care of yourself amidst all the financial juggling. Self-care isn’t selfish—it’s necessary. Set aside time and money for activities that recharge your batteries, whether it’s a hobby, exercise, or a weekend getaway. A well-rested, happy you is better able to cope with the financial and emotional demands of family life. Plus, it sets a great example for your kids about the importance of self-care.

8. GET PROFESSIONAL HELP WHEN NEEDED

There is no shame in seeking professional assistance with your finances. A financial advisor and coach, like myself, can offer valuable insights, assist you in developing a comprehensive plan, and keep you on track. Look for an advisor who acts in your best interest. Sometimes an outside perspective is all you need to see the big picture and make sound decisions.

Balancing financial goals and family life is no easy task, but with a little planning, smart choices, and a healthy dose of humour, you can master the great balancing act. Now, go out and conquer that budget—your financial circus awaits!

Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

Mastering Budget and Saving Techniques
Free Budgeting Spreadsheet

MONTHLY COACHING

Take Control of Your Finances Today!

Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.