Financial Resilience: Planning for Setbacks on Your Path to Debt Freedom

Financial Resilience: Planning for Setbacks on Your Path to Debt Freedom

Achieving a debt free life is a journey filled with highs and lows. While it’s great to stay optimistic, it’s equally important to be prepared for setbacks that might knock you off your progress. Unexpected expenses, job loss, medical bills, or even just plain old burnout can throw a spanner in your plans. The key to overcoming these challenges lies in building financial resilience. In this post, we’ll explore strategies to prepare for and bounce back from setbacks, ensuring you stay on track to becoming debt-free.

1. IDENTIFY YOUR MARKETABLE SKILLS

I bang on about this one all the time, why because an emergency fund is your financial safety net. It’s the cushion that helps absorb the shock of unexpected expenses without relying on credit cards or loans. A common rule of thumb is to have three to six months’ worth of living expenses saved.

Action Step:
Start by setting aside a small, manageable amount each week or month. Even $10 a week can add up. Automate your savings to ensure consistency and resist the temptation to dip into this fund for non-emergencies.

7. OFFER VIRTUAL SERVICES OR COACHING

Relying solely on one source of income can be risky. If you lose your job or face a reduction in hours, your finances can take a significant hit. Diversifying your income through side hustles, freelance work, or passive income streams can provide a buffer against such setbacks. I mentioned in a recent blog post tips and strategies on how “Using Your Talents to Accelerate Debt Repayment”. Go check this post out HERE.

Action Step:
Identify a side hustle or freelance opportunity that aligns with your skills. Set aside dedicated time each week to develop this secondary income stream.
3. CREATE A FINANCIAL CONTINGENCY PLAN

A contingency plan outlines what you’ll do in the face of financial setbacks. It could include steps like cutting back on non-essential expenses, using savings, or temporarily taking on additional work.

Action Step:
List potential setbacks and corresponding actions you would take to mitigate their impact. Keep this plan accessible and review it regularly.

4. PRACTICE CONSCIOUS SPENDING

Conscious spending involves being aware of where your money goes and making intentional choices. By being mindful of your spending, you’re better equipped to adjust your budget when faced with financial challenges.

Action Step:
Track all your spending for a month to identify where your money is going. Create a budget that prioritises essential expenses and allocates funds towards debt repayment and savings.

5. INVEST IN INSURANCE

Insurance is a vital component of financial resilience. Health insurance, home insurance, car insurance, and even disability insurance can protect you from significant financial setbacks. While it’s an added expense, the cost of not having adequate insurance can be much higher.

Action Step:
Review your current insurance policies and assess if you have adequate coverage. If not, consider adjusting your policies or shopping around for better rates.

6. PREPARE FOR IRREGULAR EXPENSES

Irregular expenses – like car repairs, home maintenance, or annual subscriptions can disrupt your debt repayment plan if not anticipated. Preparing for these expenses can prevent the need to rely on credit.

Action Step:
Review past expenses to identify irregular costs and create a separate savings fund for them. Allocate a small amount each month to this fund.

7. DEVELOP A DEBT REPAYMENT BUFFER

Instead of putting every last dollar towards debt, consider building a small buffer in your savings or checking account. This buffer can help cover unexpected expenses without halting your debt repayment plan.

Action Step:
Determine a comfortable buffer amount (e.g., $500) and gradually build it up by allocating a portion of your income each month.

8. KEEP YOUR CREDIT IN GOOD STANDING

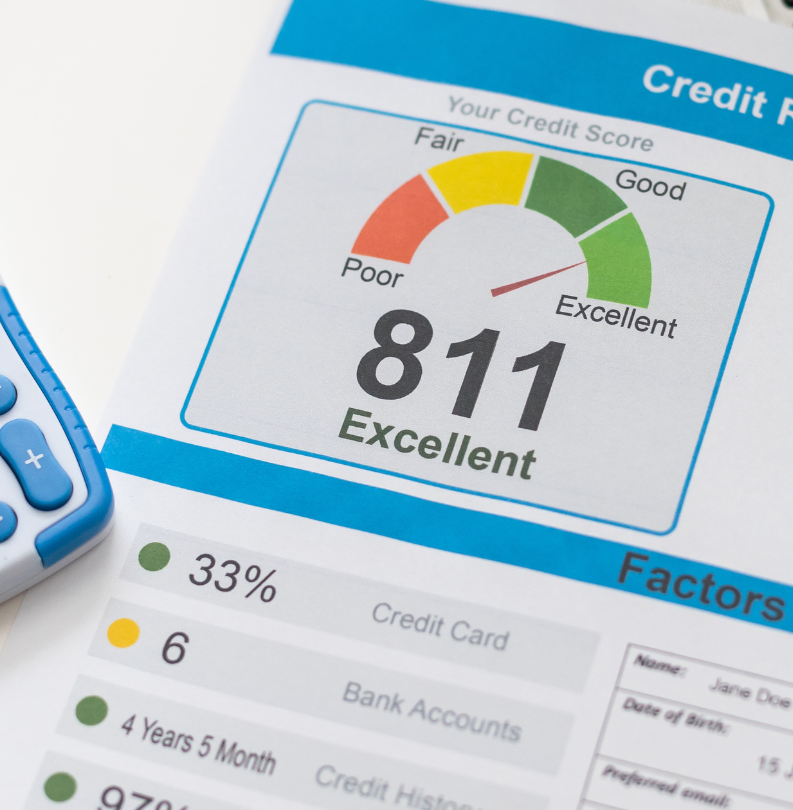
Maintaining a good credit score is crucial, even when you’re working to pay off debt. In the event of a financial emergency, having access to credit can provide a temporary solution without resorting to high-interest loans.

Action Step:
Regularly check your credit report for errors and keep credit card balances low. Make all payments on time, even if it’s just the minimum amount.
9. EMBRACE THE POWER OF NEGOTIATION

Unexpected expenses can often be negotiated or spread out. Medical bills, for instance, are notorious for being negotiable. Don’t hesitate to ask for a payment plan, a reduction in interest rates, or even a discount.

Action Step:
If faced with a large, unexpected bill, contact the service provider and enquire about payment options, discounts, or financial assistance programs.

10. FOSTER A RESILIENT MINDSET

Building financial resilience isn’t just about money—it’s also about mindset. Understand that setbacks are a part of life, and maintaining a positive outlook will help you navigate them more effectively.

Action Step:
Practice stress-management techniques such as mindfulness, meditation, or journaling. Develop a routine that helps you stay focused and calm during financial challenges.

11. BUILD A SUPPORT NETWORK

Having a support network of friends, family, or a financial advisor can provide emotional and practical support during challenging times. Surround yourself with people who understand your goals and can offer advice or encouragement.

Action Step:
Identify three people who can be part of your financial support network. Share your goals with them and ask for their support in staying accountable. 
12. PLAN FOR FUTURE SETBACKS

While it’s impossible to predict every setback, planning for potential scenarios can make them less overwhelming. Think about what could go wrong in your financial journey and devise strategies to deal with them.

Action Step:
Conduct a “financial fire drill.” Write down potential setbacks (e.g., job loss, major car repair) and create a response plan for each scenario.

13. REGULARLY REVIEW AND ADJUST YOUR FINANCIAL PLAN

Your financial situation and priorities can change over time. Regularly reviewing and adjusting your debt repayment plan ensures you stay on track and adapt to new circumstances.

Action Step:
Set a reminder to review your financial plan every quarter. Adjust your budget, debt repayment, and savings strategies based on your current situation.

CONCLUSION

Setbacks are inevitable on the path to becoming debt-free, but with the right preparation, they don’t have to derail your progress. By building financial resilience through strategic planning, conscious spending, and a positive mindset, you can bounce back stronger from any challenge. Remember, becoming debt-free is not a sprint; it’s a marathon. Stay focused, stay prepared, and keep moving forward. 
Take Control of Your Finances Today!

Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.

As your financial coach, Karen will teach you how to build financial muscle, so that you have money working to your advantage and not to your bank or financial institution’s benefit. Click here to enrol!
Mastering Budget and Saving Techniques

Are you ready to take control of your finances and start your debt-free journey?

In this empowering 30-day course, we’ll guide you through actionable steps to help you break free from debt and achieve financial stability.
Using Your Talents to Accelerate Debt Repayment

Using Your Talents to Accelerate Debt Repayment

One of the most effective ways to speed up your debt-free journey is to increase your earnings. While cutting expenses is essential, there’s only so much you can save. On the other hand, boosting your income has virtually no upper limit. And the best way to do this? By leveraging your unique skills and talents. In this post, we’ll explore creative ways to monetise what you’re already good at to generate extra income and pay down your debt faster.

1. IDENTIFY YOUR MARKETABLE SKILLS

Everyone has skills that others find valuable. These could be professional skills like writing, graphic design, or coding, or personal talents like cooking, crafting, or fitness coaching. The first step is to identify what skills you have that can be monetised.

Action Step:
Make a list of all your skills—both professional and personal. Next to each skill, brainstorm how you could offer this as a service or product to others.

2. OFFER FREELANCE OR CONSULTING SERVICES

Freelancing is a flexible way to turn your professional skills into an income stream. Whether it’s writing, graphic design, web development, or marketing. There’s a demand for almost every skill set online.

Action Step:
Create profiles on popular freelance platforms like Upwork, Fiverr, or Freelancer. Start with a competitive rate to build your portfolio and reputation. As you gain experience and positive reviews, increase your rates.

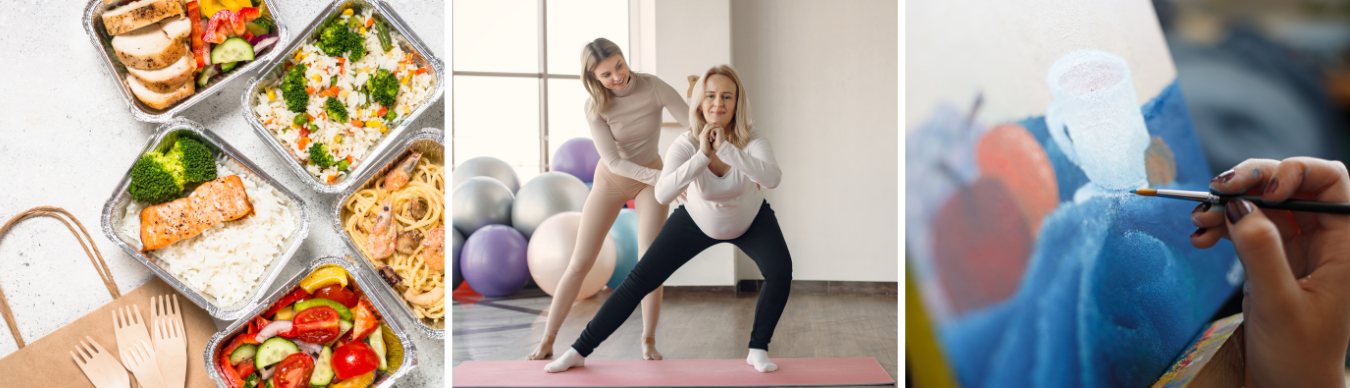
Starting a side hustle can be a great way to turn your passions into income. Offer catering services for events or meal prep for busy individuals. Host yogaclasses at local community centres or online. Create custom and commissioned artwork for clients.

3. START A SIDE-HUSTLE BASED ON YOUR PASSION

If you’re passionate about something, chances are you’re good at it—and people are willing to pay for it. This could range from tutoring, personal training, photography, or even starting a blog or YouTube channel about a niche topic you love.

Action Step:
Identify a passion you can turn into a side hustle. Research how others in the field monetize their passion, and develop a simple business plan to start.

4. TEACH WHAT YOU KNOW

If you have expertise in a particular area, consider teaching others. This could be through online courses, workshops, or even one-on-one tutoring sessions. The e-learning market is booming, and platforms like Udemy, Teachable, and Skillshare make it easier than ever to reach a global audience.

Action Step:
Outline a course or workshop you could teach based on your expertise. Create a simple curriculum and start by offering free webinars or low-cost classes to gauge interest.

5. MONETISE YOUR HOBBIES

Hobbies like photography, crafting, baking, or gardening can be turned into profitable side businesses. For instance, if you’re into photography, you could sell prints online or offer portrait sessions. If you love crafting, consider opening an Etsy shop or participating in local craft fairs.

Action Step:
Identify a hobby you could monetise. Research how others have successfully turned similar hobbies into businesses and consider starting small—like selling at a local market or online.

6. WRITE AND SELF-PUBLISH A BOOK OR AN EBOOK

If you have expertise or a story to share, consider writing a book or e-book. Platforms like Amazon Kindle Direct Publishing (KDP) make it easy to self-publish and reach a wide audience. Whether it’s a how-to guide, a cookbook, or a fiction novel, there’s a market for almost every genre.

Action Step:
Outline a book or e-book idea that leverages your knowledge or storytelling ability. Write a few chapters and seek feedback. Once ready, self-publish and promote it through social media and online communities.

7. OFFER VIRTUAL SERVICES OR COACHING

The virtual world offers endless opportunities for monetising your skills. If you’re a great communicator, consider coaching or consulting via Zoom or Skype. This could be life coaching, career coaching, language tutoring, or even virtual fitness training.

Action Step:
Choose a virtual service that aligns with your skills. Set up a simple website or social media page to promote your services. Offer a few free sessions to gather testimonials and refine your approach.

8. CREATE A MEMBERSHIP OR SUBSCRIPTION SERVICE

If you have a skill or knowledge that requires ongoing support or regular updates, consider creating a membership or subscription service. This could be a monthly subscription box for handmade goods, an exclusive online community, or a members-only blog with premium content.

Action Step:
Identify a service or product that could be offered on a subscription basis. Develop a pricing model and launch a beta version to test the market.

9. SELL DIGITAL PRODUCTS

Digital products like printables, e-books, templates, or courses have high-profit margins and low overhead costs. Once created, they can be sold repeatedly, generating passive income over time.

Action Step:
Develop a digital product related to your skill or passion. Use platforms like Etsy, or your own website to sell and promote the product.

10. PARTICIPATE IN THE GIG ECONOMY

Consider participating in the gig economy if you’re looking for flexible, quick income opportunities. Driving for Uber, delivering groceries with Instacart, or doing odd jobs with Airtasker or hipages are all options that allow you to set your schedule.

Action Step:
Sign up for a gig economy platform that aligns with your availability and interests. Use the income from these gigs specifically to pay down debt.

11. LEVERAGE YOUR SOCIAL MEDIA PRESENCE

If you have a strong social media presence or are willing to build one, you can leverage this platform to promote affiliate products, partner with brands, or even sell your products and services. Influencer marketing is a lucrative option for those who can build a dedicated following.

Action Step:
Choose a social media platform that aligns with your target audience. Start creating valuable content consistently and explore monetisation options as your following grows.

12. NETWORK AND COLLABORATE

Networking and collaborations can open up new income opportunities. Reach out to others in your field or related industries to see how you can collaborate on projects, cross-promote each other’s services, or even share clients.

Action Step:
Join professional groups or online communities related to your skill. Engage actively, offer help, and look for collaboration opportunities.

Conclusion: Stay Ahead of the Game

Leveraging your talents to create additional income streams can significantly accelerate your debt payoff journey. The key is to think creatively about how you can monetise what you already know and do well. Remember, there’s no single right way to do this—experiment with different ideas, see what works best, and scale up from there. With consistent effort and a bit of creativity, you’ll be on your way to becoming debt-free in no time.

Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

Take Control of Your Finances Today!

Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.

As your financial coach, Karen will teach you how to build financial muscle, so that you have money working to your advantage and not to your bank or financial institution’s benefit. Click here to enrol!

Are you ready to take control of your finances and start your debt-free journey?

In this empowering 30-day course, we’ll guide you through actionable steps to help you break free from debt and achieve financial stability.