The Debt-Free Mindset: How to Train Your Brain for Financial Freedom

The Debt-Free Mindset: How to Train Your Brain for Financial Freedom

Becoming debt-free isn’t just about paying off balances; it’s about reshaping your mindset to align with financial freedom. Many people get trapped in a cycle of debt because their mindset is stuck in a place of scarcity or fear. Let us look at some actionable steps for developing a debt-free mindset.

1. UNDERSTAND YOUR DEBT SITUATION

Every financial decision you make is influenced by your beliefs about money, often shaped by your experiences. Reflect on your “debt story”—the events, habits, and emotions that led you to where you are now. Write it down. Understanding your history with money is the first step to rewriting your financial future.

ACTION STEP:
Journal about your first memory of money, your feelings towards debt, and how that might have shaped your current situation.

2. REFRAME YOUR THOUGHTS ABOUT MONEY

Instead of viewing debt as a burden, see it as a challenge to overcome. Change your language from “I’m in debt” to “I am working towards financial freedom.” Positive affirmations can help you stay motivated and focused on your goal.

ACTION STEP:
Create a list of positive money affirmations, such as “I am capable of managing my finances,” and repeat them daily.
3. VISUALISE DEBT FREEDOM

Visualisation is a powerful tool. Imagine how your life will look and feel once you’re debt-free. Picture the freedom, the opportunities, and the peace of mind that comes with it. The more vivid your vision, the more motivated you’ll be to achieve it.

ACTION STEP:
Spend 5 minutes every morning visualising your debt-free life. Write down what you see and feel.

4. SURROUND YOURSELF WITH FINANCIAL POSITIVITY 

Your environment influences your mindset. If you’re surrounded by people who are also striving to be debt-free, or who have achieved it, their energy can motivate you. Join a debt-free community or follow influencers who share your financial goals.

ACTION STEP:
Join my monthly coaching program where you will feel supported and be part of a community all working towards helping you achieve your financial independence and goals. CLICK HERE for more information.

5. CHALLENGE YOUR LIMITING BELIEFS

Many of us have limiting beliefs about money—like thinking we’ll always be in debt or that financial freedom is only for the wealthy. Challenge these beliefs by seeking evidence to the contrary and reprogramming your mind with empowering thoughts.

ACTION STEP:
Write down three limiting beliefs you have about money and challenge them with factual statements or examples.

6. PRACTICE GRATITUDE FOR WHAT YOU HAVE

Shifting your focus from what you lack to what you have can create a more abundant mindset. When you’re grateful for your current resources, you’re more likely to use them wisely and attract more.

ACTION STEP:
Start a gratitude journal and list three things you’re grateful for each day, focusing on non-material aspects of your life.

7. SET REALISTIC AND ACHIEVABLE GOALS

Setting small, achievable goals can help build momentum. Instead of focusing solely on the end goal of being debt-free, set smaller milestones. Celebrate each win, no matter how small.

ACTION STEP:
Break down your debt into smaller, manageable chunks and create a reward system for achieving each milestone.
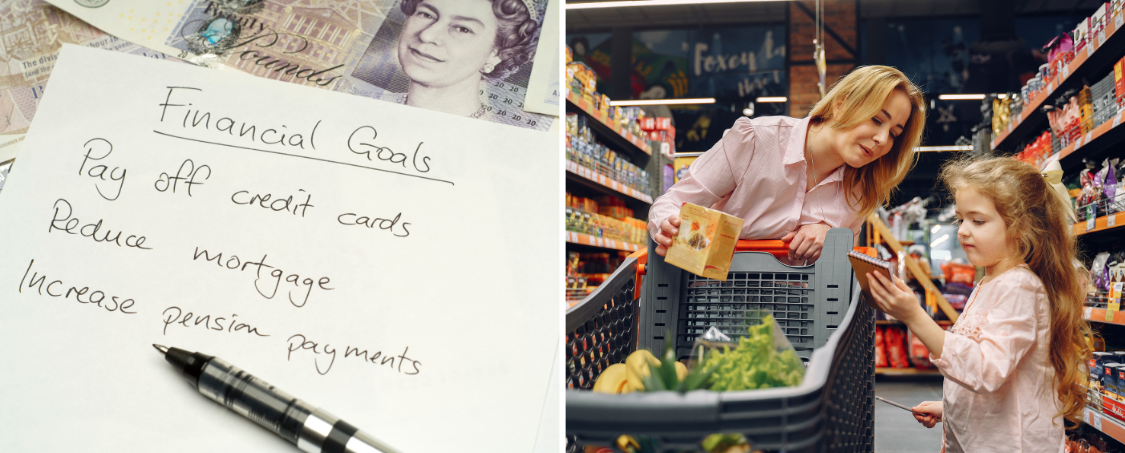
Only purchase essentials and document the impact on your finances and mindset.

8. EMBRACE MINIMALISM IN SPENDING

Adopting a minimalist approach to spending helps shift the focus from consuming to saving and investing in experiences rather than things. This mindset shift can significantly contribute to becoming debt-free.

ACTION STEP:
For one month, only purchase essentials and document the impact on your finances and mindset.

9. LEARN FROM YOUR MISTAKES WITHOUT GUILT

Everyone makes financial mistakes, but dwelling on them with guilt can keep you stuck. Instead, view them as learning opportunities. Reflect on what went wrong and how you can prevent it from happening again.

ACTION STEP:
List past financial mistakes and write down the lessons you’ve learned from each. 

10. COMMIT TO LIFELONG LEARNING ABOUT MONEY

Developing a debt-free mindset is an ongoing process. Make a commitment to continue learning about money management, investing, and wealth-building. This growth mindset will keep you motivated and informed.

ACTION STEP:
Choose one financial book or one of my online courses and programs to complete each month.
CONCLUSION

Becoming debt-free starts with transforming your mindset. By understanding your debt story, reframing your thoughts about money, and setting realistic goals, you can begin the journey towards financial freedom with a clear and positive outlook. Remember, the path to being debt-free is not just about the numbers but also about your mindset.

Take Control of Your Finances Today!

Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.
Mastering Budget and Saving Techniques
Free Budgeting Spreadsheet

GRAB YOUR OWN COPY FOR FREE

YOUR MONEY eMagazine

Are you ready to take control of your finances and secure a brighter future?

Dive into “Your Money,” the premier e-magazine by Karen G Adams, the Founder of Financial Management 101.

Subscribe for FREE!
What Happens When You Miss a Loan Payment: Avoiding the Financial Pitfalls

What Happens When You Miss a Loan Payment: Avoiding the Financial Pitfalls

Hey there, my savvy money managers!

Today, we are going over a topic that is about as fun as stepping on a Lego in the middle of the night: missing loan payments. Missing a payment on a credit card, mortgage, or personal loan can have serious consequences for your financial health. But do not worry, we will navigate these rough waters together, so by the end of this post, you will understand why you should not miss payments and how to stay on track like a financial ninja. Let’s get started!

The Domino Effect of Missing a Payment

1. CREDIT SCORE TAKES A HIT

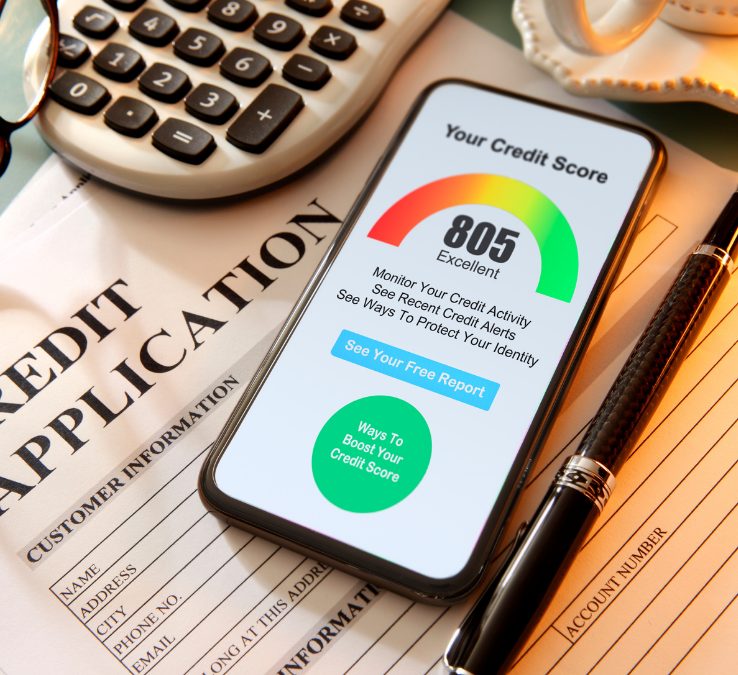
Consider your credit score to be a report card for your finances. Missing a payment is similar to failing a big test; it hurts. When you miss a payment, your lender reports it to the credit bureaus (Experian, Equifax, Veda and TransUnion), and your credit score may suffer significantly. A lower credit score means higher interest rates on future loans and credit cards, and it may even limit your ability to rent an apartment or find work. Yikes!

    2. LATE FEES AND PENALTIES

    Lenders love late fees because it is their way of saying, “We told you so!” These fees can range from mildly annoying to extremely painful. Late fees on credit cards can be up to $40. Mortgages and personal loans may have even steeper penalties. These additional costs can quickly accumulate, making it difficult to catch up.

    3. HIGHER INTEREST RATES

    If you fail to pay your credit card bill on time, you may face the dreaded annual penalty rate. This is a higher interest rate that can apply to your existing balance and future purchases. Penalty rates can soar up to 29.99%, turning your manageable debt into a mountain of despair.

    4. COLLECTION AGENCIES COME CALLING

    If you continue to miss payments, your debt may be sent to a collection agency. These people are persistent; they will call, email, and possibly even write you a letter or two. Having a debt in collections can harm your credit score even more and cause a lot of stress.

    5. FORECLOSURE AND REPOSSESSION

    Missing multiple mortgage payments can result in foreclosure, in which the lender takes back your home. Similarly, if you default on a car loan, the lender may seize your vehicle. Losing your home or car is a life-changing event that you should definitely avoid.

    The Ripple Effect on Your Life

    1. EMOTIONAL AND MENTAL STRESS

    Financial issues can be extremely stressful. Worrying about missed payments, mounting debt, and the potential loss of assets can have a negative impact on your mental health. Anxiety, depression, and insomnia are common side effects.

    2. RELATIONSHIP STRAIN

    Money problems are one of the most common causes of relationship stress. Arguments about money can strain relationships with your partner, family, and friends. Being open and working together on a plan can help mitigate these issues. 

    3. LIMITED FINANCIAL FLEXIBILITY 

    When you fall behind on your payments, you lose financial flexibility. You may have to forego saving for emergencies, retirement, and other goals. Living paycheck to paycheck becomes a harsh reality.

    How To Avoid Missing Payments Like a Pro

    1. MAKE A BUDGET AND STICK TO IT

    Yes, the B-word – budget. It might not sound glamorous, but creating a budget is the foundation of good financial health. Keep track of your income and expenses to ensure that you have enough money set aside for loan payments. There are numerous budgeting apps available that can make this process easier and even more enjoyable.

    2. SET UP AUTOMATIC PAYMENTS

    Automated payments are your best friend. They ensure that you never miss a due date, and many lenders provide this feature. Just make sure you have enough money in your account to cover the payments – you don’t want to incur overdraft fees!

    3. CREATE AN EMERGENCY FUND

    Life is unpredictable. An emergency fund serves as a financial cushion for unforeseen expenses that can disrupt your payment schedule. Aim to save three to six months’ worth of living expenses in a separate, easily accessible account.

    4. COMMUNICATE WITH YOUR LENDER

    If you think you are going to miss a payment, do not hide under the rock. Contact your lender as soon as possible. Many lenders are willing to work with you if you take proactive steps. They might offer temporary relief options like payment deferrals, reduced interest rates, or a modified payment plan.

    5. PRIORITISE YOUR DEBTS

    Not all debts are equal. High-interest debts, such as credit cards, should be your primary focus because they can quickly spiral out of control. Use the snowball or avalanche method to tackle your debts systematically.

    6. REVIEW YOUR STATEMENTS REGULARLY

    Keep track of your loan statements and bank accounts. This allows you to catch any errors or unauthorised charges early and keeps you informed of your payment due dates.

    7. IF IT SEEMS LIKE THERE’S NOT ENOUGH MONEY

    You may need to look for some extra money, like a side hustle or additional part time work— anything that you can fit into your already busy schedule to help ease the stress and pay down those debts quicker.  There are many ways you can earn a few extra dollars, so look at your creative talents and see if you can earn extra income from areas like tutoring, arts and crafts to name a few.

    Look at your creative talents and see if you can earn extra income from areas like tutoring, arts and crafts to name a few.

    A Fun Challenge: The No-Spend Week

    Here’s a fun little challenge to help you stay on track – try a no-spend week. For one week, don’t spend money on anything that isn’t a necessity. Use up what you have in the pantry, avoid eating out, and avoid online shopping. This can help you save a significant amount of money, which you can put towards your loan payments.

    Conclusion: Stay Ahead of the Game

    Missing a loan payment may feel like the end of the world, but it does not have to be. Understanding the consequences and taking proactive steps will help you avoid pitfalls and stay financially healthy. Remember, it is all about staying informed, being organised, and making sound decisions.

    So buckle up, set up those automatic payments, and keep an eye on your finances. With a little discipline and planning, you will be able to navigate your financial journey with ease in no time. And hey, if you ever need a pep talk or some financial coaching, you know where to find me. Enjoy managing your money!

    By following these suggestions, you will be well on your way to avoiding late payments and maintaining a healthy financial future. Now get out there and conquer those loan payments like the financial superstar you are!

    Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

    Mastering Budget and Saving Techniques
    Free Budgeting Spreadsheet

    GRAB YOUR OWN COPY FOR FREE

    YOUR MONEY eMagazine

    Are you ready to take control of your finances and secure a brighter future?

    Dive into “Your Money,” the premier e-magazine by Karen G Adams, the Founder of Financial Management 101.

    Subscribe for FREE!
    The Great Balancing Act: Juggling Financial Goals and Family Life in Your 40s and 50s

    The Great Balancing Act: Juggling Financial Goals and Family Life in Your 40s and 50s

    Welcome to the circus, where you star in the world’s greatest balancing act! Between raising kids, saving for college, and planning for retirement, it’s easy to feel like you’re juggling flaming torches while riding a unicycle. Do not worry, my friend. Your financial coach is here to help you master the art of balance (with no singed brows).

    1. PRIORITISE LIKE A PRO

    When you’re juggling multiple financial goals, prioritisation is key. Start by listing all your financial goals—short-term, medium-term, and long-term. Then, rank them by importance and urgency. Focus on the top priorities first. For most people, this includes building an emergency fund, paying off high-interest debt, and contributing to retirement accounts. Once the essentials are covered, you can allocate funds to other goals like college savings or that dream vacation.

    Use Budgeting Apps

    Family Budget Meetings

    Budget meetings do not have to be boring. Make them fun and engaging for the entire family. By involving the whole family, you’ll teach your kids valuable money management skills and ensure everyone is on the same page.

    2. FAMILY BUDGET MEETINGS: THE FUN VERSION

    Budget meetings do not have to be boring. Make them fun and engaging for the entire family. Set aside a regular time each month to review your budget, track progress towards goals, and discuss any changes. Get everyone involved. Use charts, graphs, and even stickers to make it more interactive. Do not forget the snacks; everything is better with them. By involving the whole family, you’ll teach your kids valuable money management skills and ensure everyone is on the same page.

    3. COLLEGE SAVINGS: DON’T BREAK THE BANK

    Saving for college can feel like a daunting task, but it doesn’t have to break the bank. Start by exploring funds, which offer tax advantages for education savings. Set up automatic contributions to make saving easier. If you’re getting a late start, don’t panic. Encourage your kids to apply for scholarships, grants, and work-study programs. And remember, there’s no shame in starting at a community college or attending a state school. The goal is to get an education without a mountain of debt.

    4. RETIREMENT SAVINGS: THE LONG GAME

    It can be difficult to balance college savings and retirement plans, but keep in mind that there are no retirement scholarships. Prioritise your retirement savings first. If you are falling behind, consider increasing your contributions, delaying retirement, or looking into part-time work in retirement. The key is to remain adaptable and focused on the long-term goal. And, if you end up working a little longer, consider it extra time to improve your golf game or finally finish that novel.

    5. SMART SPENDING: THE ART OF SAYING NO

    With kids, there’s always something new to spend money on—gadgets, sports, extracurricular activities, you name it. Learning to say no (or at least “not right now”) is essential. Teach your kids the value of money by involving them in budget decisions. Show them how saving for a big goal means making sacrifices in the short term. And lead by example. If they see you making smart spending choices, they’re more likely to follow suit.

    Smart Spending

    6. FAMILY FUN ON A BUDGET

    Quality family time doesn’t have to come with a hefty price tag. Look for free or low-cost activities in your community. Parks, hiking trails, and local events can provide endless entertainment without breaking the bank. Get creative at home with game nights, DIY projects, or cooking together. The goal is to create memories, not rack up credit card debt.

    7. SELF-CARE IS NOT SELFISH

    Remember to take care of yourself amidst all the financial juggling. Self-care isn’t selfish—it’s necessary. Set aside time and money for activities that recharge your batteries, whether it’s a hobby, exercise, or a weekend getaway. A well-rested, happy you is better able to cope with the financial and emotional demands of family life. Plus, it sets a great example for your kids about the importance of self-care.

    8. GET PROFESSIONAL HELP WHEN NEEDED

    There is no shame in seeking professional assistance with your finances. A financial advisor and coach, like myself, can offer valuable insights, assist you in developing a comprehensive plan, and keep you on track. Look for an advisor who acts in your best interest. Sometimes an outside perspective is all you need to see the big picture and make sound decisions.

    Balancing financial goals and family life is no easy task, but with a little planning, smart choices, and a healthy dose of humour, you can master the great balancing act. Now, go out and conquer that budget—your financial circus awaits!

    Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

    Mastering Budget and Saving Techniques
    Free Budgeting Spreadsheet

    MONTHLY COACHING

    Take Control of Your Finances Today!

    Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.
    Midlife Crisis or Opportunity? Finding Financial Zen in Your 40s and 50s

    Midlife Crisis or Opportunity? Finding Financial Zen in Your 40s and 50s

    So, if you listened to and read my previous blog and podcast, you would have heard some advice for those in the financial sandwich age 35 to 50.
    So, let us talk about people in their mid-40s and 50s. This is the stage where you are old enough to have gained some wisdom but young enough to wonder if you have made all the right financial decisions. If you feel like you are on the verge of a midlife financial crisis, take a deep breath. Your trusted financial coach is here to turn that crisis into an opportunity, with a dash of humour to keep things light.

    1. THE MIDLIFE FINANCIAL CHECK-UP

    Do not skip your financial checkup any more than you would your annual physical. Take a hard look at your finances. Review your budget, debt, savings, and investments. Are you on track to achieve your goals? If not, it is time to make adjustments. Think of it as a financial tune-up. You would not drive your car with the check engine light on indefinitely, so do not neglect your finances.

    2. DEBT DETOX: TIME TO CLEAN THE HOUSE

    Debt is like that guest who overstays their welcome. It’s time to show it the door. Start by listing all your debts: credit cards, student loans, car loans, and any other liabilities. Tackle high-interest de bt first using the avalanche method or start small with the snowball method. Whatever strategy you choose, the key is to be consistent in your payments. Celebrate small victories along the way—each paid-off debt is a step closer to financial freedom.

    3. REVIEW YOUR RETIREMENT GOALS

    By now, you probably have some retirement savings, but is it enough? Use retirement calculators to estimate how much you’ll need. Adjust your contributions if necessary. Do not be concerned if you are falling behind. If you are over 50, consider maxing out your retirement accounts or looking into catch-up contributions. And remember that every little bit helps. Even small increases in your contributions can make a big difference over time.

    4. HEALTH SAVINGS ACCOUNT (HSA): THE TRIPLE TAX BENEFIT

    If you have a high-deductible health plan, an HSA is your new best friend. Contributions are tax deductible, funds grow tax-free, and withdrawals for qualified medical expenses are tax-free. It’s like a financial hat trick. Plus, after age 65, you can use HSA funds for non-medical expenses without a penalty (though you’ll pay regular income tax). It’s a win-win.

    5. SIDE HUSTLES: NOT JUST FOR MILLENIALS

    Who says side hustles are only for the younger generation? Your 40s and 50s are ideal times to investigate new income streams. A side hustle, whether it is freelancing, consulting, or turning a hobby into a business, can help you earn more money while also providing you with creative opportunities. It is also an excellent way to test the waters if you are thinking about changing careers or staying active in retirement.

    6. PROTECT YOUR ASSETS: INSURANCE AND ESTATE PLANNING

    Life insurance, disability insurance, and long-term care insurance may not be the most exciting topics, but they are critical for safeguarding your assets and ensuring your family’s financial stability. Review your policies and make sure they align with your current needs. And don’t forget estate planning. A will, power of attorney, and healthcare directive are all important documents that can save your loved ones a lot of stress and heartache.

    Estate Planning ensures that your assets are distributed according to your wishes. Without a plan, state laws will dictate the distribution, which may not align with your desires.

    7. INVEST IN EXPERIENCES, NOT JUST THINGS

    As you get older, you realise that memories are worth more than material possessions. Prioritise spending on experiences that will improve your life. Travel, hobbies, and quality time with loved ones all contribute to your happiness and well-being. Plus, they don’t depreciate like that fancy car or gadget.

    8. KEEP LEARNING: FINANCIAL EDUCATION NEVER STOPS

    The financial world is constantly changing, and staying informed is essential. Keep your financial knowledge up to date by reading books, attending seminars, or taking online courses. Consider working with a financial advisor to help you navigate complex decisions and stay on track. Remember: knowledge is power, and it is never too late to learn something new.

    Take these suggestions with a sense of humour and an open mind. Your 40s and 50s can be a time of financial growth and opportunity. So, dust off those financial cobwebs, make a plan, and move forward with confidence. You’ve got this!

    Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

    Mastering Budget and Saving Techniques
    Free Budgeting Spreadsheet

    MONTHLY COACHING

    Take Control of Your Finances Today!

    Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.
    Understanding How Money Works

    Understanding How Money Works

    Remember when we thought adults knew everything about money? Joke’s on us! But it’s never too late to learn. Here’s your crash course in Money 101.

    Why Understanding Money Matters

    Understanding money is essential because it influences every aspect of your life. From buying groceries to planning for retirement, money management skills can mean the difference between financial stability and stress. By learning how money works, you can make informed decisions that lead to a more secure and fulfilling life.

    THE BASICS OF BUDGETING

    Budgeting is the cornerstone of good money management. It helps you track income and expenses, ensuring you live within your means and save for future goals.

    Action Steps:

    1. Track Your Income and Expenses: Write down all sources of income and all your monthly expenses. Use a spreadsheet, a budgeting app, or even a notebook to keep track.
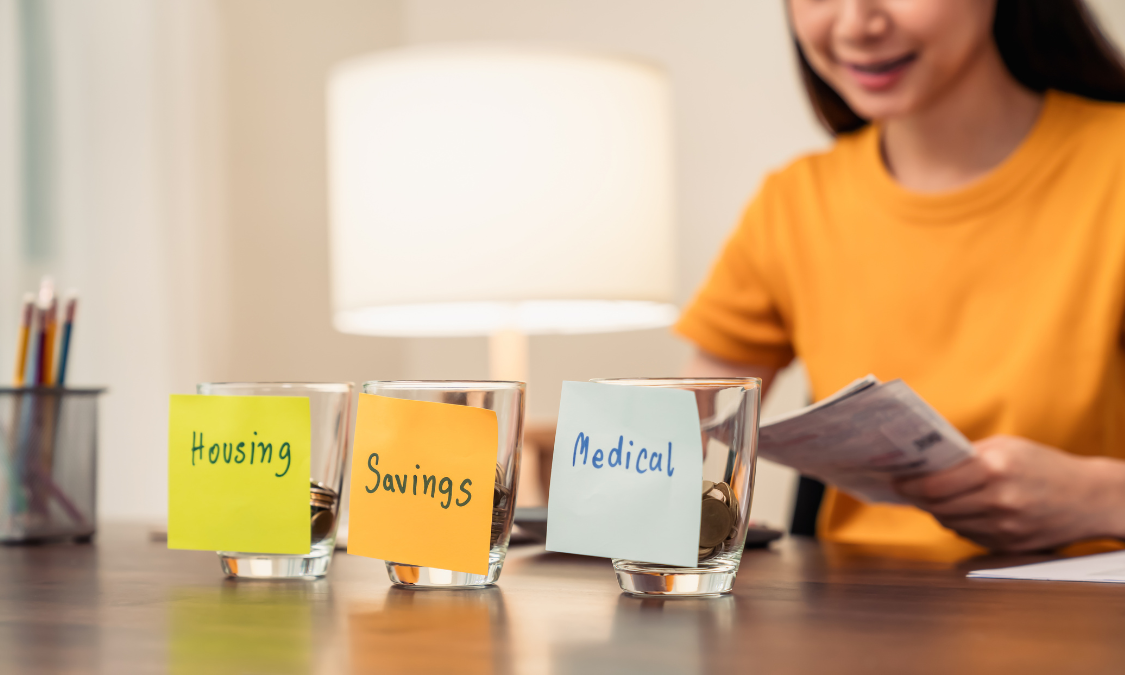
    2. Categorise Your Spending: Divide your expenses into categories like housing, groceries, transportation, entertainment, and savings. This helps you see where your money is going.
    3. Set Budget Limits: Based on your income, set limits for each spending category. Be realistic but disciplined.
    4. Review and Adjust: At the end of each month, review your budget to see if you stayed within your limits. Adjust your budget as needed to better align with your financial goals.

    Budgeting helps you control your spending, avoid debt, and save money. It’s the foundation of financial health.

    Use Budgeting Apps

    Categorise Your Spending

    Categorise your expenses to see where your money is going.

    THE POWER OF COMPOUND INTEREST

    Compound interest is a magical concept that can either work for or against you. Understanding it is crucial for managing both savings and debt.

    Action Steps:

    1. Learn the Formula: Compound interest is calculated using the formula A = P(1 + r/n)^(nt), where A is the amount of money accumulated, P is the principal amount, r is the annual interest rate, n is the number of times interest is compounded per year, and t is the time the money is invested for.
    2. Start Early: The earlier you start saving or investing, the more time compound interest has to work its magic. Even small contributions can grow significantly over time.
    3. Pay-off High-Interest Debts: Compound interest can also work against you when it comes to debt. High-interest debt, like credit card debt, can quickly spiral out of control due to compound interest. Focus on paying it off as soon as possible.

    By harnessing the power of compound interest, you can grow your savings and investments exponentially over time.

    CREDIT SCORES AND THEIR IMPORTANCE

    Your credit score is a numerical representation of your creditworthiness. It affects your ability to get loans, credit cards, and even rent an apartment. Maintaining a good credit score is essential for financial stability.

    Action Steps:

    1. Understand the Factors: Your credit score is influenced by payment history (35%), amounts owed (30%), length of credit history (15%), new credit (10%), and credit mix (10%).
    2. Pay Bills on Time: Late payments can significantly damage your credit score. Set up automatic payments or reminders to ensure you never miss a due date.
    3. Keep Balances Low: Aim to use less than 30% of your available credit. High credit utilisation can negatively impact your score.
    4. Check Your Credit Report: Regularly review your credit report for errors and discrepancies. You can get a free report annually from each of the three major credit bureaus.

    A good credit score opens doors to better loan terms, lower interest rates, and more financial opportunities.

    Investing is a powerful way to grow your wealth over time.

    The longer your money is invested, the more time it has to grow through compound interest, where your earnings generate additional earnings.

    Long-term investments are assets that you plan to hold for an extended period, usually more than three years. They’re meant to grow in value over time and achieve your long-term financial goals, like retirement or for your child’s education. 

    THE BASICS OF INVESTING

    Investing is a powerful way to grow your wealth over time. By putting your money to work in various assets, you can build a substantial financial cushion for the future.

    Action Steps:

    1. Understand Different Types of Investments: Common investment types include stocks, bonds, mutual funds, and real estate. Each has its own risk and return profile.
    2. Start with Retirement Accounts: Take advantage of tax-advantaged retirement accounts like superannuation funds, 401(k)s and IRAs. These accounts allow your investments to grow tax-free or tax-deferred.
    3. Diversify Your Portfolio: Don’t put all your eggs in one basket. Spread your investments across different asset classes to reduce risk.
    4. Learn About Risk and Return: Higher potential returns usually come with higher risk. Understand your risk tolerance and invest accordingly.

    Investing wisely can help you build wealth and achieve long-term financial goals, such as retirement or buying a home.

    EMERGENCY FUND: YOUR SAFETY FINANCIAL NET

    An emergency fund is a crucial component of financial stability. It’s a savings buffer that protects you from unexpected expenses and financial shocks.

    Action Steps:

    1. Determine Your Target Amount: Aim to save 3-6 months’ worth of living expenses. This amount provides a cushion for emergencies like job loss, medical bills, or major repairs.
    2. Start Small and Build Up: If saving several months’ worth of expenses seems daunting, start with a smaller goal, like $1,000. Gradually increase your savings over time.
    3. Keep It Accessible: Store your emergency fund in a high-yield savings account where it can earn interest but still be easily accessible in case of emergency.
    4. Use It Wisely: Only dip into your emergency fund for true emergencies. Avoid the temptation to use it for non-essential expenses.

    Having an emergency fund gives you peace of mind and financial security, knowing you’re prepared for unexpected situations.

    Smart Spending

    SMART SPENDING: GETTING MORE BANG FOR YOUR BUCK

    Being a smart spender means making informed choices that maximise the value of your money. It’s about prioritising needs over wants and finding ways to save on everyday expenses.

    Action Steps:

    1. Differentiate Needs and Wants: Before making a purchase, ask yourself if it’s a necessity or a luxury. Prioritise spending on essentials and limit discretionary spending.
    2. Shop Smart: Look for sales, use coupons, and compare prices before making purchases. Online tools and apps can help you find the best deals.
    3. Plan Your Purchases: Avoid impulse buying by planning your purchases in advance. Make a shopping list and stick to it.
    4. Buy Quality, Not Quantity: Sometimes, spending a bit more on a high-quality item can save you money in the long run, as it lasts longer and performs better.

    Smart spending helps you get the most value out of your money and prevents unnecessary debt.

    THE IMPORTANCE OF FINANCIAL GOALS

    Setting financial goals gives you direction and motivation. It helps you stay focused on what’s important and measure your progress over time.

    Action Steps:

    1. Identify Your Goals: Think about what you want to achieve financially. This could include saving for a down payment on a house, paying off debt, or building an emergency fund.
    2. Set Specific and Measurable Goals: Make your goals specific and measurable. For example, “Save $10,000 for a down payment within two years” is more effective than “Save money.”
    3. Create a Plan: Outline the steps you need to take to achieve your goals. Break them down into manageable tasks and set deadlines.
    4. Review and Adjust: Regularly review your progress and adjust your plan as needed. Life changes, and your financial goals might need to change too.

    Having clear financial goals keeps you motivated and provides a roadmap for achieving financial success.

    Conclusion

    Understanding how money works is crucial for achieving financial stability and success. By mastering the basics of budgeting, leveraging compound interest, maintaining a good credit score, investing wisely, building an emergency fund, spending smartly, and setting financial goals, you can take control of your finances and create a secure future. It’s never too late to start learning and making positive changes. So, dive in, educate yourself, and watch as your financial confidence and stability grow. You’ve got this!

    Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

    Mastering Budget and Saving Techniques
    Free Budgeting Spreadsheet

    MONTHLY COACHING

    Take Control of Your Finances Today!

    Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.