Year-End Financial Check-Up: 7 Key Steps to Close 2024 with Confidence

Year-End Financial Check-Up: 7 Key Steps to Close 2024 with Confidence

As the year wraps up, it’s time to give your finances a little TLC and prepare to start the new year strong! Think of this as your yearly financial check-up, a simple routine that sets you up for a financially fit future. Here are seven straightforward steps to help you close out 2024 with confidence.

1. Review Your Budget with Fresh Eyes

December is perfect for giving your budget a quick health check. Ask yourself:

    • Did you stick to your budget most months?
    • Are there categories where you regularly overspent?

If you find that certain areas of your budget were tough to stick to, don’t worry; you’re not alone! Make notes on what worked and what didn’t, and consider if those categories need adjusting. Next year’s budget will feel easier to manage if it aligns more closely with your actual spending patterns.

2. Evaluate Your Financial Goals for 2024

Reflect on the goals you set at the beginning of 2024. Did you aim to build an emergency fund, pay off a certain amount of debt, or save for a big purchase? Take a moment to celebrate any wins, big or small, you’ve earned it! If there were goals you couldn’t reach, try to pinpoint what might have held you back. Life happens, and sometimes, adjustments are necessary. Use these reflections to set realistic goals for 2025 that build on the progress you’ve made.
Audit Your Subscriptions and Recurring Expenses

3. Audit Your Subscriptions and Recurring Expenses

Subscriptions can sneak up on you! Take a look at all the services you’re subscribed to, streaming platforms, gym memberships, software, meal kits and decide if they’re still worth the monthly or annual fee. Ask yourself:

    • Do you use each service enough to justify the cost?
    • Are there better deals or bundles that could help you save?

Canceling or downgrading services you no longer use can free up cash you can redirect toward your savings or debt goals.

4. Set a Holiday Spending Plan

The holiday season can be a big budget-buster if you’re not careful. This December, approach holiday spending with a clear plan:

    • Set a total holiday budget and stick to it.
    • Focus on meaningful gifts within your budget and avoid last-minute splurges.
    • Consider experiences instead of material items, they often make more memorable gifts and can be cost-effective.

You’ll thank yourself in January when your credit card bills aren’t sky-high!

5. Check-in On Your Emergency Fund


Your emergency fund is your financial safety net, and December is a great time to assess its status. Ideally, you want enough to cover three to six months’ worth of essential expenses.

If your fund has been depleted due to unexpected expenses this year, make a plan to rebuild it. If it’s in good shape, well done!

Consider adding a little extra, even if it’s just a small amount each month, it’s always better to be prepared.
You want enough to cover three to six months’ worth of essential expenses on your emergency fund

5. Update Your Financial Goals for 2025

End the year by setting some intentional goals for 2025. These don’t have to be massive changes; small, achievable goals can have a big impact on your financial future. A few ideas:

    • Set a target for increasing your savings rate, even if it’s by a modest amount.
    • Commit to paying down a certain percentage of your debt.
    • Plan to invest in education or skills that could lead to higher income opportunities.

Whatever your financial goals, write them down and keep them visible. By starting now, you’ll be well-prepared to tackle them come January.
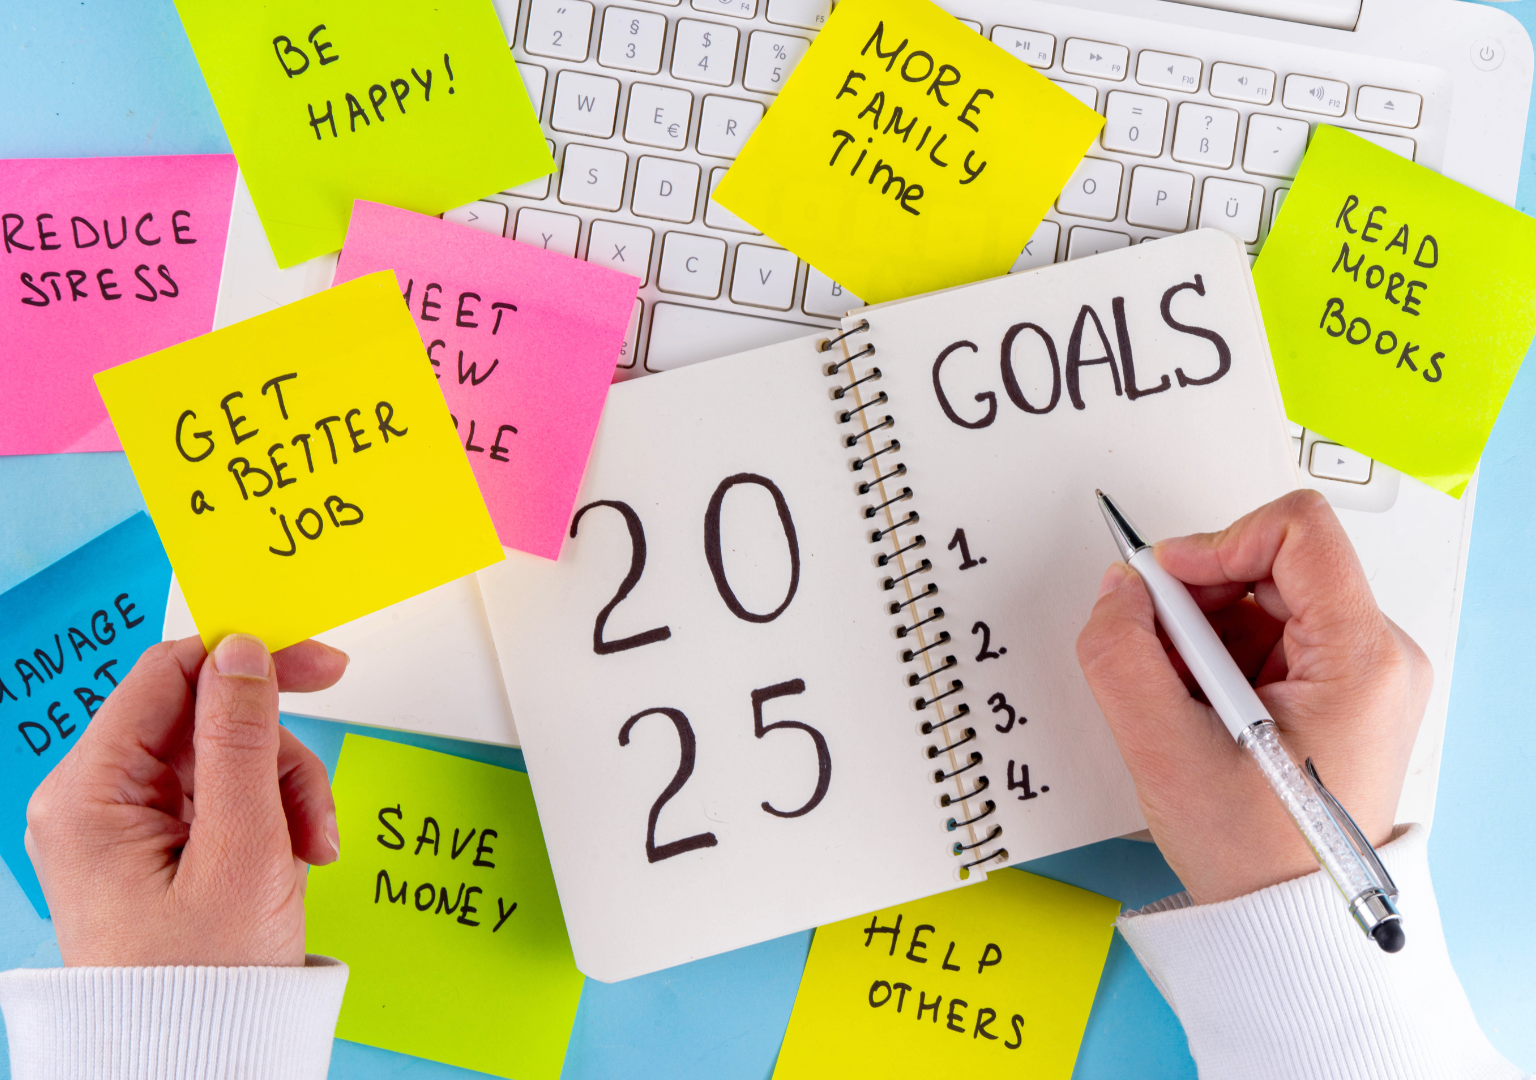
End the year by setting some intentional goals for 2025.

Final Thoughts

Closing out the year with a financial check-up is a powerful way to put yourself in the driver’s seat for 2025. These six steps are simple but effective and give you a clear view of your financial health. Here’s to closing out 2024 strong and stepping into 2025 with confidence!

Are you ready to make 2025 your breakthrough year?

MASTER YOUR MONEY is for YOU if you are tired of financial stress and ready to transform your relationship with money. Whether you’re managing a family, building your career, or chasing your dreams, this is your chance to gain the clarity, confidence, and habits you need to thrive.

This is more than a mindset shift—it’s a transformational program that puts you on the path to lasting financial success! ? Click the button below to book a call with Karen to see if this program is right for you!
Mastering Budget and Saving Techniques
Reflect, Review, and Refresh: A Guide to Assessing Your Finances Before 2025

Reflect, Review, and Refresh: A Guide to Assessing Your Finances Before 2025

As the year draws to a close, it’s natural to think about what’s next. But before you dive into new resolutions, let’s take a step back and look at your 2024 finances. Reflecting on what worked (and what didn’t) helps you move forward with clarity and confidence. Here’s a simple guide to reviewing your finances so you can start 2025 refreshed and ready to go.

1. Celebrate Your Wins

Before you jump into what needs improving, take a moment to celebrate your financial wins. Did you manage to save more than expected? Finally pay off a credit card? Stick to a new budget? Acknowledging your achievements, no matter how small, gives you a sense of progress and keeps you motivated.

Make a list of all the positive changes you’ve made or financial goals you’ve met this year. Reflecting on what you’ve achieved will give you a boost of confidence as you prepare for your next steps.

2. Identify Areas for Improvement

Once you’ve celebrated, it’s time to take an honest look at where you could improve. Ask yourself questions like:

    • Were there any unexpected expenses that threw off your budget?
    • Did you struggle to stick to any specific financial goals?
    • Are there areas where you overspent?

This reflection isn’t about criticising yourself, it’s about understanding where things may have gone off track. Knowing where you struggled will help you set realistic goals for next year and find ways to tackle those challenges head-on.

3. Review Your Debt and Savings Process

Your debt and savings are two major pillars of financial health. Look at where you stand with each:

    • Debt: How much debt have you paid down? Did you reach any of your debt reduction targets?
    • Savings: How is your emergency fund? Are you on track with your retirement savings or other savings goals?

If you didn’t reach your targets, that’s okay. Use this information to adjust for next year. Maybe you’ll aim to contribute a bit more to your debt payments or bump up your savings rate. Small changes can have a big impact over time, so don’t feel pressured to overhaul everything at once.

4. Assess Your Spending Habits

Sometimes, our spending habits change without us even noticing. Take a look at your spending patterns over the past few months. Are there categories where you consistently overspend, like dining out, online shopping, or subscriptions?

This review can reveal where your budget could use a little tweaking. By identifying your personal spending triggers, you can plan ahead and avoid overspending in the future. It’s all about aligning your spending with your priorities and making sure your budget works for you, not the other way around. 

Assess Your Spending Habits in the Past Year

5. Update Your Financial Goals for 2025

Based on your review, set fresh goals for 2025. Remember to keep your goals specific and realistic. Here are a few examples to get you started:

    • Build an emergency fund with three months’ worth of expenses by the end of the year.
    • Pay off one credit card or reduce your debt by a specific amount.
    • Save for a family vacation or a big purchase, like a car or home improvement project.

Whatever goals you choose, make sure they’re meaningful to you. When your goals reflect what you truly value, you’re more likely to stay committed.

6. Adjust Your Budget to Reflect New Priorities

A new year often brings new priorities. After reflecting on your 2024 finances, update your budget to reflect any changes in your income, expenses, or financial goals. This might mean increasing your savings contributions, adjusting debt payments, or cutting back in certain areas to make room for new expenses.

Remember, your budget is a tool, it’s there to serve you. Make adjustments that help you live comfortably within your means while still working toward your goals.

7. Setup a New System for Regular Check-ins

One of the best ways to stay on track financially is to check in regularly. Whether it’s a monthly review or a weekly “money date,” commit to a consistent routine where you:

    • Review your spending and savings.
    • Track your progress toward goals.
    • Adjust your budget as needed.

Regular check-ins make it easier to catch any issues early and keep your goals top of mind. Plus, they help you stay accountable and give you the chance to celebrate progress each step of the way.

Avoid Adding New Debt

Final Thoughts

Reflecting on your financial journey from the past year can give you valuable insights and help you start 2025 with confidence. By assessing where you are now, you’re giving yourself the power to make informed decisions and set realistic, meaningful goals. Here’s to wrapping up 2024 on a positive note and building a prosperous year ahead!

Are you ready to to build wealth without sacrificing the things you love? Do want to break free from limiting beliefs like “I’m bad with money” or “There’s never enough”?

MASTER YOUR MONEY is for YOU if you are tired of financial stress and ready to transform your relationship with money. Whether you’re managing a family, building your career, or chasing your dreams, this is your chance to gain the clarity, confidence, and habits you need to thrive.

This is more than a mindset shift—it’s a transformational program that puts you on the path to lasting financial success! ? Click the button below to book a call with Karen to see if this program is right for you!
Mastering Budget and Saving Techniques
Debt Detox: Tips for Paying Down Holiday Debt and Starting the New Year Strong

Debt Detox: Tips for Paying Down Holiday Debt and Starting the New Year Strong

The holidays are a season of joy, but they can also come with a hefty price tag. If you’ve spent a bit more than planned, don’t stress! January is the perfect time to tackle that holiday debt and set yourself up for a fresh financial start. Here’s a simple guide to help you detox your debt and enter the new year feeling financially strong.

1. Assess Your Total Holiday Debt

Start by getting a clear picture of what you owe. List all your holiday-related expenses, from credit card balances to any financing or store credit used for gifts, travel, or holiday activities. Knowing your total debt helps you avoid surprises and gives you a clear starting point.

Jot down each debt’s balance, interest rate, and minimum payment. This way, you’ll be prepared to choose the best strategy for paying it off efficiently.

Assess Your Total Holiday Debt

2. Choose a Debt Repayment Strategy

Once you know what you’re dealing with, pick a strategy that works for you. Here are two popular options:

      • The Snowball Method: Start by paying off your smallest debt first. Once it’s cleared, add that amount to the next smallest debt. This method builds momentum, as paying off smaller debts quickly can feel motivating.
      • The Avalanche Method: Start with the debt that has the highest interest rate, saving you more money in the long run. Once you clear it, move to the next highest interest rate.

Both methods work well; it just depends on what motivates you more – quick wins or long-term savings.

3. Cut Back (Temporarily) to Boost Repayments

To pay down holiday debt faster, look for small, temporary cutbacks in your budget. This could be as simple as cutting down on dining out, skipping a few subscription services, or holding off on new purchases for a month or two. Every bit you save can go toward chipping away at your debt.

Even a few small changes can make a big difference over time. For example, redirecting $50 a week toward debt could mean paying off $200 extra per month, speeding up your progress considerably.

4. Avoid Adding New Debt

While you’re focusing on paying down holiday debt, try to avoid taking on new debt. This might mean holding off on big purchases or saying no to smaller “treat yourself” items for now. The goal is to keep your focus on reducing what you owe so that you’re starting the new year in a stronger financial position.

It’s all about setting boundaries. Give yourself permission to pause on non-essential spending, knowing you’ll get back to it once you’re in a more comfortable spot with your debt.

Avoid Adding New Debt

5. Consider a Balance Transfer or Consolidation Loan

If your holiday debt is spread across multiple high-interest credit cards, look into options for consolidating or transferring the balance. A balance transfer card with a 0% introductory offer can give you a breather, allowing you to pay down the principal without additional interest for a limited time.

Alternatively, a low-interest personal loan can help you consolidate multiple debts into one manageable monthly payment. Just be sure to read the fine print and choose an option with favorable terms that genuinely help your situation.

6. Look for Extra Income Opportunities

Bringing in a little extra cash can speed up your debt payoff. You might consider picking up a side hustle, selling unused items around the house, or offering freelance services if you have skills others can use. Even a small boost in income can help you make extra payments and reduce your debt faster.

Use any additional income exclusively for debt payments until you’re in a more comfortable place financially. It’s a short-term effort with long-term benefits!

7. Set New Financial Goals to Stay Motivated

While paying down holiday debt is the priority, it’s important to stay focused on your broader financial goals. Once your debt is more manageable, shift your efforts toward building savings, contributing to your emergency fund, or working on other long-term goals.

Set one or two financial goals for the year, like “Build a $1,000 emergency fund by June” or “Pay down $2,000 in debt by year-end.” Having these goals can keep you motivated and give you something to look forward to once the holiday debt is under control.

Start Today for a Better Tomorrow!

Holiday debt doesn’t have to weigh you down for long. With a focused approach and small adjustments, you can knock out that debt and start the new year with confidence. Remember, every little effort counts, and you’ll feel empowered as you watch your debt shrink. Here’s to a fresh financial start and a strong, debt-free 2025!

Are you ready to take control of your finances and start your debt-free journey? In this empowering 30-day course, we’ll guide you through actionable steps to help you break free from debt and achieve financial stability. Join the Debt-Free Journey Challenge today!

Mastering Budget and Saving Techniques
Why It’s Time to Get Your Money Sorted

Why It’s Time to Get Your Money Sorted

It’s time to get real about your finances. Maybe you’ve been putting it off, hoping that things would magically improve, or that a sudden windfall might solve your problems. But deep down, you know that waiting won’t make things better. If you’re tired of feeling stressed about money, uncertain about your future, or like you’re not in control, then it’s time to take action.

Sorting out your finances is the best gift you can give yourself and your family. It might feel overwhelming at first, but with the right approach, you can take back control of your money, create a more stable financial future, and finally find the peace of mind that you deserve. So, let’s dive into why and how you should get your money sorted right now.

Why It’s Time To Get Your Money Sorted

1. Regain Control and Reduce Stress

Financial stress can impact every aspect of your life. It’s hard to sleep when you’re worried about how to pay your bills. It’s tough to enjoy your weekends when you’re constantly thinking about mounting debt or unexpected expenses. Money worries can even strain relationships and affect your overall mental health.

But imagine if you knew exactly where every dollar was going and felt confident about your financial decisions. Getting your money sorted means creating a budget that works, setting up a savings plan, and having a strategy for paying down debt. The peace of mind that comes from knowing your finances are under control is truly life-changing.

2. Achieve Your Financial Goals

Whether it’s saving for a house, planning a dream vacation, or simply building an emergency fund, financial goals are what keep us motivated. But without a clear plan, it’s easy for these goals to remain just that—dreams.

By getting your money sorted, you’ll be able to create a roadmap that takes you from where you are now to where you want to be. It’s not just about cutting back on lattes; it’s about setting realistic goals, tracking your progress, and making adjustments as needed. With a solid financial plan in place, those dreams start to feel within reach.

Don’t let your dream vacation remain to be “in your dreams.” Get your money sorted and achieve your financial goals one at a time!

3. Prepare for Life’s Uncertainties

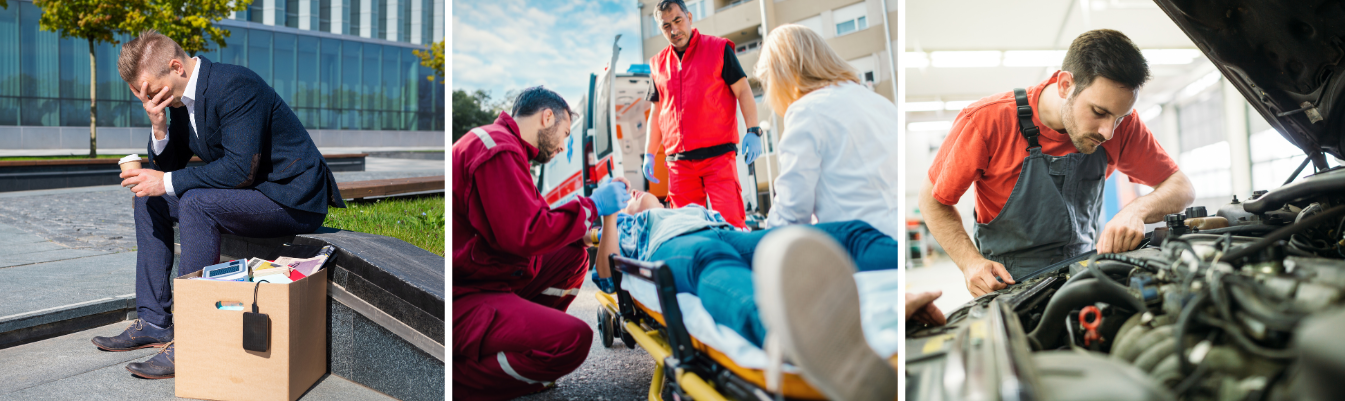
Life has a way of throwing curveballs when you least expect them – job loss, medical emergencies, car repairs, you name it. Without a financial safety net, these unexpected events can send you spiraling into debt and financial uncertainty.

Building an emergency fund and establishing good money habits now means that you’ll be prepared when life doesn’t go according to plan. It’s about creating a buffer that protects you and your family when things get tough, so you don’t have to rely on credit cards or loans to get through a rough patch.

Life has a way of throwing curveballs when you least expect them - job loss, medical emergencies, car repairs, you name it.

4. Break the Cycle of Living Paycheck to Paycheck

Are you constantly counting down the days until your next paycheck? You’re not alone. Millions of people find themselves in a cycle of living paycheck to paycheck, with little to no savings and the constant pressure of making ends meet.

Sorting out your finances is the first step toward breaking this cycle. By understanding where your money goes each month and making intentional changes, you can start to build a cushion between paychecks. It’s not just about earning more; it’s about managing what you already have in a way that creates breathing room and financial stability.

How To Get Your Money Sorted

Now that you know why it’s so important to get your money sorted, let’s talk about how you can do it. The process might seem intimidating at first, but with a few simple steps, you can take control of your finances and start seeing progress.

1. Start With a Financial Snapshot

Before you can make improvements, you need to know where you stand. Start by creating a financial snapshot. Write down your income, expenses, debts, and savings. Be honest with yourself—this is your starting point. Understanding your current situation will help you identify areas where you need to make changes.

2. Create a Budget That Works for You

Budgeting isn’t about depriving yourself; it’s about making sure that your money is working toward the things that matter most to you. List out all of your monthly expenses, including fixed costs like rent or mortgage payments, utilities, and groceries, as well as discretionary spending like dining out or entertainment.

From there, set limits for each category based on your income and financial goals. The key is to find a balance that allows you to cover your needs, save for the future, and enjoy a few treats along the way. A budget should be flexible enough to adapt to your lifestyle but firm enough to keep you on track.

3. Build an Emergency Fund

Life is unpredictable, and an emergency fund is your financial safety net. Aim to save at least three to six months’ worth of living expenses in a separate account that’s easy to access but not too tempting to dip into. Start small—$1,000 is a great initial goal—and then work toward building up that cushion over time.

Having this fund in place will prevent you from resorting to high-interest debt when unexpected expenses arise, giving you peace of mind knowing that you have a financial backup plan.

4. Tackle Your Debt Strategically

Debt can feel like a heavy weight dragging you down, but it doesn’t have to be that way. List out all of your debts, including the interest rates and minimum payments. Focus on paying down high-interest debts first while making minimum payments on the others.

Once you’ve knocked out those high-interest debts, redirect those payments toward your remaining debts. This method, known as the debt avalanche, helps you save on interest and pay off your debts faster. Alternatively, if you find it more motivating, you can use the debt snowball method, starting with the smallest balances first for quick wins.

5. Automate Savings and Bills

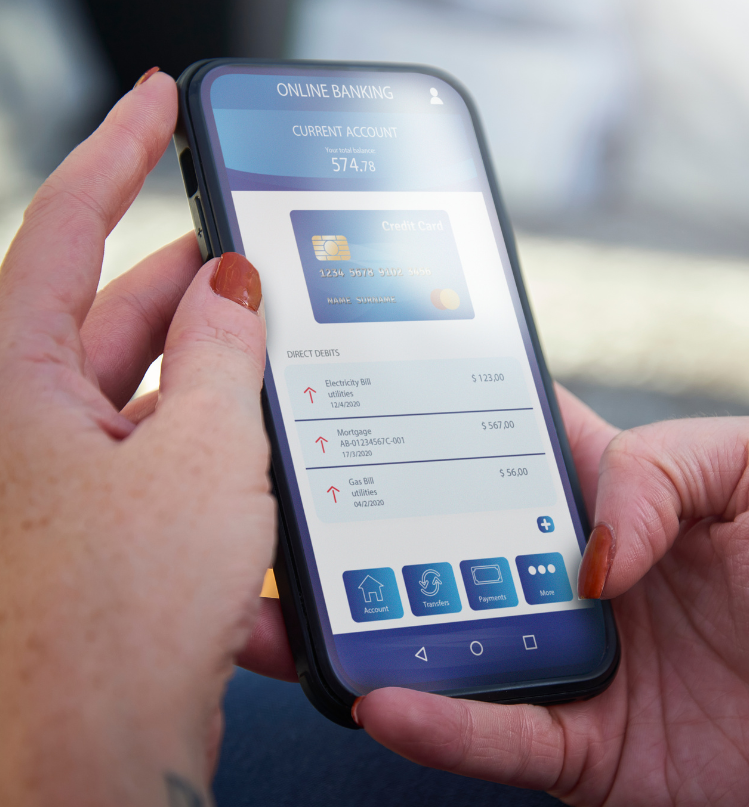
The less time you spend managing your money, the easier it is to stick to your plan. Set up automatic transfers to your savings account each month, and automate your bill payments to avoid late fees and missed payments. This way, you’re prioritizing savings before you even have a chance to spend, making it easier to reach your goals.

Automate Payments and Savings

6. Review and Adjust Regularly

Your financial situation will change over time, so it’s important to review your budget, goals, and progress regularly. Set aside time each month to go over your finances, adjust your budget if necessary, and make sure you’re on track with your goals.

This monthly check-in will keep you accountable and help you catch any issues before they become bigger problems. It’s a simple habit that can make a huge difference in your long-term success.

7. Consider Working With a Financial Coach

Sometimes, having an expert in your corner makes all the difference. A financial coach can provide personalized advice, help you navigate complex situations, and keep you accountable as you work toward your goals. With a coach’s guidance, you’ll be better equipped to make smart financial decisions, overcome challenges, and stay motivated on your journey.

Start Today for a Better Tomorrow!

It’s time to take control of your financial future. Getting your money sorted may seem like a big task, but remember, you don’t have to do it all at once. Start with small steps, focus on progress rather than perfection, and don’t be afraid to ask for help when you need it.

By taking action today, you’re investing in a future where money is a source of confidence, not stress. A future where you can enjoy life without worrying about every dollar. So, what are you waiting for? It’s time to get your money sorted and take that first step toward financial freedom.

Are you ready to take control of your money? Mastering Budgeting and Saving Techniques is a program designed to empower you to understand the importance of both budgeting and saving. 

We will explore and work through mindset shifts to empower and equip you with the tools necessary for a stress free life. This is a hands-on program with me guiding you on how to budget, track and look at managing your money like a pro.

Mastering Budget and Saving Techniques
Using Your Talents to Accelerate Debt Repayment

Using Your Talents to Accelerate Debt Repayment

One of the most effective ways to speed up your debt-free journey is to increase your earnings. While cutting expenses is essential, there’s only so much you can save. On the other hand, boosting your income has virtually no upper limit. And the best way to do this? By leveraging your unique skills and talents. In this post, we’ll explore creative ways to monetise what you’re already good at to generate extra income and pay down your debt faster.

1. IDENTIFY YOUR MARKETABLE SKILLS

Everyone has skills that others find valuable. These could be professional skills like writing, graphic design, or coding, or personal talents like cooking, crafting, or fitness coaching. The first step is to identify what skills you have that can be monetised.

Action Step:
Make a list of all your skills—both professional and personal. Next to each skill, brainstorm how you could offer this as a service or product to others.

2. OFFER FREELANCE OR CONSULTING SERVICES

Freelancing is a flexible way to turn your professional skills into an income stream. Whether it’s writing, graphic design, web development, or marketing. There’s a demand for almost every skill set online.

Action Step:
Create profiles on popular freelance platforms like Upwork, Fiverr, or Freelancer. Start with a competitive rate to build your portfolio and reputation. As you gain experience and positive reviews, increase your rates.

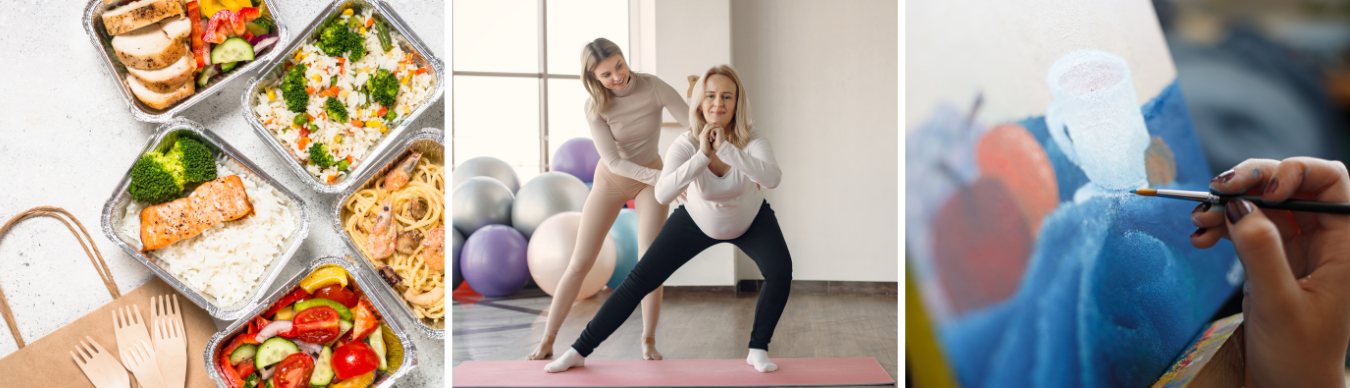
Starting a side hustle can be a great way to turn your passions into income. Offer catering services for events or meal prep for busy individuals. Host yogaclasses at local community centres or online. Create custom and commissioned artwork for clients.

3. START A SIDE-HUSTLE BASED ON YOUR PASSION

If you’re passionate about something, chances are you’re good at it—and people are willing to pay for it. This could range from tutoring, personal training, photography, or even starting a blog or YouTube channel about a niche topic you love.

Action Step:
Identify a passion you can turn into a side hustle. Research how others in the field monetize their passion, and develop a simple business plan to start.

4. TEACH WHAT YOU KNOW

If you have expertise in a particular area, consider teaching others. This could be through online courses, workshops, or even one-on-one tutoring sessions. The e-learning market is booming, and platforms like Udemy, Teachable, and Skillshare make it easier than ever to reach a global audience.

Action Step:
Outline a course or workshop you could teach based on your expertise. Create a simple curriculum and start by offering free webinars or low-cost classes to gauge interest.

5. MONETISE YOUR HOBBIES

Hobbies like photography, crafting, baking, or gardening can be turned into profitable side businesses. For instance, if you’re into photography, you could sell prints online or offer portrait sessions. If you love crafting, consider opening an Etsy shop or participating in local craft fairs.

Action Step:
Identify a hobby you could monetise. Research how others have successfully turned similar hobbies into businesses and consider starting small—like selling at a local market or online.

6. WRITE AND SELF-PUBLISH A BOOK OR AN EBOOK

If you have expertise or a story to share, consider writing a book or e-book. Platforms like Amazon Kindle Direct Publishing (KDP) make it easy to self-publish and reach a wide audience. Whether it’s a how-to guide, a cookbook, or a fiction novel, there’s a market for almost every genre.

Action Step:
Outline a book or e-book idea that leverages your knowledge or storytelling ability. Write a few chapters and seek feedback. Once ready, self-publish and promote it through social media and online communities.

7. OFFER VIRTUAL SERVICES OR COACHING

The virtual world offers endless opportunities for monetising your skills. If you’re a great communicator, consider coaching or consulting via Zoom or Skype. This could be life coaching, career coaching, language tutoring, or even virtual fitness training.

Action Step:
Choose a virtual service that aligns with your skills. Set up a simple website or social media page to promote your services. Offer a few free sessions to gather testimonials and refine your approach.

8. CREATE A MEMBERSHIP OR SUBSCRIPTION SERVICE

If you have a skill or knowledge that requires ongoing support or regular updates, consider creating a membership or subscription service. This could be a monthly subscription box for handmade goods, an exclusive online community, or a members-only blog with premium content.

Action Step:
Identify a service or product that could be offered on a subscription basis. Develop a pricing model and launch a beta version to test the market.

9. SELL DIGITAL PRODUCTS

Digital products like printables, e-books, templates, or courses have high-profit margins and low overhead costs. Once created, they can be sold repeatedly, generating passive income over time.

Action Step:
Develop a digital product related to your skill or passion. Use platforms like Etsy, or your own website to sell and promote the product.

10. PARTICIPATE IN THE GIG ECONOMY

Consider participating in the gig economy if you’re looking for flexible, quick income opportunities. Driving for Uber, delivering groceries with Instacart, or doing odd jobs with Airtasker or hipages are all options that allow you to set your schedule.

Action Step:
Sign up for a gig economy platform that aligns with your availability and interests. Use the income from these gigs specifically to pay down debt.

11. LEVERAGE YOUR SOCIAL MEDIA PRESENCE

If you have a strong social media presence or are willing to build one, you can leverage this platform to promote affiliate products, partner with brands, or even sell your products and services. Influencer marketing is a lucrative option for those who can build a dedicated following.

Action Step:
Choose a social media platform that aligns with your target audience. Start creating valuable content consistently and explore monetisation options as your following grows.

12. NETWORK AND COLLABORATE

Networking and collaborations can open up new income opportunities. Reach out to others in your field or related industries to see how you can collaborate on projects, cross-promote each other’s services, or even share clients.

Action Step:
Join professional groups or online communities related to your skill. Engage actively, offer help, and look for collaboration opportunities.

Conclusion: Stay Ahead of the Game

Leveraging your talents to create additional income streams can significantly accelerate your debt payoff journey. The key is to think creatively about how you can monetise what you already know and do well. Remember, there’s no single right way to do this—experiment with different ideas, see what works best, and scale up from there. With consistent effort and a bit of creativity, you’ll be on your way to becoming debt-free in no time.

Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

Take Control of Your Finances Today!

Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.

As your financial coach, Karen will teach you how to build financial muscle, so that you have money working to your advantage and not to your bank or financial institution’s benefit. Click here to enrol!

Are you ready to take control of your finances and start your debt-free journey?

In this empowering 30-day course, we’ll guide you through actionable steps to help you break free from debt and achieve financial stability.