Oct 10, 2018 | Financial Management 101
What Is Financial Muscle!
A little while ago someone said to me what’s this thing you keep talking about financial muscle – it doesn’t make any sense. That’s probably because I’ve coined the phase “building financial muscle”. So here’s snapshot of what it means to have financial muscle!
So financial muscle is about building strength in your finances and it’s also about building mental stamina, as well as, ensuring your money is working for you and not for some credit company or banking institutions benefit.
It means that in a time of emergency you can pull on money reserves to get you out of a bind.
Having financial muscle is about taking the worry out of unexpected things that can go wrong and often do.
Financial muscle is also about knowing you’ve got this covered – you’ve money behind you and that’s giving you greater peace of mind.
It means you can enjoy more out of life without any added financial stress and worry.
I believe we all want the same things out of life.
We all want prosperity & happiness.
We want to live a life free from stress.
And we want to live a full life – filled with many adventures and the freedom to do what we choose.
The problem I see it is that today people are being burdened down with a massive amount of stress in their life.
Some – if not a lot – of the stress is caused by financial issues.
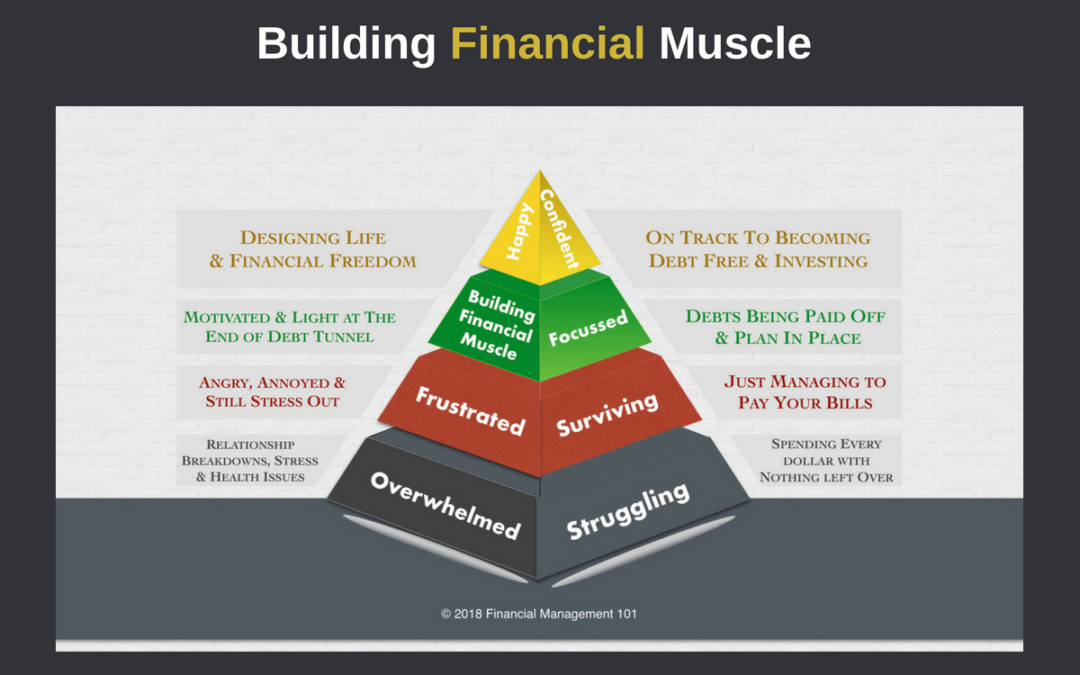
If you take a look again at this diagram you’ll see that when you don’t have financial muscle – it means you don’t have money working to your advantage.
If this is the case then you’re probably struggling and feeling very overwhelmed.
When this occurs it usually means you’re either spending everything you earn with nothing much left over.
Your relationships are probably suffering and you’re stressed out and if you’re not careful your health will start to suffer.
If you’re not quite at the bottom but feeling like you’re just surviving – by managing to pay your bills. I’m guessing you’re frustrated and possibly feeling angry and annoyed, no doubt still stressed out that your money isn’t working the way you want it to be.
In a recent study done by the Australian Psychology Society’s stress and wellbeing survey – financial issues continue to be the number 1 stress for people.
Today, there is not just one income earner but two in most households.
Families in general have more money coming in today than previous generations – and on the surface, things look really great.
However, we know there are more divorces today than ever before and the average family is looking a lot different now than from a few years ago.
When did we decide that we would give up so much of our core values in order to have the material things that give us the appearance of living a happier fulfilled life but in reality are not!
People are now slowly starting to question things like is it worth really getting into so much debt and buying stuff to impress people that we don’t even like? The onset of this is causing them to suffer in the process.
People are looking for options and want the best out of life without sacrificing their core values and principles.
You see…
“It’s not how much money we earn. It’s our ability to manage our money that can make the difference”!
Regardless of where you might be right now – invest some time into obtaining more financial knowledge that will lead to you making better decisions about your money and life.
This is the first thing you can do to start learning how to build financial muscle.
The second way you can build financial muscle is investing in yourself.
Investing in your belief that you can do it, while earning how to pay yourself first.
You pay yourself first by putting away every pay day a minimum of 10% into an account that you can not touch or access easily with the swipe of an ATM card.
This account should be one that doesn’t have any ongoing monthly fees and gives you the ability to automatically transfer at payday the minimum 10% directly into this account.
Having this on autopilot means you don’t have the think about transferring money and it just gets done.
You’re not going to miss this amount and before you know it you will have built up a sizeable amount of money that can now be used for investing and growing you money further.
Stick to the minimum of 10% until all bad debts like credit cards etc are paid off. Once you’re in a position then look to increase this to 15%.
This is how you build financial muscle.
Did you know that 80% of people are managing their money out of sheer habit with no real understanding why their doing things a certain way.
So often following or listening to someone who is not that knowledgeable in financial matters. Or following “the crowd mentality and subscribing to clever marketing tactics by advertisers” both can be dangerous if you’re not sure what you’re doing.
Managing money requires know-how and understanding on whether its actually good for your own situation. You see we all have different comfort areas and risk tolerances. So check with your financial adviser before embarking on any new investment opportunities to see if they fit your personal investment style.
Research has shown that when people get a handle on their money they end up making making smarter, healthier financial decisions that enable them to live with less stress.
Making changes in this area can be difficult for some than others – and it does require courage and commitment.
But unless people decide to make some major changes, there will be a very difficult future that lies ahead for them.
Obtaining financial education is one thing – having an awesome mindset is another and both go hand in hand for you to achieve a stress free life.
When you start building financial muscle you will find yourself at the top of this diagram. Feeling happy and confident that you are on track to becoming debt free, maybe looking at investment options and overall designing your life the way you want it.
Building financial muscle is about understanding how money works to your advantage so that in the end you can live a financially stress free life.
I hope you now have a better understanding what “Building Financial Muscle” is all about so you can create a stress free life for you and your family.
Until next time…. here’s to you building financial muscle.
Oct 10, 2018 | Podcast
Hi and welcome to podcast episode 003
In this episode I’m going to be sharing how stress maybe shortening your life and why it’s never been more important to get your money in order today.
Stress takes a huge toll on us not only emotionally and physcially but in how we’re living our life. I know myself that when I get stressed my body aches, my patience gets tested and my family suffers a little as they’re not getting the best of me.
In the episode learn how to become better equipped to deal with stress related symptoms so you can improve the way you handle your stress.
SUBSCRIBE to hear more tips and information on areas relating to financial and mindset and leave a comment on what areas of your life stresses you out the most.
Here are the resources mentioned in this episode:
Right-click here and save as to download this episode to your computer.
Oct 10, 2018 | Podcast
Hi there, in this episode I’m is going to be talking to you about the psychology of money, which is basically how your thoughts and views about money and what you possibly heard when growing up has shaped the way you manage your money today.
In one way or another depending who taught you about money – this has shaped the way you manage it today whether you are experiencing financial stress or have money behind you and living a stress free life
I want you to think about the answer to this question…….who was your role model or who did you learn your money management skills from while growing up?
You see a lot of people find dealing with money stressful and very overwhelming. I believe it’s because they don’t understand some of the basic principals to having money work to their advantage. Instead using debt as a way to get ahead but it’s seeing them fall further behind.
There is no doubt that knowledge is power and having good money habits and beliefs about money can see individuals and families enjoy more of the good stuff in life.
Like….being happier. Less stressed. More overall confidence in their life and healthier because they’re not stressed out about money.
So take a listen to see how what your belief is around money.
SUBSCRIBE to hear more tips and information on areas relating to financial and mindset and leave a comment on some of the money sayings you heard growing up.
Here are the resources mentioned in this episode:
Right-click here and save as to download this episode to your computer.