Year-End Financial Check-Up: 7 Key Steps to Close 2024 with Confidence

Year-End Financial Check-Up: 7 Key Steps to Close 2024 with Confidence

As the year wraps up, it’s time to give your finances a little TLC and prepare to start the new year strong! Think of this as your yearly financial check-up, a simple routine that sets you up for a financially fit future. Here are seven straightforward steps to help you close out 2024 with confidence.

1. Review Your Budget with Fresh Eyes

December is perfect for giving your budget a quick health check. Ask yourself:

    • Did you stick to your budget most months?
    • Are there categories where you regularly overspent?

If you find that certain areas of your budget were tough to stick to, don’t worry; you’re not alone! Make notes on what worked and what didn’t, and consider if those categories need adjusting. Next year’s budget will feel easier to manage if it aligns more closely with your actual spending patterns.

2. Evaluate Your Financial Goals for 2024

Reflect on the goals you set at the beginning of 2024. Did you aim to build an emergency fund, pay off a certain amount of debt, or save for a big purchase? Take a moment to celebrate any wins, big or small, you’ve earned it! If there were goals you couldn’t reach, try to pinpoint what might have held you back. Life happens, and sometimes, adjustments are necessary. Use these reflections to set realistic goals for 2025 that build on the progress you’ve made.
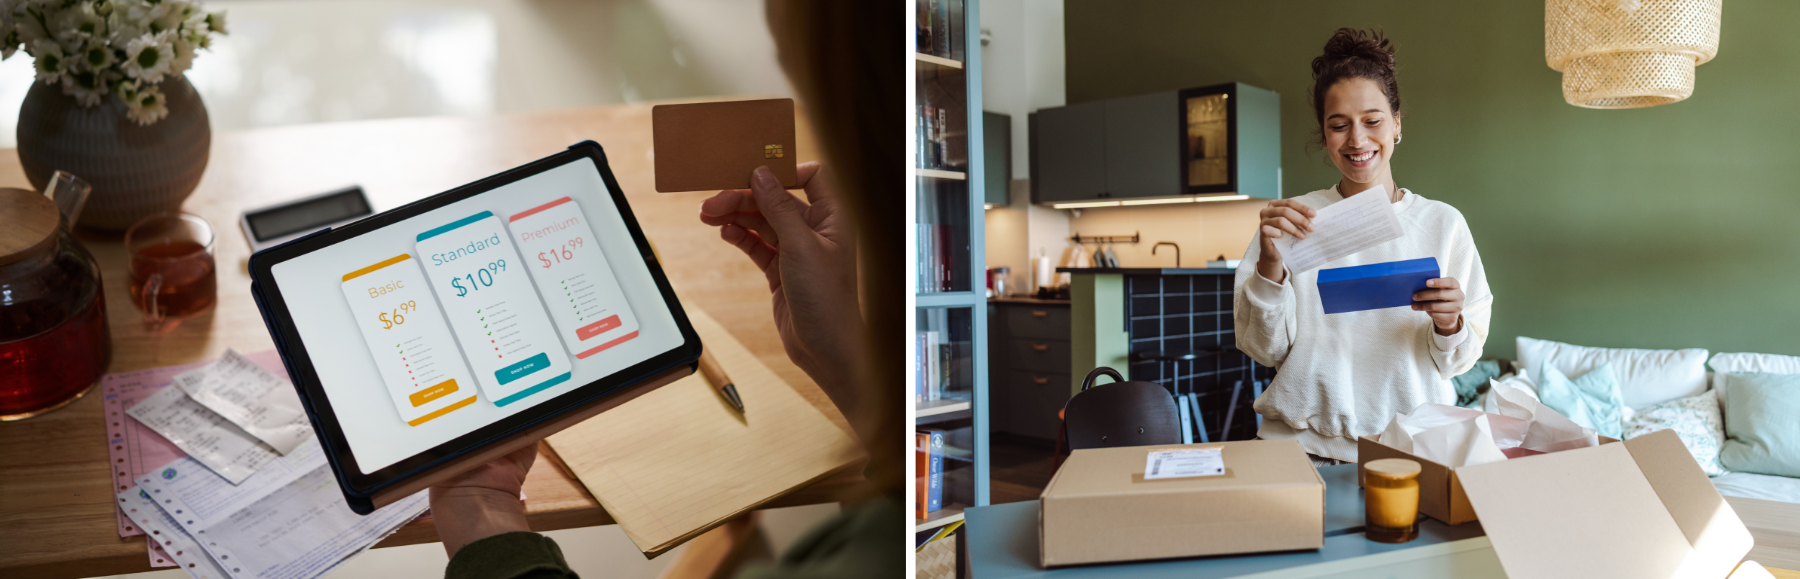
Audit Your Subscriptions and Recurring Expenses

3. Audit Your Subscriptions and Recurring Expenses

Subscriptions can sneak up on you! Take a look at all the services you’re subscribed to, streaming platforms, gym memberships, software, meal kits and decide if they’re still worth the monthly or annual fee. Ask yourself:

    • Do you use each service enough to justify the cost?
    • Are there better deals or bundles that could help you save?

Canceling or downgrading services you no longer use can free up cash you can redirect toward your savings or debt goals.

4. Set a Holiday Spending Plan

The holiday season can be a big budget-buster if you’re not careful. This December, approach holiday spending with a clear plan:

    • Set a total holiday budget and stick to it.
    • Focus on meaningful gifts within your budget and avoid last-minute splurges.
    • Consider experiences instead of material items, they often make more memorable gifts and can be cost-effective.

You’ll thank yourself in January when your credit card bills aren’t sky-high!

5. Check-in On Your Emergency Fund


Your emergency fund is your financial safety net, and December is a great time to assess its status. Ideally, you want enough to cover three to six months’ worth of essential expenses.

If your fund has been depleted due to unexpected expenses this year, make a plan to rebuild it. If it’s in good shape, well done!

Consider adding a little extra, even if it’s just a small amount each month, it’s always better to be prepared.
You want enough to cover three to six months’ worth of essential expenses on your emergency fund

5. Update Your Financial Goals for 2025

End the year by setting some intentional goals for 2025. These don’t have to be massive changes; small, achievable goals can have a big impact on your financial future. A few ideas:

    • Set a target for increasing your savings rate, even if it’s by a modest amount.
    • Commit to paying down a certain percentage of your debt.
    • Plan to invest in education or skills that could lead to higher income opportunities.

Whatever your financial goals, write them down and keep them visible. By starting now, you’ll be well-prepared to tackle them come January.
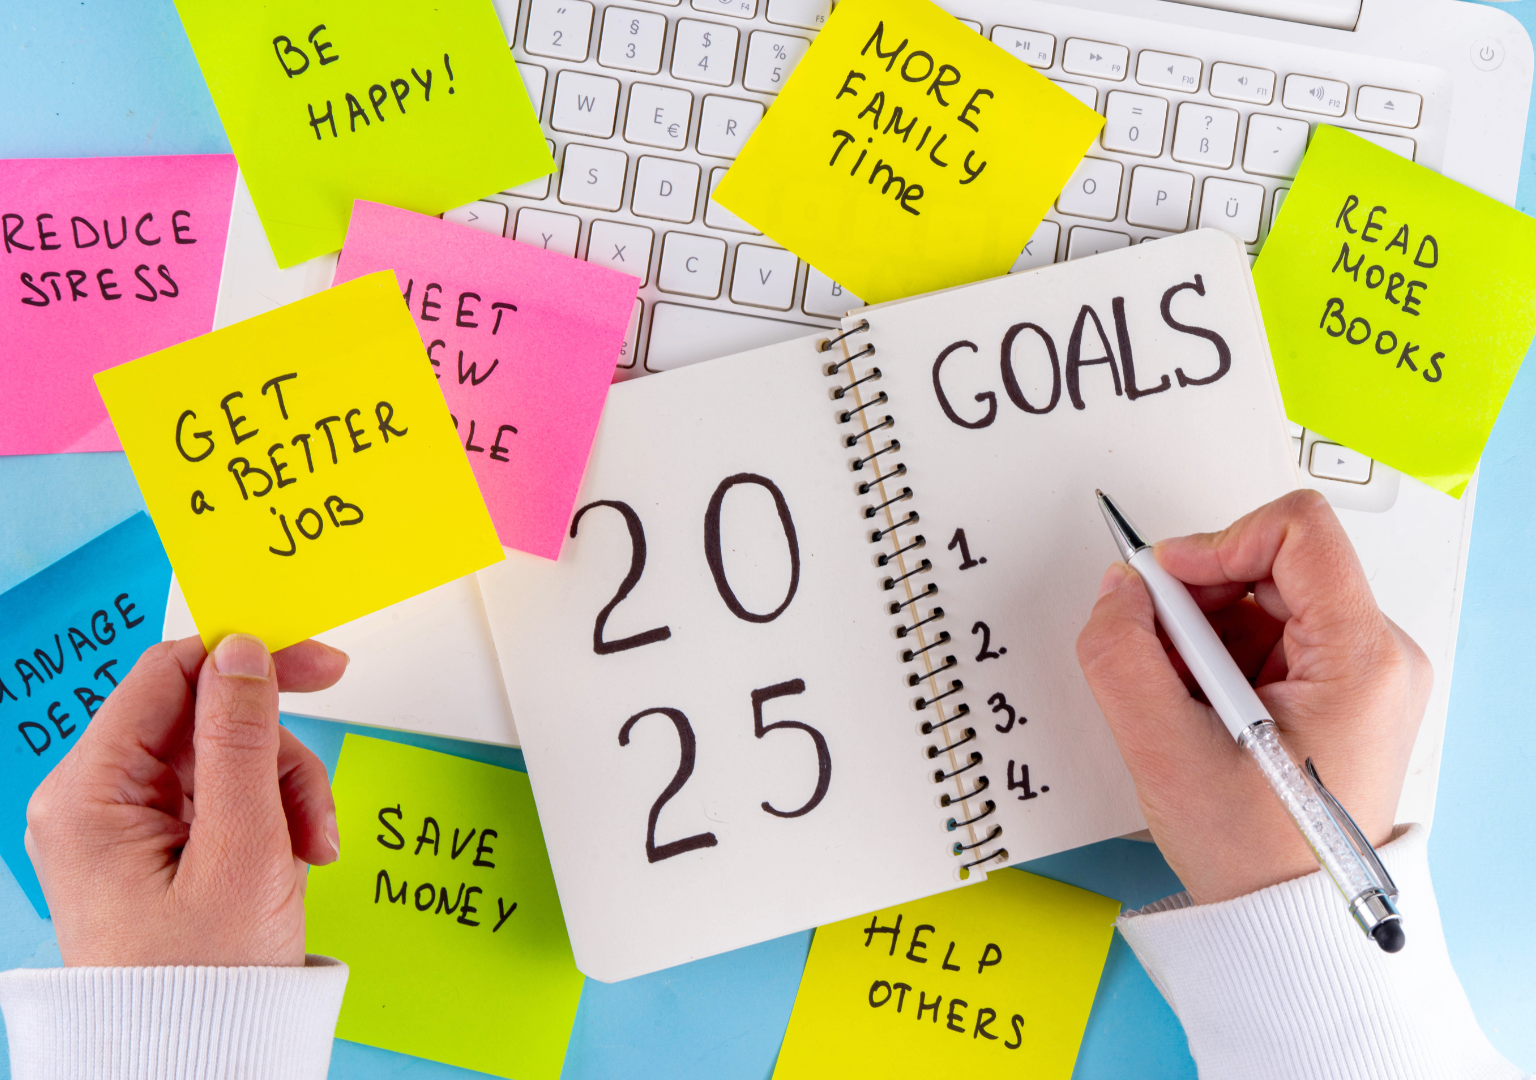
End the year by setting some intentional goals for 2025.

Final Thoughts

Closing out the year with a financial check-up is a powerful way to put yourself in the driver’s seat for 2025. These six steps are simple but effective and give you a clear view of your financial health. Here’s to closing out 2024 strong and stepping into 2025 with confidence!

Are you ready to make 2025 your breakthrough year?

MASTER YOUR MONEY is for YOU if you are tired of financial stress and ready to transform your relationship with money. Whether you’re managing a family, building your career, or chasing your dreams, this is your chance to gain the clarity, confidence, and habits you need to thrive.

This is more than a mindset shift—it’s a transformational program that puts you on the path to lasting financial success! ? Click the button below to book a call with Karen to see if this program is right for you!
Mastering Budget and Saving Techniques
Financial Resilience: Planning for Setbacks on Your Path to Debt Freedom

Financial Resilience: Planning for Setbacks on Your Path to Debt Freedom

Achieving a debt free life is a journey filled with highs and lows. While it’s great to stay optimistic, it’s equally important to be prepared for setbacks that might knock you off your progress. Unexpected expenses, job loss, medical bills, or even just plain old burnout can throw a spanner in your plans. The key to overcoming these challenges lies in building financial resilience. In this post, we’ll explore strategies to prepare for and bounce back from setbacks, ensuring you stay on track to becoming debt-free.

1. IDENTIFY YOUR MARKETABLE SKILLS

I bang on about this one all the time, why because an emergency fund is your financial safety net. It’s the cushion that helps absorb the shock of unexpected expenses without relying on credit cards or loans. A common rule of thumb is to have three to six months’ worth of living expenses saved.

Action Step:
Start by setting aside a small, manageable amount each week or month. Even $10 a week can add up. Automate your savings to ensure consistency and resist the temptation to dip into this fund for non-emergencies.

7. OFFER VIRTUAL SERVICES OR COACHING

Relying solely on one source of income can be risky. If you lose your job or face a reduction in hours, your finances can take a significant hit. Diversifying your income through side hustles, freelance work, or passive income streams can provide a buffer against such setbacks. I mentioned in a recent blog post tips and strategies on how “Using Your Talents to Accelerate Debt Repayment”. Go check this post out HERE.

Action Step:
Identify a side hustle or freelance opportunity that aligns with your skills. Set aside dedicated time each week to develop this secondary income stream.

3. CREATE A FINANCIAL CONTINGENCY PLAN

A contingency plan outlines what you’ll do in the face of financial setbacks. It could include steps like cutting back on non-essential expenses, using savings, or temporarily taking on additional work.

Action Step:
List potential setbacks and corresponding actions you would take to mitigate their impact. Keep this plan accessible and review it regularly.

4. PRACTICE CONSCIOUS SPENDING

Conscious spending involves being aware of where your money goes and making intentional choices. By being mindful of your spending, you’re better equipped to adjust your budget when faced with financial challenges.

Action Step:
Track all your spending for a month to identify where your money is going. Create a budget that prioritises essential expenses and allocates funds towards debt repayment and savings.

5. INVEST IN INSURANCE

Insurance is a vital component of financial resilience. Health insurance, home insurance, car insurance, and even disability insurance can protect you from significant financial setbacks. While it’s an added expense, the cost of not having adequate insurance can be much higher.

Action Step:
Review your current insurance policies and assess if you have adequate coverage. If not, consider adjusting your policies or shopping around for better rates.

6. PREPARE FOR IRREGULAR EXPENSES

Irregular expenses – like car repairs, home maintenance, or annual subscriptions can disrupt your debt repayment plan if not anticipated. Preparing for these expenses can prevent the need to rely on credit.

Action Step:
Review past expenses to identify irregular costs and create a separate savings fund for them. Allocate a small amount each month to this fund.

7. DEVELOP A DEBT REPAYMENT BUFFER

Instead of putting every last dollar towards debt, consider building a small buffer in your savings or checking account. This buffer can help cover unexpected expenses without halting your debt repayment plan.

Action Step:
Determine a comfortable buffer amount (e.g., $500) and gradually build it up by allocating a portion of your income each month.

8. KEEP YOUR CREDIT IN GOOD STANDING

Maintaining a good credit score is crucial, even when you’re working to pay off debt. In the event of a financial emergency, having access to credit can provide a temporary solution without resorting to high-interest loans.

Action Step:
Regularly check your credit report for errors and keep credit card balances low. Make all payments on time, even if it’s just the minimum amount.

9. EMBRACE THE POWER OF NEGOTIATION

Unexpected expenses can often be negotiated or spread out. Medical bills, for instance, are notorious for being negotiable. Don’t hesitate to ask for a payment plan, a reduction in interest rates, or even a discount.

Action Step:
If faced with a large, unexpected bill, contact the service provider and enquire about payment options, discounts, or financial assistance programs.

10. FOSTER A RESILIENT MINDSET

Building financial resilience isn’t just about money—it’s also about mindset. Understand that setbacks are a part of life, and maintaining a positive outlook will help you navigate them more effectively.

Action Step:
Practice stress-management techniques such as mindfulness, meditation, or journaling. Develop a routine that helps you stay focused and calm during financial challenges.

11. BUILD A SUPPORT NETWORK

Having a support network of friends, family, or a financial advisor can provide emotional and practical support during challenging times. Surround yourself with people who understand your goals and can offer advice or encouragement.

Action Step:
Identify three people who can be part of your financial support network. Share your goals with them and ask for their support in staying accountable. 

12. PLAN FOR FUTURE SETBACKS

While it’s impossible to predict every setback, planning for potential scenarios can make them less overwhelming. Think about what could go wrong in your financial journey and devise strategies to deal with them.

Action Step:
Conduct a “financial fire drill.” Write down potential setbacks (e.g., job loss, major car repair) and create a response plan for each scenario.

13. REGULARLY REVIEW AND ADJUST YOUR FINANCIAL PLAN

Your financial situation and priorities can change over time. Regularly reviewing and adjusting your debt repayment plan ensures you stay on track and adapt to new circumstances.

Action Step:
Set a reminder to review your financial plan every quarter. Adjust your budget, debt repayment, and savings strategies based on your current situation.

CONCLUSION

Setbacks are inevitable on the path to becoming debt-free, but with the right preparation, they don’t have to derail your progress. By building financial resilience through strategic planning, conscious spending, and a positive mindset, you can bounce back stronger from any challenge. Remember, becoming debt-free is not a sprint; it’s a marathon. Stay focused, stay prepared, and keep moving forward. 

Take Control of Your Finances Today!

Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.

As your financial coach, Karen will teach you how to build financial muscle, so that you have money working to your advantage and not to your bank or financial institution’s benefit. Click here to enrol!

Mastering Budget and Saving Techniques

Are you ready to take control of your finances and start your debt-free journey?

In this empowering 30-day course, we’ll guide you through actionable steps to help you break free from debt and achieve financial stability.