What Is a Small Business in Australia? It’s Bigger Than You Think

What Is a Small Business in Australia? It’s Bigger Than You Think

When you hear “small business”, what do you picture?

For most people it’s a corner shop. A mum-and-dad operation. One van, one phone, a kitchen-table office.

So when you’re running a trades or service business with eight staff, three utes and a seven-figure turnover, “small business” can feel like the wrong label. Like it’s talking about someone else.

Here’s the thing… by every official Australian measure, it’s talking about you.

By the end of this article you’ll know what “small business” actually means in Australia, why the definitions don’t agree, and three numbers to check in your own business this week.

What is a small business in Australia? The short answer

There’s no single definition. The ABS counts a small business as one with fewer than 20 employees. The ATO uses aggregated turnover of less than $10 million. Fair Work uses fewer than 15 employees. And ASIC treats a proprietary company as small unless it meets two of three “large” tests on revenue, assets and employees.

Four official definitions, four different answers

There’s no single definition of a small business in Australia. Each government body draws the line for its own purpose.

The ABS (statistics): a small business has fewer than 20 employees. That’s the standard the Australian Bureau of Statistics uses when it counts businesses.

The ATO (tax): you’re a small business entity if you carry on a business and your aggregated turnover is less than $10 million. That turnover includes connected and affiliated businesses. (A few concessions use other thresholds, like $5 million for the small business income tax offset.)

Fair Work (employment): under the Fair Work Act, a small business employer has fewer than 15 employees. That headcount includes part-time staff, regular casuals and employees of associated entities. It matters for things like unfair dismissal rules.

ASIC (companies): a proprietary company is “large” if it meets at least two of these three tests: consolidated revenue of $50 million or more, consolidated gross assets of $25 million or more, or 100 or more employees. If it doesn’t, it’s a small proprietary company. (The Government has proposed lifting the revenue and assets tests to $100 million and $50 million, but ASIC says those changes aren’t in effect yet.)

Notice the range. “Small” can mean fewer than 15 people, fewer than 20, under $10 million in turnover, or under $50 million in revenue. Same label, very different businesses.
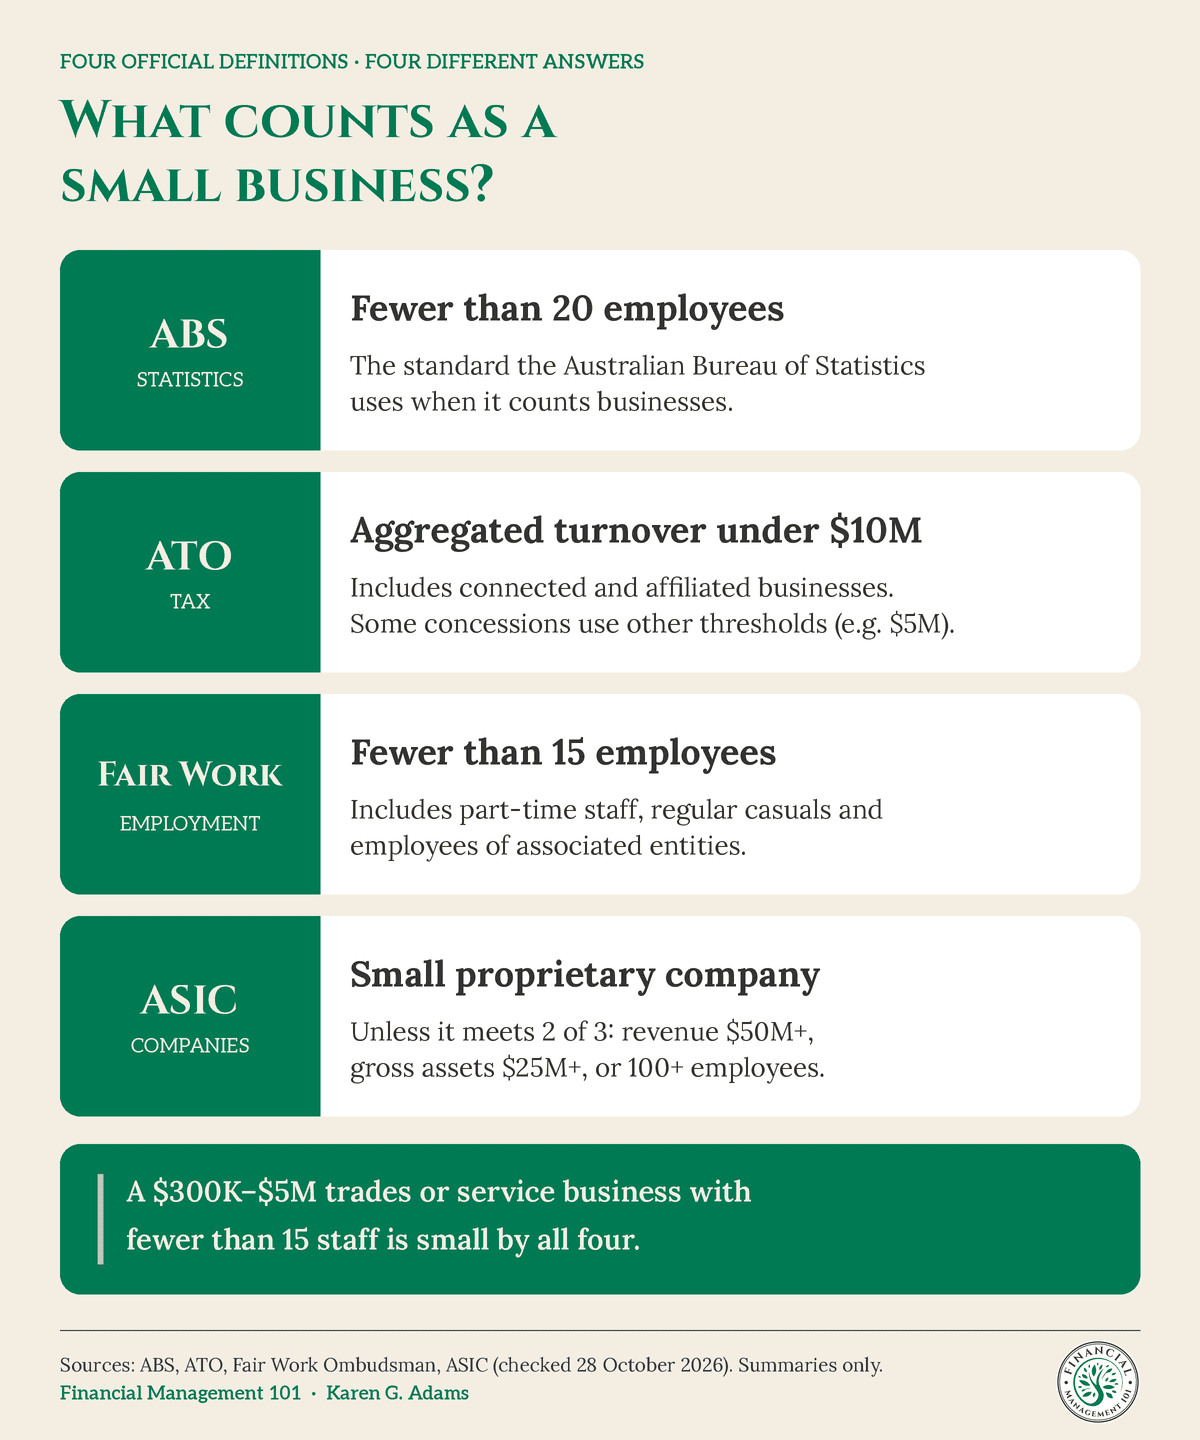
Graphic titled What counts as a small business? ABS: fewer than 20 employees. ATO: aggregated turnover under $10 million. Fair Work: fewer than 15 employees. ASIC: a small proprietary company unless it meets 2 of 3 tests, revenue $50 million or more, gross assets $25 million or more, or 100 or more employees.
Same label, four different lines. A $300K to $5M trades or service business with fewer than 15 staff is small by all four.

What the numbers say about who’s really out there

The ABS counted 2,814,778 actively trading businesses in Australia at 30 June 2026. About 97 per cent of them had fewer than 20 employees.

Yes, plenty are tiny. Around 65 per cent don’t employ anyone at all.

But look at turnover. At 30 June 2025, the latest turnover figures available, 35.4 per cent of Australian businesses turned over between $200,000 and $2 million. Another 4.8 per cent turned over between $2 million and $5 million.

That’s about 1.1 million businesses in the $200K to $5M range. Real operations, with wages, vehicles, suppliers, tax obligations and families relying on them.
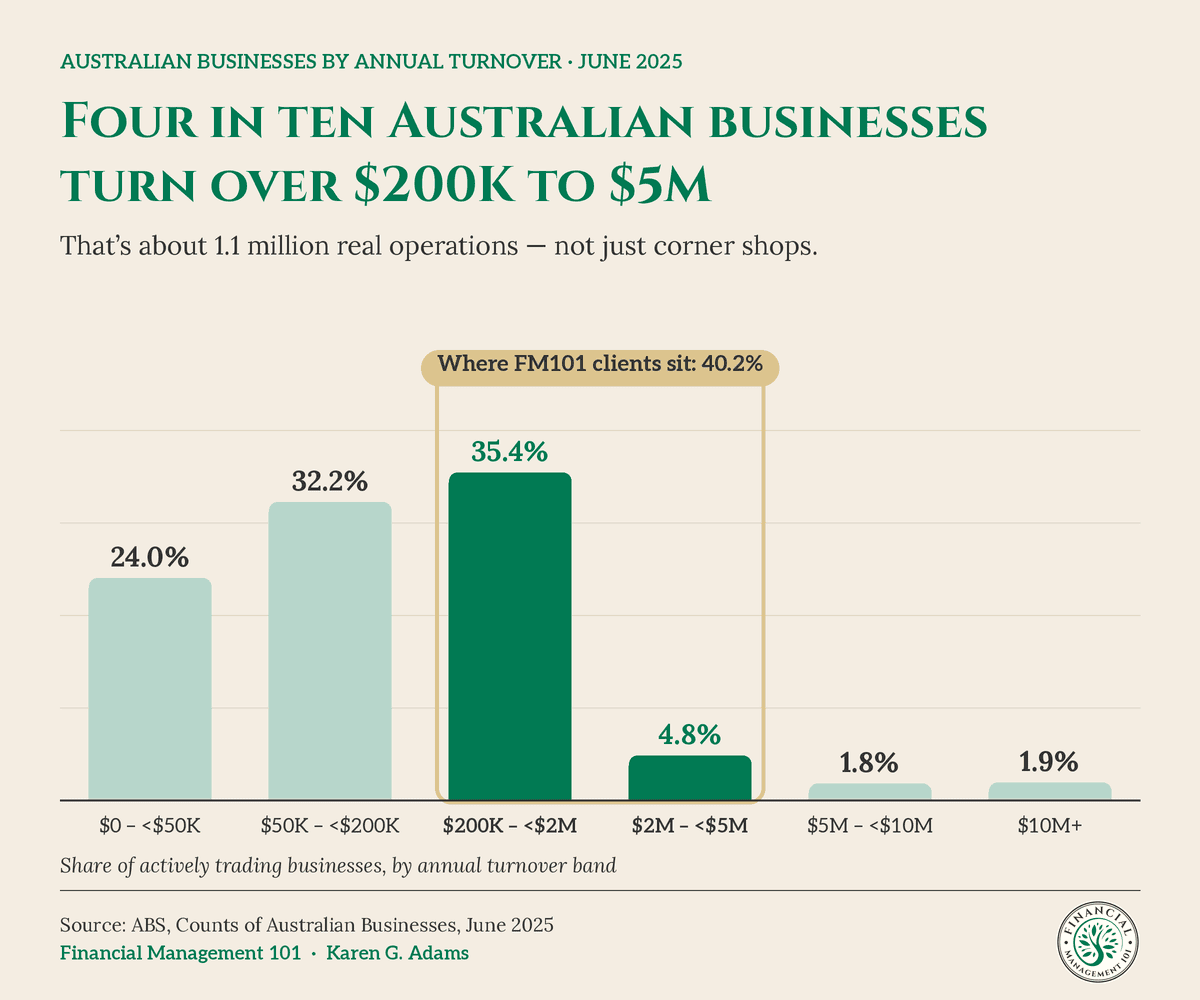
Bar chart of Australian businesses by annual turnover at June 2025: $0 to under $50K 24.0%, $50K to under $200K 32.2%, $200K to under $2M 35.4%, $2M to under $5M 4.8%, $5M to under $10M 1.8%, $10M or more 1.9%. The $200K to $5M bands are highlighted as where FM101 clients sit, 40.2% combined. Source: ABS, Counts of Australian Businesses, June 2025.
Four in ten Australian businesses turn over $200K to $5M. Source: ABS, Counts of Australian Businesses, June 2025.

So if your trades or service business turns over $300,000 to $5 million with fewer than 15 staff, you’re a small business by every official measure. With up to 19 staff, you still are for the ABS, the ATO and ASIC. And either way, you’re running something substantial.

I call it Too Big to Wing It. Too Small to Need a CFO.

Why the label matters more than you’d think

When we picture “small business” as tiny, we tend to run it like it’s tiny.

We check the bank balance and call it financial management. We look at the numbers at tax time. We assume that if the phone’s ringing and the team’s busy, the money must be fine.

At $1.5 million in turnover, that approach gets expensive. Let me show you exactly what I mean.

A worked example: a fictional electrical business with 10 staff

  • Turnover: $1,500,000
  • Direct costs (materials, subcontractors, on-the-tools wages): $900,000
  • Gross profit: $600,000, or 40 cents in every dollar
  • Overheads (rent, vehicles, insurance, software, admin): $380,000
  • A fair wage for the owner: $120,000
  • What’s actually left: $100,000

That’s under 7 cents in every dollar of turnover.

And the break-even point? Overheads plus the owner’s wage, divided by the gross profit margin: $500,000 ÷ 40% = $1,250,000. This business is only $250,000 above break-even.

A few underquoted jobs, one slow-paying builder or an uncosted variation or two, and that 7 cents disappears fast. On a $1.5 million turnover, the room for guesswork is small.

This example is fictional and for illustration only. Your figures will be different.

Your accountant and bookkeeper make sure the numbers are right. That’s essential. The next step is you knowing how to run the business with them, week to week.

Your action this week: check your three gauges

Block out 30 minutes this week with your latest monthly reports. Think of them as the three gauges on your dashboard.
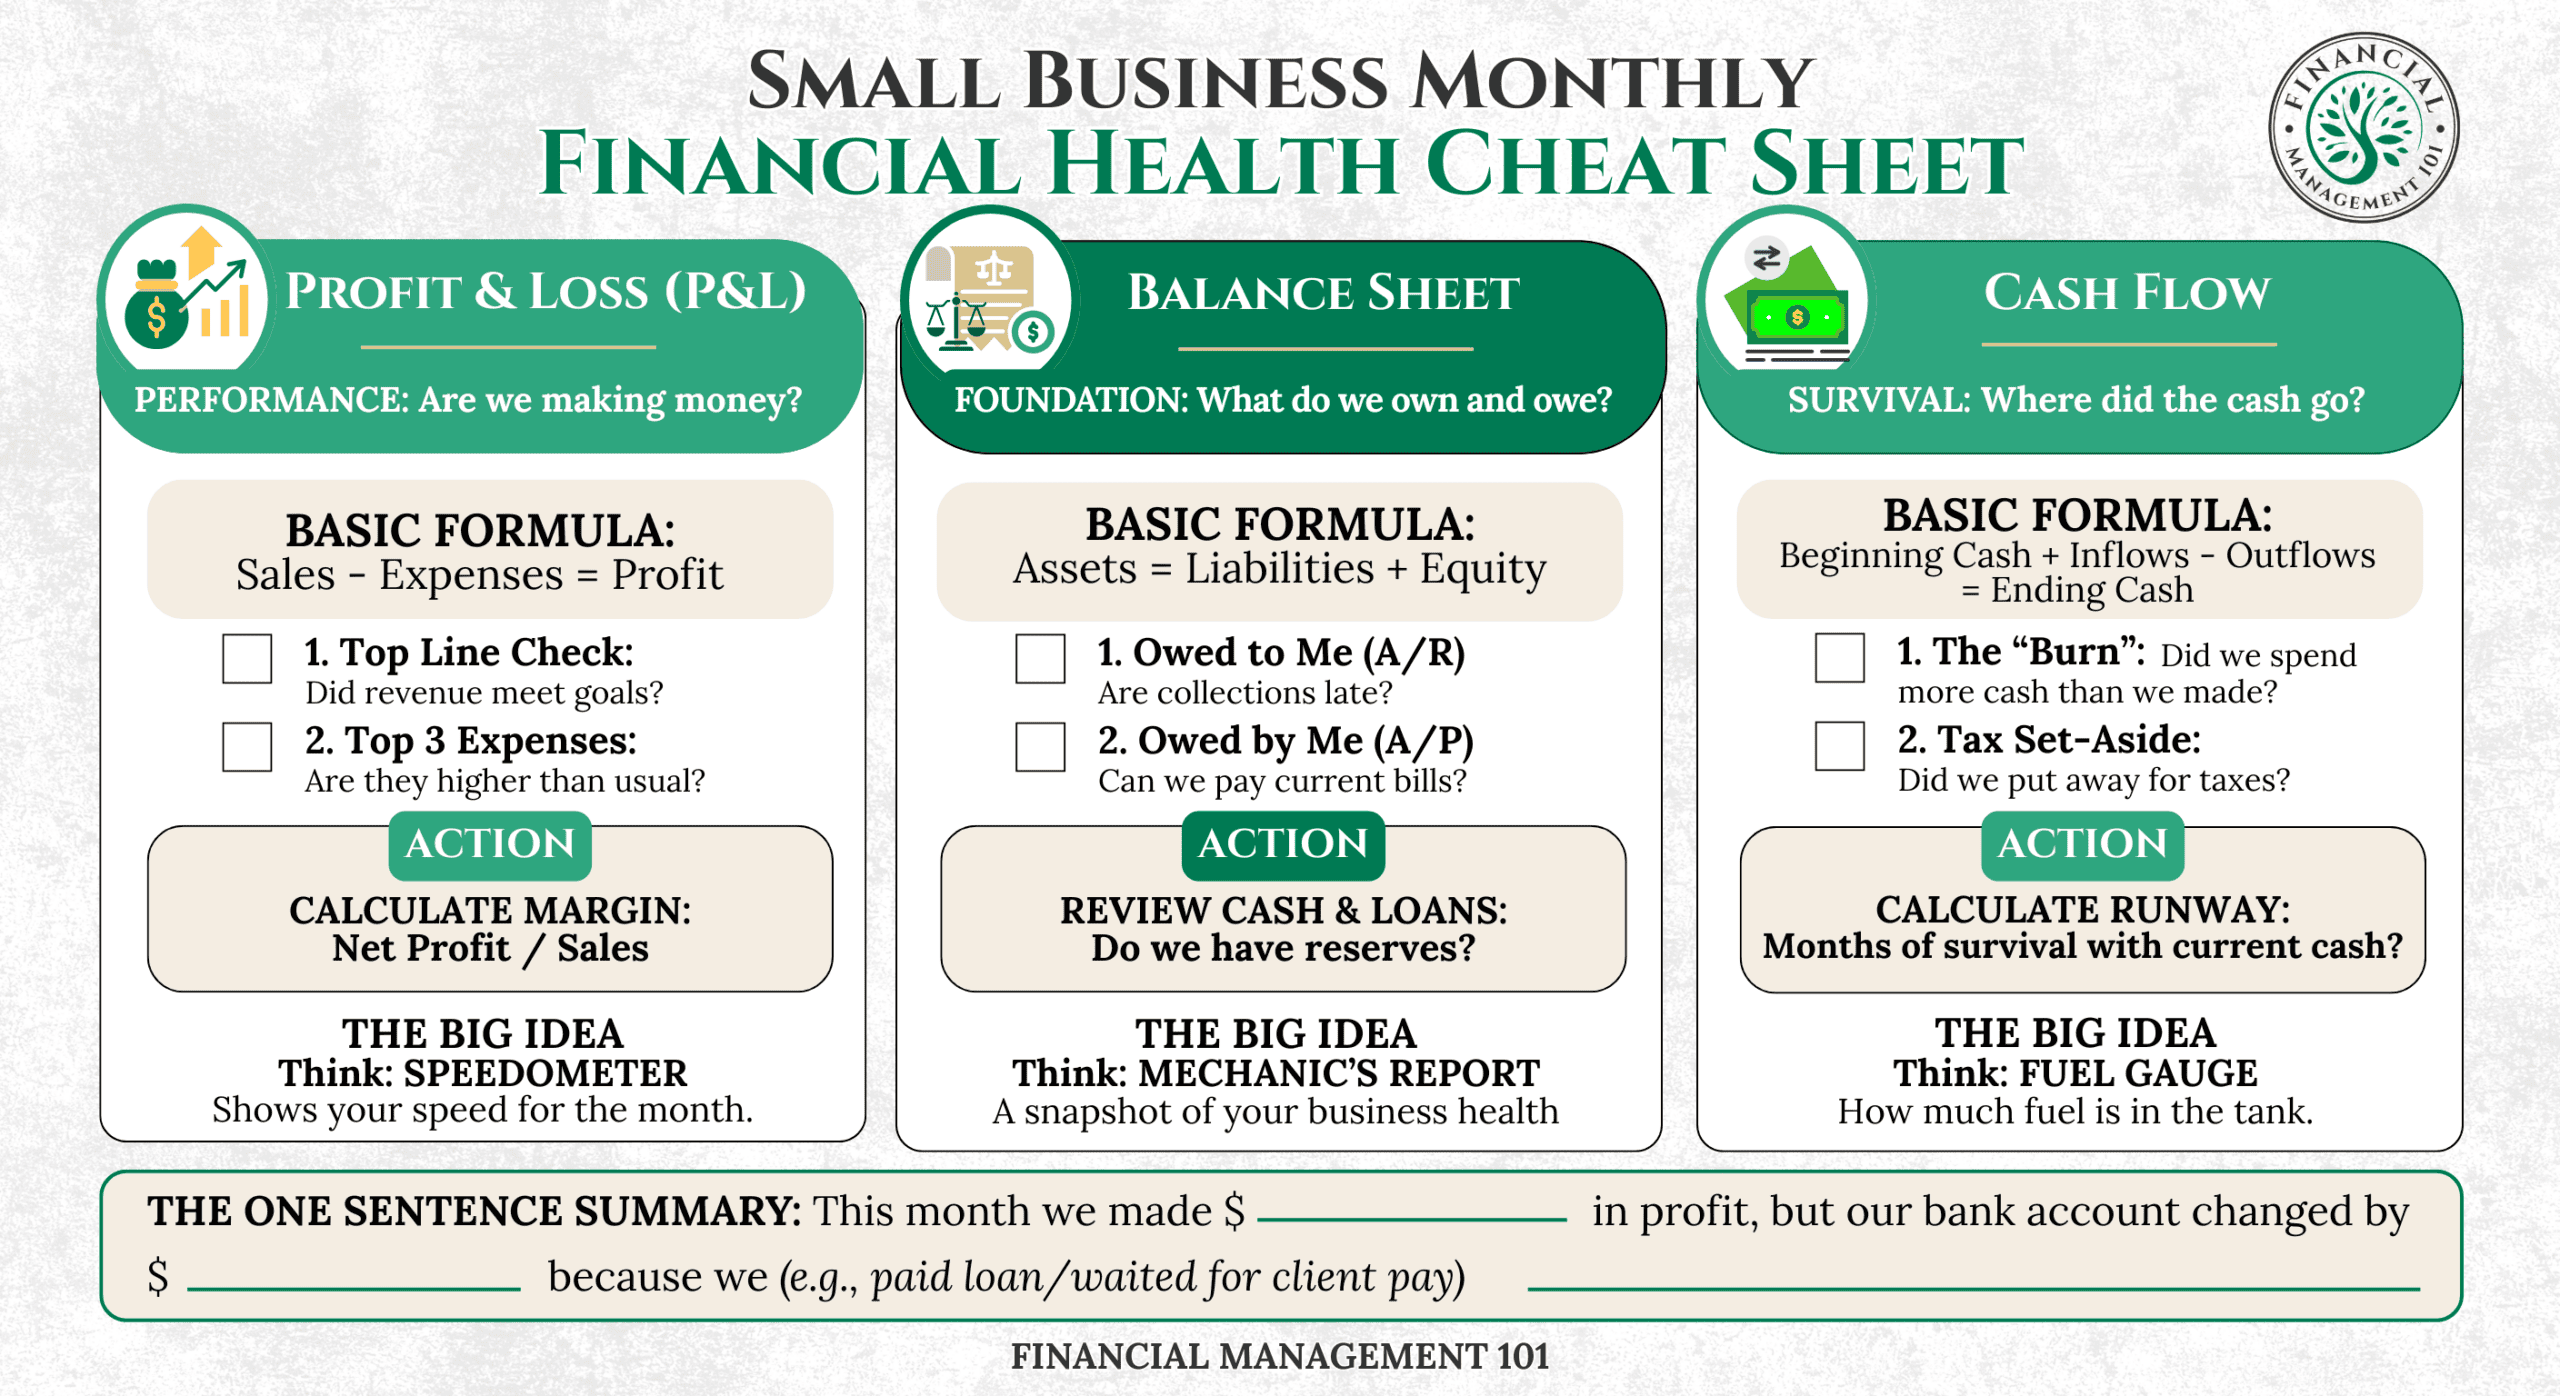
Small Business Monthly Financial Health Cheat Sheet from Financial Management 101: Profit & Loss as the speedometer, Balance Sheet as the mechanic's report and Cash Flow as the fuel gauge, each with a basic formula, two checks and one action, plus a one-sentence summary to fill in.
Your three gauges on one page: the Small Business Monthly Financial Health Cheat Sheet.

1. The speedometer: your Profit & Loss

It shows how fast you’re going this month. Are we making money?

Calculate your net profit margin: net profit ÷ sales. In our example, $100,000 ÷ $1,500,000 = 6.7%. Then ask: did revenue meet the goal, and are the top three expenses higher than usual?

2. The mechanic’s report: your Balance Sheet

It’s a snapshot of what you own and what you owe.

Check what customers owe you. Are collections running late? Then check what you owe. Can you pay current bills, and do you have reserves?

3. The fuel gauge: your cash flow

It tells you how much is in the tank.

Calculate your runway: cash on hand ÷ average monthly outgoings. In our example, monthly outgoings are about $116,700. If there’s $90,000 in the bank, that’s under three weeks of fuel. Also check: did we spend more cash than we made, and have we set aside enough for tax?

Related reading: Why Is Cashflow Always Tight?

Then write one sentence

“This month we made $_____ in profit, but our bank account changed by $_____ because we _____.”

That one sentence connects your profit to your cash. When you can read the story, you can change the ending.

Related reading: What Numbers Should A Small Business Owner Track?

Your next step: The EDGE Business Health Check

If doing those three checks raised more questions than answers, you’re not alone in this.

The EDGE Business Health Check is the next step. It takes about 20 minutes with your last 12 months’ Profit & Loss, and it gives you:

  • Your EDGE Score across 30 statements in five areas: Profit & Pricing, Cashflow, CEO Visibility, Systems & Freedom, and Growth
  • Your Profit Leak Calculator results: your break-even, your true net profit once you’re paid fairly, what a 5% price rise would add, what your unbilled time is worth, and how much cash is tied up in slow payers
  • Your lowest area, so you know the one thing to fix first
  • A 7-Day Reset you can start on Monday, around 20 minutes a day

It’s $47, and it’s designed for established business owners like you.
The EDGE Business Health Check by Karen G. Adams, Financial Management 101. What if the problem isn't what you think it is? Uncover hidden profit leaks, cashflow pressures and growth bottlenecks in less than 20 minutes.

Rather talk it through first? Get in touch and book a call with me.

Frequently asked questions

What is the ATO definition of a small business?

For tax, you’re a small business entity if you carry on a business and your aggregated turnover is less than $10 million. That turnover includes connected and affiliated businesses. A few concessions use other thresholds, like $5 million for the small business income tax offset.

How many employees can a small business have in Australia?

It depends who’s asking. The ABS counts a small business as one with fewer than 20 employees. Under the Fair Work Act, a small business employer has fewer than 15 employees, including part-time staff, regular casuals and employees of associated entities.

Is a business turning over $300,000 to $5 million still a small business?

Yes. If your trades or service business turns over $300,000 to $5 million with fewer than 15 staff, you’re a small business by every official measure. With up to 19 staff, you still are for the ABS, the ATO and ASIC.

How many small businesses are there in Australia?

The ABS counted 2,814,778 actively trading businesses in Australia at 30 June 2026. About 97 per cent of them had fewer than 20 employees, and around 65 per cent don’t employ anyone at all.

When is a company “small” under ASIC’s rules?

A proprietary company is “large” if it meets at least two of three tests: consolidated revenue of $50 million or more, consolidated gross assets of $25 million or more, or 100 or more employees. If it doesn’t, it’s a small proprietary company. The Government has proposed lifting the revenue and assets tests, but ASIC says those changes aren’t in effect yet.

You’ve built something real. Financial confidence starts with clarity.

Karen G. Adams
Small Business Performance Strategist, Financial Management 101


Business education only, not financial, tax or legal advice. The official definitions above are summaries; check with your accountant or adviser how each one applies to your business.
The Financial House Inspection: 10 Sneaky Money Leaks (And How to Plug Them Fast)

The Financial House Inspection: 10 Sneaky Money Leaks (And How to Plug Them Fast)

Let me ask you something… if your financial house was a real house, would you invite guests over right now?

Or would you do that frantic pre-visit panic clean where you shove everything into the laundry or the spare room and pray nobody opens that door?

Because that’s what most people are doing financially.
Not because they’re “bad with money” (you’re not), but because life is busy, expensive, and full of sneaky little costs that quietly set up camp in your bank account like they pay rent.

And the truth is… you don’t always need a bigger income to feel more in control.
Sometimes you just need to find the leaks.

Today, we’re doing a Financial House Inspection – warm cuppa in hand, no shame, no judgement, and definitely no stiff “financial coach voice.”  You’ll walk away with practical fixes, a clearer head, and probably a few “WAIT… WHAT?!” moments.

Let’s inspect your money house.

Why “Money Leaks” Matter (Even If You Earn Good Money)

A money leak is not a big, dramatic purchase you remember forever (like buying a car or going on a holiday).

A money leak is the “small stuff” you don’t notice… until you look at your bank statement and think:

“Excuse me, where did my money go?”

Leaks are dangerous because they:

  • feel harmless in the moment
  • happen repeatedly
  • add up faster than you think
  • make you feel like you’re always behind even when you’re trying

And here’s the kicker: leaks are often emotionally driven, not logically driven. They’re convenience, comfort, habit, exhaustion, reward, stress, or just not having a system in place.

So let’s find them and plug them like the financially strong legend you are.

The Financial House Inspection Checklist: 10 Common Money Leaks

1) The Subscription Graveyard

This one is so common it deserves its own memorial plaque.

Streaming services, apps, software, gym memberships, delivery memberships, random “productivity tools,” audiobooks, meditation apps, cloud storage…

And you know what makes subscriptions sneaky?
They don’t hurt enough to notice. It’s just $9.99 here… $14.99 there… $24.99 for something you “might use.”

Until suddenly you’re donating $300 a month to the Subscription Graveyard.

Quick Fix:

  • Go through your bank statements and highlight every recurring payment.
  • Ask: “Would I buy this again today?”
  • Cancel anything that isn’t a HELL YES.

Pro tip:
If cancelling makes you panic (“but what if I need it one day?”), that’s not logic, that’s fear. And fear is expensive.

2) Lazy Renewals (Insurance, Utilities, Phone Plans)

Lazy renewals are like leaving a tap dripping for years and being shocked your water bill is high.

Insurance companies love loyal customers… because loyal customers often don’t check the price.

Phone plans creep up. Internet deals expire. Electricity rates change. Suddenly you’re paying premium pricing for basic service.

Quick Fix:

  1. Put a recurring reminder in your calendar every 6–12 months:
    • car/home insurance
    • health insurance
    • electricity/gas
    • phone/internet
  2. Compare and renegotiate.

Money mindset note:
Being financially responsible is not being “cheap.” It’s being strategic.

3) Bank Fees and “Oops” Charges

Account keeping fees. International transaction fees. ATM fees. Late payment fees. Overdraft fees.

These aren’t “just the cost of banking.” They’re often the cost of not having the right account setup or system.

Quick Fix:

  • Review your bank accounts and credit cards.
  • Ask your bank: “Is there a fee-free option?”
  • Set up alerts for low balances and bill due dates.
  • Automate minimum payments to avoid late fees.

You don’t need to pay $10 – $30 a month in fees just to have a bank account. Your money deserves better.

4) Convenience Spending (AKA “I’m Too Tired” Tax)

This is the one people don’t want to admit because it’s so relatable.

Convenience spending is:

  • takeaway because you’re exhausted
  • Uber because parking feels like emotional warfare
  • delivery apps because “I’ll just get one thing”
  • pre-made meals because you can’t face thinking

And honestly? Sometimes it’s worth it. Life is busy. You’re human. But if it’s happening on autopilot, it becomes a leak.

Quick Fix:

  • Create a weekly “convenience budget”  –  guilt-free, planned.
  • Have one or two “emergency meals” at home (freezer meals, eggs, wraps, anything easy).
  • Decide your rules before you’re tired.

This isn’t about perfection. It’s about awareness + boundaries.

Convenience Spending includes food delivery services.

5) Supermarket Drift (The “Just One More Thing” Trap)

You go in for milk and bread. You come out with:

  • fancy dips
  • a plant you didn’t need
  • snacks for “school lunches” (even though you don’t have kids)
  • and a candle because self-care.

The supermarket is designed to separate you from your money with maximum efficiency.

Quick Fix:

  • Shop with a list (yes, like a grown-up, annoying but effective).
  • Eat before you shop.
  • Do click-and-collect if you’re an impulse buyer.
  • Track your weekly grocery spend for 4 weeks and be honest about what’s happening.

Groceries are one of the easiest leaks to tighten without feeling deprived.

6) The Servo Snack & Coffee Leak

The little daily habits: coffee, snacks, “just grabbing something,” the quick drink on the way home, the “treat” because the day was hard.

And let me be clear: you’re allowed joy. But when joy is unplanned and daily, it becomes a leak.

Quick Fix:

  • Choose what’s worth it.
  • If café coffee is your thing, keep it, but make it intentional.
  • Set a weekly allowance for treats and stick to it.

The goal isn’t to become a finance robot. The goal is to stop accidentally overspending.

7) Lifestyle Inflation (The “I Deserve It” Spiral)

This one is sneaky because it feels like progress. You earn more… so you spend more. New car. Nicer clothes. More dinners out. Better holidays. Upgraded everything.

And you might still feel broke. Lifestyle inflation isn’t about being irresponsible. It’s about missing the moment where you lock in your future before upgrading your present.

Quick Fix:

  1. When income increases, decide in advance:
    • what percentage goes to lifestyle
    • what percentage goes to savings/investing
    • what percentage goes to debt reduction
  2. Automate “Future You” first.

Future You is not asking for everything.
Future You is asking for something.

8) “Buy Now Pay Later” (BNPL) and Payment Splitting

BNPL is basically like inviting little debts into your house and then being shocked they’re eating all your groceries.

It doesn’t feel like debt because it’s broken up into payments.
But it still reduces your future cash flow and adds mental load.

Quick Fix:

  • List every BNPL account and total outstanding.
  • Pause new purchases until the balances are cleared.
  • Rebuild a sinking fund for things you commonly use BNPL for (clothes, gifts, school costs, etc.

BNPL is not evil. But it is dangerous if it becomes your normal.

9) Unused Memberships and “Aspirational Spending”

This is spending money on the version of you who:

  • goes to the gym 5 days a week
  • does yoga at sunrise
  • reads 2 business books a week
  • meal preps like a wellness influencer
  • uses that online course “soon”

We’re funding our aspirational selves while our current selves are just trying to get through Tuesday.

Quick Fix:

  • Keep one “growth” commitment at a time.
  • If you’re not using it, pause it.
  • Choose what actually fits your life right now.

The goal is to build financial muscle, not financial guilt.

10) The “No System” Leak (The Biggest One)

This is the mother of all leaks. Because even if you fix everything above, if you don’t have a system, the leaks come back.

A system is what creates calm. It tells your money where to go before life grabs it first.

Quick Fix:
Start with these basics:

  • a separate bills account
  • automatic transfers on pay day
  • a weekly money check-in (10 minutes)
  • clear spending categories (not 47 categories… just the ones that matter)

Most people don’t have a money problem. They have a money flow problem.

And that is fixable.

Your Mini Action Plan: Plug Leaks in 30 Minutes This Week

If you want to feel immediate relief, do this:

  1. Print your last 30 days of transactions (or pull them up on your banking app).
  2. Highlight anything that surprised you.
  3. Circle:
    • subscriptions
    • takeaway/coffee
    • shopping
    • fees
  4. Choose 3 leaks to plug this week.
  5. Move the money you save into a separate “Future Me” account.

That last step matters. If you don’t redirect the savings, it disappears into new spending. Money is like that. It loves momentum.

Print your last 30 days of transactions (or pull them up on your banking app). Then, highlight anything that surprised you.

The Real Truth: You Don’t Need More Willpower – You Need Support + Structure

I want to say something kindly but clearly:

If you’ve tried to “get on top of money” before and it didn’t stick, it’s not because you’re hopeless. It’s because you’ve been trying to do it alone, in between work, kids, stress, bills, and exhaustion… with zero structure and a lot of pressure.

And that’s not a character flaw. That’s a strategy gap.

Come Into the Membership (Because This Is What We Do Together)

If reading this has you thinking, “Okay… I can see the leaks, but I need help making this a real system,” then babe – this is exactly why I created my Membership.

Inside the Membership, we don’t just talk about money. We build financial muscle.

✅ We identify your personal leaks (not generic ones).
✅ We set up a simple money system that actually fits your life.
✅ We make progress without shame, overwhelm, or perfection.
✅ You get guidance, structure, education, and support – so you’re not constantly starting over.

Because getting your financial house in order isn’t about a one-time clean-up.
It’s about building habits and systems that keep it running smoothly long-term.

If you’re ready to stop guessing and start feeling in control, join the Membership.
Let’s plug the leaks, create a plan, and turn your financial house into a place you feel proud to live in.

#HowToResetMyMoneyMindset #WhyDoIFeelOutOfControlWithMoney #HowToFeelInControlOfFinances #ResetMoneyMindset2025 #NewYearFinancialMindset #HowToStartFreshWithMoney Discover 10 sneaky money leaks draining your bank account and simple fixes to plug them fast. Get your financial house in order without the guilt. financial house in order, stop overspending, budgeting without stress, cash flow tips reduce financial stress, personal finance Australia spending habits save money fast, subscriptions costing me money, how to manage money better


Cash Flow is King: Why Every Small Business Owner  Needs a Financial Plan (Not Just More Work)

Cash Flow is King: Why Every Small Business Owner  Needs a Financial Plan (Not Just More Work)

If you’re a tradie, Franchisee or small business owner, chances are you’ve said this before:

“I just need more work.”
“If I can land that next big job, I’ll be sweet.”
“Once I get through this month, I’ll finally get on top of things.”

Sound familiar?

We’ve been sold this idea that working more hours or taking on more jobs is the key to financial stability.

But here’s the truth…

More work won’t fix your money problems if your financial plan is broken.

Let me say that again: More work won’t fix broken cash flow.

In fact, working harder without a system can actually worsen your money stress – leading to burnout, resentment, and a business that runs you, instead of the other way around.

In this blog, I’ll break down why cash flow is king, how small business owners end up in the trap of “more jobs = more chaos”, and what you can do to take control of your money (without working yourself into the ground).

The Myth of “More Work = More Money”

Let’s say you take on 3 new clients this month as a tradie. Awesome, right?
But then:

  • You buy more materials
  • You spend more hours on-site
  • You hire a subbie to help out
  • You juggle more admin
  • You forget to invoice someone
  • And suddenly – you’re busier than ever… but your bank account doesn’t show it

That’s because revenue doesn’t equal profit, and being busy doesn’t equal being financially fit.
You can be flat-out all month and still feel broke.

That’s the trap, and I see it every week with tradies, franchisees and business owners who are absolutely brilliant at what they do… but never learned how to manage the money side of things.

So What’s the Real Problem?

It comes down to one powerful truth:

Cash flow – not just income – is what makes or breaks your business.

Cash flow is the movement of money in and out of your business.

Not just how much you make, but:

  • When you get paid
  • How consistently money comes in
  • What goes out each week
  • Whether you’re left with a profit (or just scraping by)

If you don’t have control over your cash flow, you’re always reacting. You’re playing catch-up. And that stress leaks into everything – your health, your relationships, and even the quality of your work.

Here’s What Cash Flow Chaos Looks Like

If you’ve ever experienced any of these, you’re in a cash flow crunch:

  • You avoid checking your account because you’re afraid of what you’ll see
  • You wait until BAS is due to realise you owe thousands
  • You struggle to pay your own wage regularly
  • You’re always chasing late invoices
  • You can’t take time off because you’re constantly hustling to “keep up”
  • You’ve had to dip into your personal savings more than once

Sound familiar? You’re not alone. But the good news is – it’s fixable.

The Solution: A Simple, Small Business – Friendly Financial Plan

You don’t need a finance degree or a fancy accountant to get this sorted. You just need a clear plan for how money flows through your business. Here’s how to start building one.

1. KNOW YOUR BREAK-EVEN POINT

This is the minimum amount of money you need to earn each month to cover:

  • Business expenses (tools, fuel, phone, materials, subs, etc.)
  • Your personal wage
  • Tax and super
  • Any loan or debt repayments

Without knowing your break-even, you’re guessing. You’re flying blind. Once you’ve nailed this number, everything becomes clearer.

Now, you can set targets based on facts – not hope.

2. PAY YOURSELF A WAGE – YES, YOU!

This is the game changer. Every time income hits your account, it should be split into different buckets. That way, you’re not tempted to spend what should’ve gone to tax, bills, or your own pay.

Here’s a simple version that works great for small business owners:

✅ Income Account
Where all your payments land. This is your holding zone.

✅ Owner’s Pay Account
Your regular wage. Non-negotiable. You work hard, you deserve to be paid consistently.

✅ Expenses Account
Materials, suppliers, fuel, subscriptions, etc.

✅ Tax & BAS Account
Put aside 25 – 30% of every payment for Tax plus the GST portion. No more panic come BAS time.

✅ Profit Account
Even just 5% of each job. This is for rainy days, growth, or peace of mind.

You can set this up in 30 minutes through online banking. Once you do? You’ll sleep better knowing your money is finally working for you.

3. TRACK YOUR MONEY CASH FLOW

Once a week, check in on your numbers. This doesn’t need to be a 2-hour admin marathon. I’m talking 20–30 minutes to:

  • See what came in
  • Check what went out
  • Update your numbers
  • Chase unpaid invoices
  • Move money into your buckets

Make this a weekly ritual (I call it a Money Date) and watch your confidence skyrocket. Because the more you look at your money, the less power it holds over you.

4. TRACK YOUR MONEY CASH FLOW

You can have all the work in the world, but if your prices don’t reflect the true cost of running your business – you’ll never get ahead.

Too many small business owners undercharge because they’re afraid of losing the work.

But if you’re not charging for:

  • Admin time
  • Quote prep
  • Travel
  • Time off tools
  • Overheads
  • Profit margin

…then you’re not building a business. You’re building a time bomb.

You should be pricing with confidence, knowing that it covers everything – not hoping for the best.
Inside The Edge, I teach you a simple pricing calculator so you know exactly what to charge and why.

5. BUILD A BUFFER FUND

We all know some work can be seasonal or unpredictable.

A job gets delayed. A client pays late. You get sick. And suddenly your cash flow takes a hit. That’s why a buffer fund is crucial.

Aim to build up 1–3 months’ worth of business expenses in a separate account. This gives you breathing space and avoids making panic-driven decisions like slashing prices or taking on crappy jobs just for quick cash.

Start small – $50 a week adds up. Automate it. Make it part of your money system. 

Build a Buffer Fund

The Truth? You Don’t Need More Work. You Need a Better Money Plan.

You don’t need to hustle harder. You don’t need to take every job that comes your way. You need to manage your money better so the work you’re already doing actually pays off. Imagine this:

  • Getting paid consistently – even in quiet months
  • No more panicked BAS seasons
  • Knowing exactly what your business needs to earn each week
  • Saying YES to time off without financial stress
  • Watching your bank account grow, not shrink

That’s what happens when cash flow becomes your king, and your systems support you, not sabotage you.

And That’s Exactly What We Do Inside THE EDGE

THE EDGE is a 6-week coaching program for tradies, franchisees and small business owners who are ready to stop guessing and start owning their business money. We’ll help you:

✅ Set up a cash flow system
✅ Price for profit
✅ Get your BAS and tax sorted
✅ Pay yourself consistently
✅ Build a buffer
✅ Plan for growth (without working more hours)

It’s simple, structured, and built for people who are great at their trade, not spreadsheets.

Final Thoughts: Work Smarter. Get Paid Properly. Stress Less.

You didn’t go into business to work 24/7 and still worry about money.

You started your business for freedom, flexibility, and a better life. And the path to that life isn’t more work. It’s better cash flow.

So if you’re ready to take the pressure off and finally feel in control of your business money…

Join THE EDGE: 6-Week Coaching Program

Your business doesn’t need to change, it just needs a plan. Let’s build it together.

THE EDGE - 6-WEEK PROGRAM
Why Every Small Business Owner Needs a Financial Coach in Their Corner

Why Every Small Business Owner Needs a Financial Coach in Their Corner

Running a small business is no joke. You wear all the hats – CEO, marketer, customer service rep, bookkeeper, and sometimes even janitor. The freedom and flexibility of entrepreneurship are amazing, but let’s be real: it can also feel like you’re juggling flaming swords while riding a unicycle on a tightrope. And when it comes to managing money? That tightrope can feel extra wobbly.


Enter the financial coach.


While accountants and bookkeepers keep track of the numbers, a financial coach helps you understand what those numbers mean for your goals, mindset, and long-term business strategy. They’re not just here to look at your past, they’re here to help you shape your future.
Let’s break down exactly why working with a financial coach can be a total game-changer for small business owners.

1. Clarity is Power

So many business owners hustle day in and day out without a clear picture of where their money is going or how much they’re really making. A financial coach helps you:

  • Understand your cash flow
  • Track your expenses
  • Price your products/services strategically
  • Set income goals that align with your vision

When you know your numbers, you can make smarter decisions with more confidence. No more crossing your fingers and hoping there’s enough to cover next month.

Understand your cash flow

2. Mindset Matters More Than You Think

Money mindset is one of the most overlooked aspects of running a business. If you’ve got a hidden belief that you’re not “good with money” or that it’s wrong to want to be profitable, it will impact your business.

A financial coach helps you identify and rewrite those limiting beliefs so you can:

  • Raise your prices without guilt
  • Pay yourself consistently
  • Invest in growth with confidence
  • Stop playing small with your money goals

You don’t just need spreadsheets – you need support for the emotional and psychological side of money, too.

3. From Reactive to Proactive

Too many small business owners operate in reaction mode: paying bills as they come, scrambling during tax season, and constantly putting out financial fires. A financial coach helps you shift from reactive to proactive.

That means:

  • Planning for taxes year-round
  • Setting aside money for slow seasons
  • Creating a strategy to build consistent income
  • Mapping out your financial goals and the steps to get there

This isn’t just about staying afloat. It’s about building a solid, scalable foundation that supports long-term success.

4. Ditch the DIY Trap

There’s a lot of pressure on small business owners to figure everything out themselves. Google, YouTube, and online courses can only take you so far. But just like you wouldn’t expect your clients to solve all their problems without your help, you shouldn’t expect yourself to master business finances without support.

A financial coach gives you:

  • Accountability
  • Expert insights tailored to your business
  • A safe space to ask the “dumb” questions (spoiler alert: they’re never dumb)
  • A partner who’s as invested in your success as you are

5. You Deserve to be Paid Well for Your Work

Too many small business owners put themselves last on the payroll. They reinvest everything back into the business, believing that one day, it will all pay off. But guess what? You don’t have to wait to be profitable.

A financial coach helps you:

  • Create a plan to pay yourself regularly
  • Separate personal and business finances
  • Build profitability into your pricing and systems
  • Stop undercharging and undervaluing your genius

Because you didn’t start your business to just survive. You started it to thrive.

Create a plan to pay yourself regularly

6. Create a Business That Supports Your Life

Your business is a part of your life – not the other way around. A great financial coach will always bring the focus back to what you want:

  • More time with your family?
  • Travel?
  • Buying a home?
  • Debt freedom?

Whatever your version of success looks like, your financial plan should support it. A coach helps you design a business model and money strategy that aligns with your lifestyle goals.

Final Thoughts: Your Business Deserves a Financial Wingwoman (or Wingman)

You don’t have to have it all figured out. You just need the right support.

A financial coach isn’t just for people who are struggling. It’s for anyone who wants to grow with intention, take control of their finances, and build a business that actually feels good to run.

At Financial Management 101, that’s exactly what we’re here for. Whether you join our Monthly Coaching program and unlock The Vault, or dive deep into transformation through The EDGE, you’ll get the tools, clarity, and mindset shifts you need to run your business with confidence.

The Edge - 2 Hour Workshop

Let’s build your business into the financial success story it’s meant to be – one intentional step at a time.

Introducing THE EDGE. This 2-Hour Power Session is a fast-paced, simplified version of my full 6-week coaching program for self employed business owners. Click the image below to know more about what you’ll be learning in this power session.

The Vault
THE EDGE