EOFY is Over – Now What? How to Make the Most of Your Fresh Start

EOFY is Over – Now What? How to Make the Most of Your Fresh Start

The receipts are in, the spreadsheets are done, and you’ve (hopefully) high-fived your tax agent. The end of financial year (EOFY) is behind us – but what now?

For many Australians, EOFY feels like the finish line. But what if I told you it’s actually the starting line for something bigger: your financial transformation?

This fresh start isn’t just about filing taxes. It’s about taking back control, getting intentional, and building the kind of financial life that makes you feel calm, confident, and in charge.

Here’s exactly how to use the post-EOFY energy to fuel your financial success in the new year.

1. Reflect, Don’t Regret: Review Your Financial Year With Curiosity

Before you launch into new goals, pause to reflect. What worked last year? What didn’t? Where did your money actually go?

This isn’t about blame or shame. It’s about building awareness. If you don’t know your patterns, how can you shift them?

Look at:

  • Income vs. spending: Were you living within your means?
  • Savings progress: Did you build or drain your emergency fund?
  • Debt: Did it grow, shrink, or stay the same?
  • Investments: Did you start, stop, or ignore them?

Pro tip: Ask yourself: “What would I love to feel differently about my money this year?”

2. Reset Your Financial Goals (Make Them Feel Exciting!)

Generic goals like “save more money” or “spend less” don’t motivate anyone. Your goals should feel like a reward, not a punishment.

Examples:

  • Old: Save $5,000
  • New: Save $5,000 to take the family on a Bali holiday

Or:

  • Old: Pay off credit card
  • New: Clear my credit card so I can sleep better at night and finally stop stressing over bills

The more emotionally connected you are to the why, the easier it is to stay focused.

Try this:

  • Choose 1 short-term goal (within 6 months)
  • Choose 1 long-term goal (6+ months to 3 years)
  • Attach a reason and an emotion to each
Reset Your Financial Goals

3. Do a Budget Reset That Reflects the Life You Want

Forget rigid old-school budgets. Let’s talk about a spending plan that reflects your values.
Where do you want your money to go? Think beyond bills. Think joy, freedom, peace of mind. Start by:

  • Reviewing subscriptions: Are you using them all?
  • Updating your cost of living: Groceries, fuel, and utilities have changed – so should your plan
  • Adjusting categories: Maybe you’re spending more on wellness, less on takeaway

Bonus idea: Create a “Fun Fund” for guilt-free spending on the things you love. Yes, really.

4. Revisit (or Create) Your Emergency Fund

This year has already shown us how unpredictable life can be. Having a financial buffer can be the difference between stress and peace of mind.

Even $1,000 can give you breathing room. Ideally, aim for 3 months of expenses, but start small and build momentum.

Hot tip: Keep your emergency fund in a high-interest savings account you don’t touch unless it’s a genuine emergency.

5. Re-assess Your Super and Insurance

Post-EOFY is the perfect time to check in on the financial foundations you often forget about.

  • Superannuation: Are your contributions on track? Is your fund performing? Are fees eating into your future?
  • Personal insurance: Are you covered for income protection, life, or trauma? Is it still aligned with your needs?

Even a quick 20-minute review can help you spot easy wins or avoid future issues. Need help? A financial coach (like me) or adviser can guide you through these choices in plain English.
Superannuation

6. Start a New Habit (Small, Consistent Wins Add Up)

Want to save more, spend better, or build wealth? It starts with habits. Pick one new habit that supports your bigger goal. For example:

  • Transfer $50 to savings every payday
  • Spend 5 minutes a week reviewing your money
  • Read or listen to one money podcast per month
  • Tiny habits build massive momentum.

Try this: Schedule a 15-minute “money date” with yourself every week. Make it fun: coffee, music, candle, whatever makes it feel less like a chore.

7. Get Support: Don’t go it alone!

If the last financial year felt overwhelming, you don’t have to repeat that story.

Whether it’s talking to a financial coach (yep, that’s me!), joining a money challenge, or signing up for a workshop, getting support can fast-track your progress and boost your confidence.

You’re not behind. You’re not bad with money. You just haven’t had the right tools or team yet.

EOFY is Done. Your Financial Comeback Starts Now.

This new financial year is more than a date change, it’s an opportunity. You can choose to:

  • Set goals that actually excite you
  • Build a money plan that fits your real life
  • Create calm, clarity, and confidence in your finances

Ready to stop winging it and start winning it? Book your free discovery session today and let’s create a plan you can stick to, without the stress.

Your fresh start is waiting. Let’s make it count.

You survived EOFY. Now let’s help your money thrive.
Free Budgeting Spreadsheet
The Vault
The Big Picture: Why Net Position Matters More Than Budgeting

The Big Picture: Why Net Position Matters More Than Budgeting

When people think about managing their finances, budgeting is often the first thing that comes to mind. While budgeting is an essential tool, it’s only one piece of the puzzle. To truly take control of your financial life, you need to understand your net position. This bigger-picture view is the cornerstone of long-term financial success. In this blog, we’ll dive into what net position is, why it matters, and how it can transform your approach to money management.

What is Net Position?

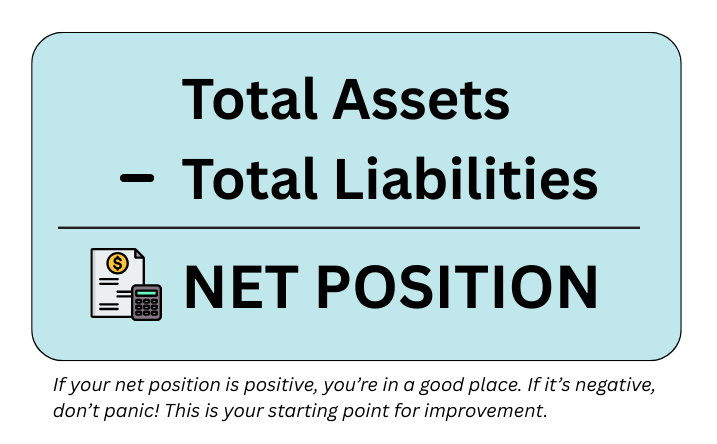
Your net position is the difference between what you own (your assets) and what you owe (your liabilities). It’s essentially your financial scorecard, giving you a snapshot of your overall financial health. Here’s a simple formula:

Net Position

Assets include things like your home, car, savings, and investments. Liabilities include mortgages, credit card debt, personal loans, and other financial obligations. Knowing your net position helps you understand whether you’re building wealth or accumulating debt.

Why Net Position Matters More Than Budgeting

Budgeting is about managing your monthly cash flow, how much money comes in and goes out. While this is important, it doesn’t give you a complete picture of your financial health. Here’s why focusing on your net position is a game-changer:

1. PROVIDES A HOLISTIC VIEW

      • Budgeting focuses on short-term goals, like paying bills or saving for a vacation. Net position shows your long-term financial standing, including the value of your assets and the weight of your debts.

2. HELPS SET REALISTIC GOALS

      • Understanding your net position allows you to set achievable financial goals, whether it’s buying a home, retiring early, or becoming debt-free.

3. REVEALS FINANCIAL TRENDS

      • Tracking your net position over time helps you see whether your financial health is improving or deteriorating.

4. GUIDES BETTER DECISION-MAKING

      • Knowing your net position helps you make informed decisions about spending, saving, and investing.

Common Misconceptions About Net Position

Budgeting is about managing your monthly cash flow, how much money comes in and goes out. While this is important, it doesn’t give you a complete picture of your financial health. Here’s why focusing on your net position is a game-changer:

1. “Only Wealthy People Need to Track Their Net Position”

      • False! Everyone, regardless of income level, can benefit from understanding their net position. It’s about knowing where you stand and where you’re headed.

2. “Budgeting Alone is Enough”

      • While budgeting is crucial for managing day-to-day expenses, it doesn’t address your overall financial health.

3. “It’s Too Complicated”

      • Tracking your net position can be as simple as listing your assets and liabilities in a spreadsheet or using a financial app.

Steps to Improve Your Net Position

1. ELIMINATE HIGH-INTEREST DEBT

      • Focus on paying off credit cards and personal loans first. These often carry the highest interest rates and can significantly impact your financial health.

2. INCREASE YOUR SAVINGS

      • Build an emergency fund with at least three to six months’ worth of living expenses. This provides a financial safety net and reduces the need for high-interest debt during emergencies.

3. INVEST WISELY

      • Grow your assets by investing in a diversified portfolio. Consider long-term investments like retirement accounts or real estate.

4. REDUCE LIABILITIES

      • Pay down loans and avoid taking on new debt unless it’s for a strategic purpose, like buying a home.

5. TRACK YOUR PROGRESS

      • Revisit your net position quarterly or annually to measure your progress and adjust your financial plan as needed.

How Our “Know Your Numbers” Course Can Help

Our “Know Your Numbers” course is designed to take the guesswork out of understanding your net position. Here’s what you’ll learn:

1. HOW TO CALCULATE YOUR NET POSITION 

      • Step-by-step guidance on listing your assets and liabilities.

2. TOOLS AND TEMPLATES

      • Access user-friendly calculators and spreadsheets to track your progress.

3. STRATEGIES FOR IMPROVEMENT

      • Learn actionable steps to grow your assets, reduce your liabilities, and increase your net worth.

4. REAL-LIFE EXAMPLES 

      • See how others have transformed their financial health by focusing on their net position.

Success Stories

1. JOAN’S TRANSFORMATION

Joan discovered her net position was negative due to high credit card debt. Using strategies from the course, she paid off her debt in two years and now has a positive net worth of $20,000.

2. PETER’S JOURNEY

Peter thought he was doing well because he had a high income. After calculating his net position, he realised his debt outweighed his assets. He’s since restructured his finances and is on track to achieve financial independence.

Know Your Numbers

Conclusion

Understanding your net position is the key to unlocking financial freedom. It’s not just about how much you earn or spend; it’s about the bigger picture of what you own versus what you owe. By focusing on your net position, you can make smarter financial decisions, set realistic goals, and build a secure future. Ready to take control? Join our “Know Your Numbers” course today and start your journey toward financial clarity and success.

The Vault
Year-End Financial Check-Up: 7 Key Steps to Close 2024 with Confidence

Year-End Financial Check-Up: 7 Key Steps to Close 2024 with Confidence

As the year wraps up, it’s time to give your finances a little TLC and prepare to start the new year strong! Think of this as your yearly financial check-up, a simple routine that sets you up for a financially fit future. Here are seven straightforward steps to help you close out 2024 with confidence.

1. Review Your Budget with Fresh Eyes

December is perfect for giving your budget a quick health check. Ask yourself:

    • Did you stick to your budget most months?
    • Are there categories where you regularly overspent?

If you find that certain areas of your budget were tough to stick to, don’t worry; you’re not alone! Make notes on what worked and what didn’t, and consider if those categories need adjusting. Next year’s budget will feel easier to manage if it aligns more closely with your actual spending patterns.

2. Evaluate Your Financial Goals for 2024

Reflect on the goals you set at the beginning of 2024. Did you aim to build an emergency fund, pay off a certain amount of debt, or save for a big purchase? Take a moment to celebrate any wins, big or small, you’ve earned it! If there were goals you couldn’t reach, try to pinpoint what might have held you back. Life happens, and sometimes, adjustments are necessary. Use these reflections to set realistic goals for 2025 that build on the progress you’ve made.

Audit Your Subscriptions and Recurring Expenses

3. Audit Your Subscriptions and Recurring Expenses

Subscriptions can sneak up on you! Take a look at all the services you’re subscribed to, streaming platforms, gym memberships, software, meal kits and decide if they’re still worth the monthly or annual fee. Ask yourself:

    • Do you use each service enough to justify the cost?
    • Are there better deals or bundles that could help you save?

Canceling or downgrading services you no longer use can free up cash you can redirect toward your savings or debt goals.

4. Set a Holiday Spending Plan

The holiday season can be a big budget-buster if you’re not careful. This December, approach holiday spending with a clear plan:

    • Set a total holiday budget and stick to it.
    • Focus on meaningful gifts within your budget and avoid last-minute splurges.
    • Consider experiences instead of material items, they often make more memorable gifts and can be cost-effective.

You’ll thank yourself in January when your credit card bills aren’t sky-high!

5. Check-in On Your Emergency Fund


Your emergency fund is your financial safety net, and December is a great time to assess its status. Ideally, you want enough to cover three to six months’ worth of essential expenses.

If your fund has been depleted due to unexpected expenses this year, make a plan to rebuild it. If it’s in good shape, well done!

Consider adding a little extra, even if it’s just a small amount each month, it’s always better to be prepared.

You want enough to cover three to six months’ worth of essential expenses on your emergency fund

5. Update Your Financial Goals for 2025

End the year by setting some intentional goals for 2025. These don’t have to be massive changes; small, achievable goals can have a big impact on your financial future. A few ideas:

    • Set a target for increasing your savings rate, even if it’s by a modest amount.
    • Commit to paying down a certain percentage of your debt.
    • Plan to invest in education or skills that could lead to higher income opportunities.

Whatever your financial goals, write them down and keep them visible. By starting now, you’ll be well-prepared to tackle them come January.

End the year by setting some intentional goals for 2025.

Final Thoughts

Closing out the year with a financial check-up is a powerful way to put yourself in the driver’s seat for 2025. These six steps are simple but effective and give you a clear view of your financial health. Here’s to closing out 2024 strong and stepping into 2025 with confidence!

Are you ready to make 2025 your breakthrough year?

MASTER YOUR MONEY is for YOU if you are tired of financial stress and ready to transform your relationship with money. Whether you’re managing a family, building your career, or chasing your dreams, this is your chance to gain the clarity, confidence, and habits you need to thrive.

This is more than a mindset shift—it’s a transformational program that puts you on the path to lasting financial success! ? Click the button below to book a call with Karen to see if this program is right for you!

Mastering Budget and Saving Techniques