Why It’s Time to Get Your Money Sorted

Why It’s Time to Get Your Money Sorted

It’s time to get real about your finances. Maybe you’ve been putting it off, hoping that things would magically improve, or that a sudden windfall might solve your problems. But deep down, you know that waiting won’t make things better. If you’re tired of feeling stressed about money, uncertain about your future, or like you’re not in control, then it’s time to take action.

Sorting out your finances is the best gift you can give yourself and your family. It might feel overwhelming at first, but with the right approach, you can take back control of your money, create a more stable financial future, and finally find the peace of mind that you deserve. So, let’s dive into why and how you should get your money sorted right now.

Why It’s Time To Get Your Money Sorted

1. Regain Control and Reduce Stress

Financial stress can impact every aspect of your life. It’s hard to sleep when you’re worried about how to pay your bills. It’s tough to enjoy your weekends when you’re constantly thinking about mounting debt or unexpected expenses. Money worries can even strain relationships and affect your overall mental health.

But imagine if you knew exactly where every dollar was going and felt confident about your financial decisions. Getting your money sorted means creating a budget that works, setting up a savings plan, and having a strategy for paying down debt. The peace of mind that comes from knowing your finances are under control is truly life-changing.

2. Achieve Your Financial Goals

Whether it’s saving for a house, planning a dream vacation, or simply building an emergency fund, financial goals are what keep us motivated. But without a clear plan, it’s easy for these goals to remain just that—dreams.

By getting your money sorted, you’ll be able to create a roadmap that takes you from where you are now to where you want to be. It’s not just about cutting back on lattes; it’s about setting realistic goals, tracking your progress, and making adjustments as needed. With a solid financial plan in place, those dreams start to feel within reach.
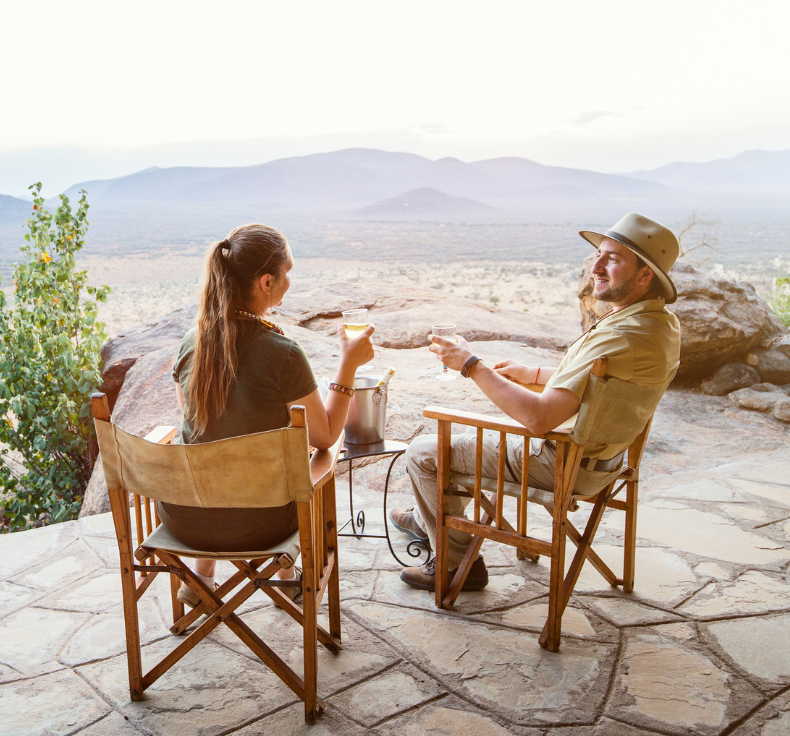
Don’t let your dream vacation remain to be “in your dreams.” Get your money sorted and achieve your financial goals one at a time!

3. Prepare for Life’s Uncertainties

Life has a way of throwing curveballs when you least expect them – job loss, medical emergencies, car repairs, you name it. Without a financial safety net, these unexpected events can send you spiraling into debt and financial uncertainty.

Building an emergency fund and establishing good money habits now means that you’ll be prepared when life doesn’t go according to plan. It’s about creating a buffer that protects you and your family when things get tough, so you don’t have to rely on credit cards or loans to get through a rough patch.
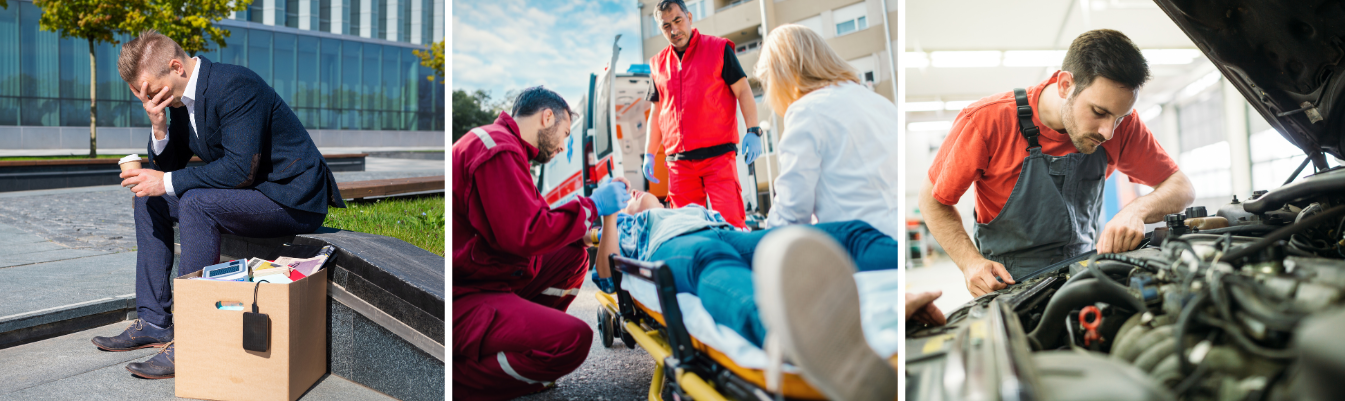
Life has a way of throwing curveballs when you least expect them - job loss, medical emergencies, car repairs, you name it.

4. Break the Cycle of Living Paycheck to Paycheck

Are you constantly counting down the days until your next paycheck? You’re not alone. Millions of people find themselves in a cycle of living paycheck to paycheck, with little to no savings and the constant pressure of making ends meet.

Sorting out your finances is the first step toward breaking this cycle. By understanding where your money goes each month and making intentional changes, you can start to build a cushion between paychecks. It’s not just about earning more; it’s about managing what you already have in a way that creates breathing room and financial stability.

How To Get Your Money Sorted

Now that you know why it’s so important to get your money sorted, let’s talk about how you can do it. The process might seem intimidating at first, but with a few simple steps, you can take control of your finances and start seeing progress.

1. Start With a Financial Snapshot

Before you can make improvements, you need to know where you stand. Start by creating a financial snapshot. Write down your income, expenses, debts, and savings. Be honest with yourself—this is your starting point. Understanding your current situation will help you identify areas where you need to make changes.

2. Create a Budget That Works for You

Budgeting isn’t about depriving yourself; it’s about making sure that your money is working toward the things that matter most to you. List out all of your monthly expenses, including fixed costs like rent or mortgage payments, utilities, and groceries, as well as discretionary spending like dining out or entertainment.

From there, set limits for each category based on your income and financial goals. The key is to find a balance that allows you to cover your needs, save for the future, and enjoy a few treats along the way. A budget should be flexible enough to adapt to your lifestyle but firm enough to keep you on track.

3. Build an Emergency Fund

Life is unpredictable, and an emergency fund is your financial safety net. Aim to save at least three to six months’ worth of living expenses in a separate account that’s easy to access but not too tempting to dip into. Start small—$1,000 is a great initial goal—and then work toward building up that cushion over time.

Having this fund in place will prevent you from resorting to high-interest debt when unexpected expenses arise, giving you peace of mind knowing that you have a financial backup plan.
4. Tackle Your Debt Strategically

Debt can feel like a heavy weight dragging you down, but it doesn’t have to be that way. List out all of your debts, including the interest rates and minimum payments. Focus on paying down high-interest debts first while making minimum payments on the others.

Once you’ve knocked out those high-interest debts, redirect those payments toward your remaining debts. This method, known as the debt avalanche, helps you save on interest and pay off your debts faster. Alternatively, if you find it more motivating, you can use the debt snowball method, starting with the smallest balances first for quick wins.

5. Automate Savings and Bills

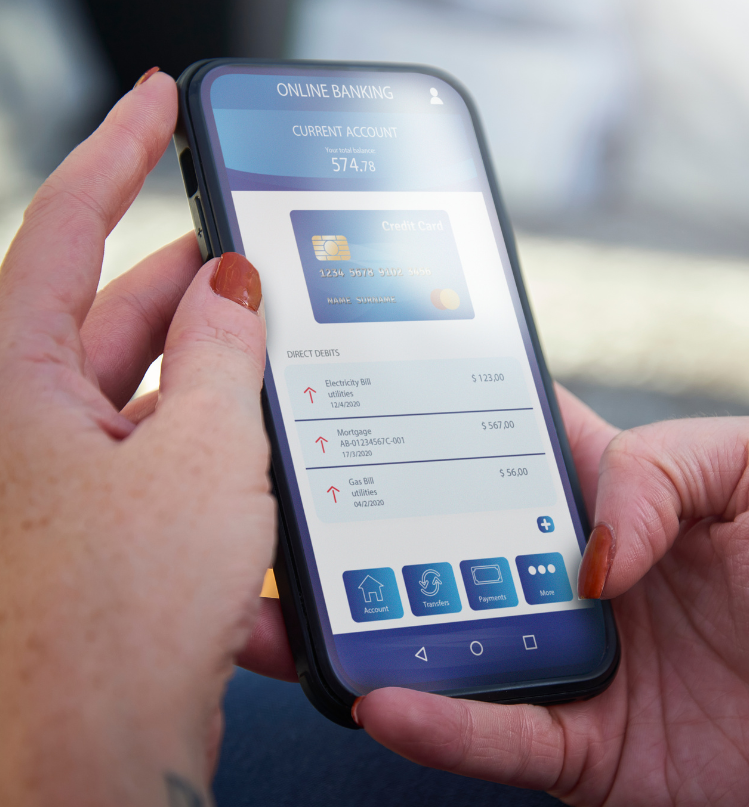
The less time you spend managing your money, the easier it is to stick to your plan. Set up automatic transfers to your savings account each month, and automate your bill payments to avoid late fees and missed payments. This way, you’re prioritizing savings before you even have a chance to spend, making it easier to reach your goals.
Automate Payments and Savings

6. Review and Adjust Regularly

Your financial situation will change over time, so it’s important to review your budget, goals, and progress regularly. Set aside time each month to go over your finances, adjust your budget if necessary, and make sure you’re on track with your goals.

This monthly check-in will keep you accountable and help you catch any issues before they become bigger problems. It’s a simple habit that can make a huge difference in your long-term success.

7. Consider Working With a Financial Coach

Sometimes, having an expert in your corner makes all the difference. A financial coach can provide personalized advice, help you navigate complex situations, and keep you accountable as you work toward your goals. With a coach’s guidance, you’ll be better equipped to make smart financial decisions, overcome challenges, and stay motivated on your journey.

Start Today for a Better Tomorrow!

It’s time to take control of your financial future. Getting your money sorted may seem like a big task, but remember, you don’t have to do it all at once. Start with small steps, focus on progress rather than perfection, and don’t be afraid to ask for help when you need it.

By taking action today, you’re investing in a future where money is a source of confidence, not stress. A future where you can enjoy life without worrying about every dollar. So, what are you waiting for? It’s time to get your money sorted and take that first step toward financial freedom.

Are you ready to take control of your money? Mastering Budgeting and Saving Techniques is a program designed to empower you to understand the importance of both budgeting and saving. 

We will explore and work through mindset shifts to empower and equip you with the tools necessary for a stress free life. This is a hands-on program with me guiding you on how to budget, track and look at managing your money like a pro.
Mastering Budget and Saving Techniques
The Financial Squeeze: Why 93% of Your Income is Gone Before You Know It and How to Take Back Control

The Financial Squeeze: Why 93% of Your Income is Gone Before You Know It and How to Take Back Control

In today’s economic landscape, many families, particularly in cities like Perth, are finding it harder to get ahead. With the cost of living rising, mortgage repayments climbing, and essential expenses consuming most of the household income, it’s no surprise that families feel financially stuck. In fact, for the average family earning around $100,000 a year in Perth, up to 93% of their income is being spent on basic living expenses and mortgage repayments. That leaves a mere 7% for everything else, whether it’s saving for an emergency, investing for the future, or even enjoying life.

So, what’s driving this financial squeeze? And more importantly, how can you start taking back control of your money, reduce financial stress, and build a path toward a more secure future? Let’s dive in.

THE BREAKDOWN — Where Does The Money Go?

If you feel like your income disappears before you even have the chance to save or plan, you’re not imagining things. For the average Perth family, a substantial portion of their income is consumed by just a few major categories.

1. MORTGAGE PAYMENTS (39.7%)

With the average house price in Perth sitting at around $690,000, a family making regular mortgage repayments is typically spending about 40% of their income just to keep a roof over their head. That’s a huge chunk of money tied up in home ownership, leaving little flexibility for other financial priorities.

2. LIVING EXPENSES (52.8%)

Next comes everyday living expenses: utilities, groceries, transportation, insurance, and other necessities. For the average family, these costs take up more than half of their monthly income. With rising prices in everything from food to fuel, these essential expenses are only getting harder to manage.

3. WHAT’S LEFT? (7.5%)

After paying for housing and general living expenses, families are left with just 7.5% of their income to cover everything else. This includes savings, emergencies, vacations, entertainment, education, and more. It’s no wonder that many people feel overwhelmed by the prospect of building an emergency fund, paying off debt, or even saving for the future.

For the average family, the costs of living expenses take up more than half of their monthly income.

Inflation directly drives up the prices of essential goods and services, from food to housing to what it costs to fill your tank so you can drive to work or put clothes on your back.

THE IMPACT — Stress, Debt, and Delayed Life Goals

This financial squeeze has significant consequences for families. When most of your income is tied up in living expenses, it’s incredibly difficult to make progress on long-term financial goals, like saving for retirement, paying off debt, or even taking that well-deserved vacation.

1. INCREASED FINANCIAL STRESS

With such a small buffer between income and expenses, any unexpected cost—a car repair, medical bill, or household emergency—can throw your entire budget off course. The constant worry about money takes a toll on mental health, relationships, and overall well-being.

2. MOUNTING DEBT

When you don’t have enough income left over for emergencies, you’re more likely to rely on credit cards or loans to cover the gaps. This can lead to a vicious cycle of debt, where interest payments eat into what little income is left, making it harder to get ahead.

Financial Stress - The constant worry about money takes a toll on mental health, relationships, and overall well-being.

3. DELAYED LIFE GOALS

Many families are forced to delay or forgo important life goals, such as buying a home, starting a family, or even saving for their children’s education. The focus is on surviving month-to-month, leaving little room for long-term planning.

HOW TO TAKE BACK CONTROL OF YOUR FINANCES

So, how can families break free from this cycle? While it may seem overwhelming, the good news is that there are concrete steps you can take to regain control of your financial situation. By being proactive and strategic, you can start to reduce financial stress, create breathing room in your budget, and move toward financial security.

1. CREATE A DETAILED BUDGET AND TRACK EVERY DOLLAR

The first step to taking control of your finances is understanding exactly where your money is going. Start by creating a detailed budget that accounts for all your expenses—both fixed (like your mortgage and utilities) and variable (like groceries and entertainment). Track every dollar to see where you might be overspending or where small changes can make a big impact.

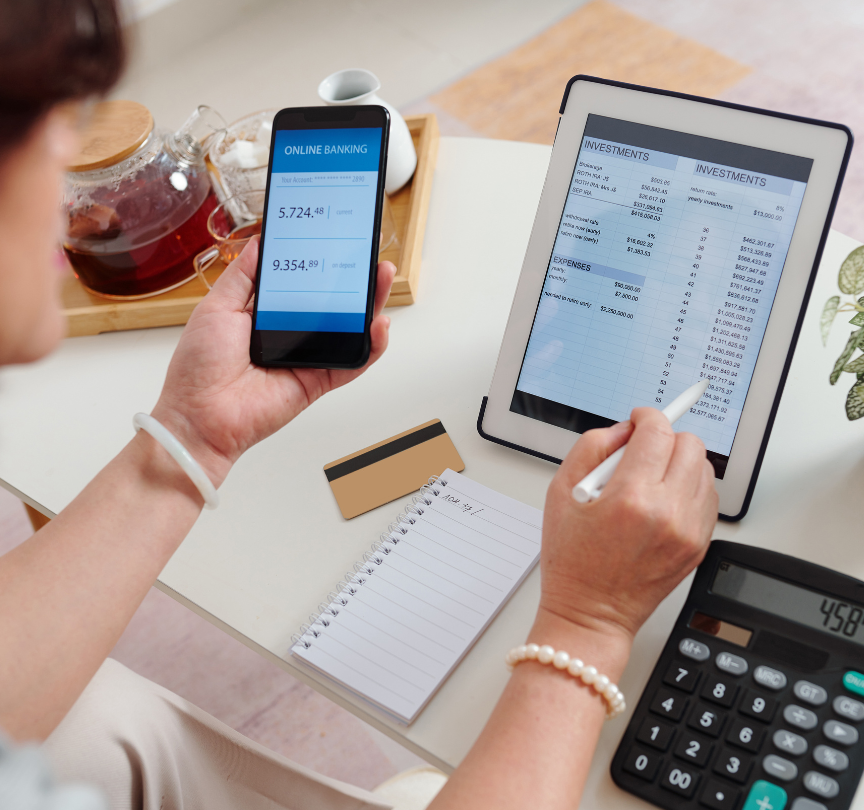
Use budgeting apps or even a simple spreadsheet to keep track of income and expenses. Once you have a clear picture of your finances, you can start making informed decisions about where to cut back or redirect funds.

Create a Detailed Budget and Track Every Dollar

2. CUT BACK ON NON-ESSENTIALS

In today’s consumer-driven world, it’s easy to get caught up in unnecessary spending. Start by evaluating your discretionary expenses—things like dining out, streaming subscriptions, and impulse purchases. While it’s important to enjoy life, small sacrifices in these areas can free up extra cash for savings or debt repayment.

Even cutting back on small expenses, like making coffee at home instead of buying it, can add up over time and create more room in your budget for the essentials.

3. REFINANCE OR RENEGOTIATE YOUR MORTGAGE

If a significant portion of your income is going toward mortgage repayments, refinancing your home loan could be a game-changer. Interest rates fluctuate, and even a small reduction in your mortgage rate can lead to significant savings over the life of the loan. Talk to your lender about refinancing options or shop around for better rates.

4. BUILD AN EMERGENCY FUND

While saving may seem impossible when so much of your income is tied up in expenses, building an emergency fund is crucial to financial security. Start small aim to save at least three to six months’ worth of living expenses. This will help you avoid relying on credit cards or loans when unexpected costs arise.

Even putting aside a small amount each month can add up over time and provide a much-needed safety net in case of emergencies.

5. INCREASE YOUR INCOME

If your current income isn’t enough to cover your expenses, it might be time to look for ways to increase it. This could mean asking for a raise at your current job, taking on a side hustle, or even exploring part-time work in a field that aligns with your skills. There are many opportunities today to monetise your talents online, whether through freelance work, selling products, or offering services.

6. PRIORITISE DEBT REPAYMENT

High-interest debt can be a major drain on your income. Focus on paying off debts with the highest interest rates first, this will save you money in the long run and free up more of your income for savings or other goals. Consider using the debt avalanche or debt snowball method to stay motivated and track your progress.

READY TO TAKE CONTROL OF YOUR FINANCES?

If you’re feeling the financial pressure, now is the time to take action. Don’t let another month go by where you feel stuck, stressed, and overwhelmed by your finances. I’m here to help you create a clear, actionable plan to take control of your money and start building a better financial future.

Join my Monthly Coaching Program, where I work one-on-one with clients to help them develop personalised budgeting strategies, eliminate debt, and build sustainable savings plans. Plus, check out my course Mastering Budgeting and Saving Techniques where I’ll teach you how to create a realistic budget that works for your family, find savings opportunities, and finally achieve financial peace of mind.
You don’t have to go through this alone together, we can turn your financial situation around. Click here to sign up for the coaching program or learn more about the course, and let’s get started on your path to financial freedom today!

By following these steps, you can start making meaningful changes in your financial life and work towards a future where you have more control, less stress, and more opportunities to get ahead. Let’s take this journey together!

Mastering Budget and Saving Techniques

Mastering Budgeting and Saving Techniques is a program designed to empower you to understand the importance of both budgeting and saving.

In this program, you will learn the fundamental concepts of how budgeting and saving is important for your financial well being.

We will explore and work through mindset shifts to empower and equip you with the tools necessary for a stress free life.

This is a hands-on program with me guiding you on how to budget, track and look at managing your money like a pro.
Which Budgeting Method is Right for You? Exploring 3 Proven Strategies

Which Budgeting Method is Right for You? Exploring 3 Proven Strategies

If you have ever wondered how to work a budget and which method is best for you, this blog post will go over three of the most popular budgeting methods that you can implement and make work for you today, allowing you to get ahead and see where your money is going.

There are three popular and proven budgeting strategies you should consider:

  1. The 50/30/20 Rule
  2. Zero Based Budgeting, and
  3. The Envelope Method

I will walk you through each of them so you can see which one is best for you and your specific financial situation.

BUDGETING METHOD – 50/30/20 RULE

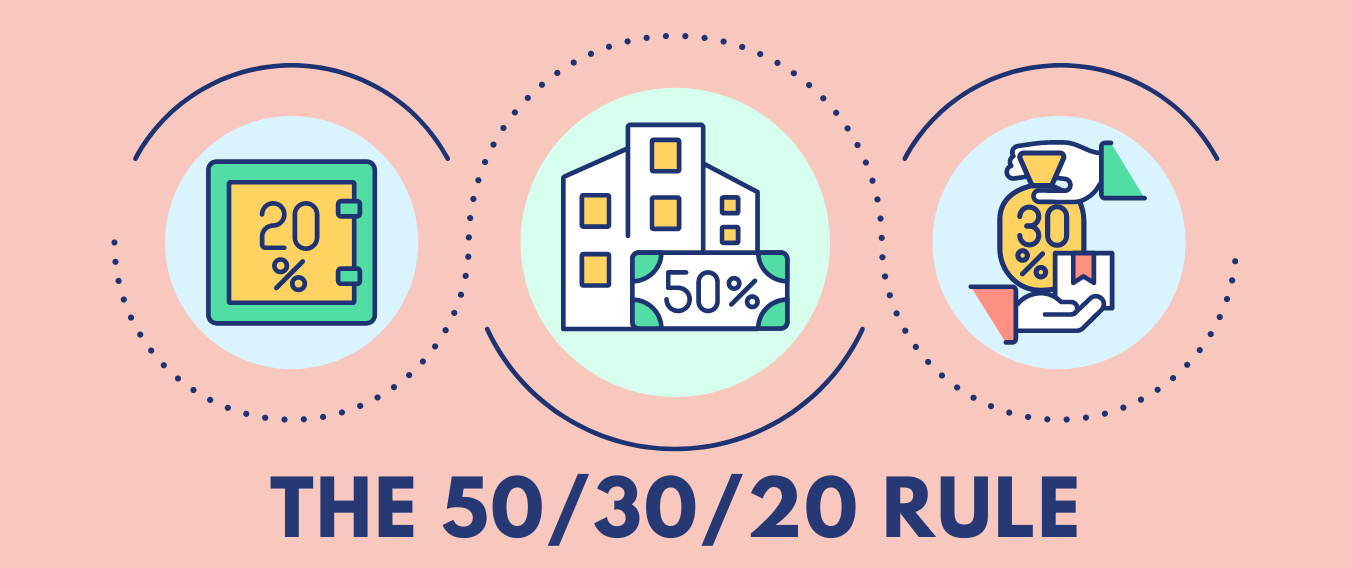
The 50/30/20 rule is a popular budgeting method that can help you allocate your income to various spending categories. It’s a straightforward and flexible guideline for managing your finances. Here’s how it works:

The 50/30/20 rule is a popular budgeting method that can help you allocate your income to various spending categories. It’s a straightforward and flexible guideline for managing your finances. Here’s how it works:

50% FOR NEEDS:

This category includes essential expenses that you must pay regularly. It covers things like housing (rent or mortgage payments), utilities (electricity, water, gas, etc.), groceries, transportation (such as car payments, insurance, and gas), minimum debt payments (like credit card minimums or student loan payments), and healthcare.

The “Needs” category should encompass no more than 50% of your after-tax income. These are the expenses that are necessary for daily living and financial stability.

30% FOR WANTS:

This category is for non-essential or discretionary spending. It includes things like dining out, entertainment, hobbies, travel, and other items or experiences that enhance your quality of life but aren’t mandatory.

The “Wants” category gives you some flexibility to enjoy life and spend on things you desire. However, it’s crucial to stay within this 30% limit to avoid overspending and maintain control over your finances.

20% FOR SAVINGS AND DEBT REPAYMENT:

The remaining 20% of your income is allocated to savings and debt repayment. This category includes savings for various financial goals like an emergency fund, retirement, a down payment on a home, or other long-term objectives. It also covers extra debt payments beyond the minimum required.

Savings are a vital part of this budgeting method. Allocating 20% of your income to savings helps you build financial security and work towards your future goals. If you have high-interest debts, consider allocating a significant portion of this 20% to debt repayment until those debts are under control.

Remember, the 50/30/20 rule is a guideline. Your actual percentages might vary depending on your unique financial situation, goals, and priorities. The key is to ensure that your spending aligns with your financial objectives and that you have a balance between covering essential expenses, enjoying life, and saving for the future.

BUDGETING METHOD – ZERO BASED BUDGETING

Zero-based budgeting is a budgeting method where you allocate your income down to zero, giving every dollar a specific purpose within your budget. In other words, you start from scratch with each budgeting period and assign every dollar you earn to an expense, savings, or debt repayment category. The goal is to ensure that your income minus your expenses equals zero. Here’s how zero-based budgeting works:

DETERMINE YOUR INCOME:

Begin by calculating your total monthly income. This includes your salary, side income, and any other sources of revenue.

LIST ALL EXPENSES:

Make a comprehensive list of all your monthly expenses. This includes both fixed expenses (like rent or mortgage, utilities, insurance, and loan payments) and variable expenses (such as groceries, transportation, dining out, and entertainment).

ALLOCATE YOUR INCOME:

Now, allocate your entire income to cover these expenses. Start with the most critical expenses, like housing, utilities, and groceries. Gradually move down the list, allocating money to each category until you’ve assigned every dollar.

TRACK YOUR SPENDING:

Throughout the month, diligently track your spending to ensure that you’re sticking to your budget. Use budgeting tools or apps to help you stay on top of your expenditures.

ADJUST AS NECESSARY:

If you find that you’ve overspent in a particular category, you’ll need to adjust your budget to cover the overage. To maintain a zero balance, you may need to reduce spending in another category.

Zero-based budgeting has several advantages:

EVERY DOLLAR HAS A PURPOSE:

This method ensures that you’re using your income efficiently and purposefully, directing your money where it matters most.

REDUCE IMPULSE BUYING:

Because every dollar must be allocated, you’re less likely to spend impulsively or frivolously.

ENCOURAGES SAVINGS AND DEBT REPAYMENT:

By including savings and debt repayment as budget categories, ZBB reinforces the importance of these financial goals.

FINANCIAL CLARITY:

It provides a clear, organised overview of your finances, making it easier to see where your money is going.

However, Zero based budgeting may not be suitable for everyone. It requires careful tracking and frequent adjustments, which can be time-consuming. Some people might prefer less detailed budgeting methods. Ultimately, the best budgeting method is the one that works for your unique financial situation and helps you reach your financial goals. Zero-based budgeting is a particularly useful tool if you want to maintain strict control over your spending and ensure that your income is allocated efficiently.

BUDGETING METHOD – THE ENVELOPE BUDGETING

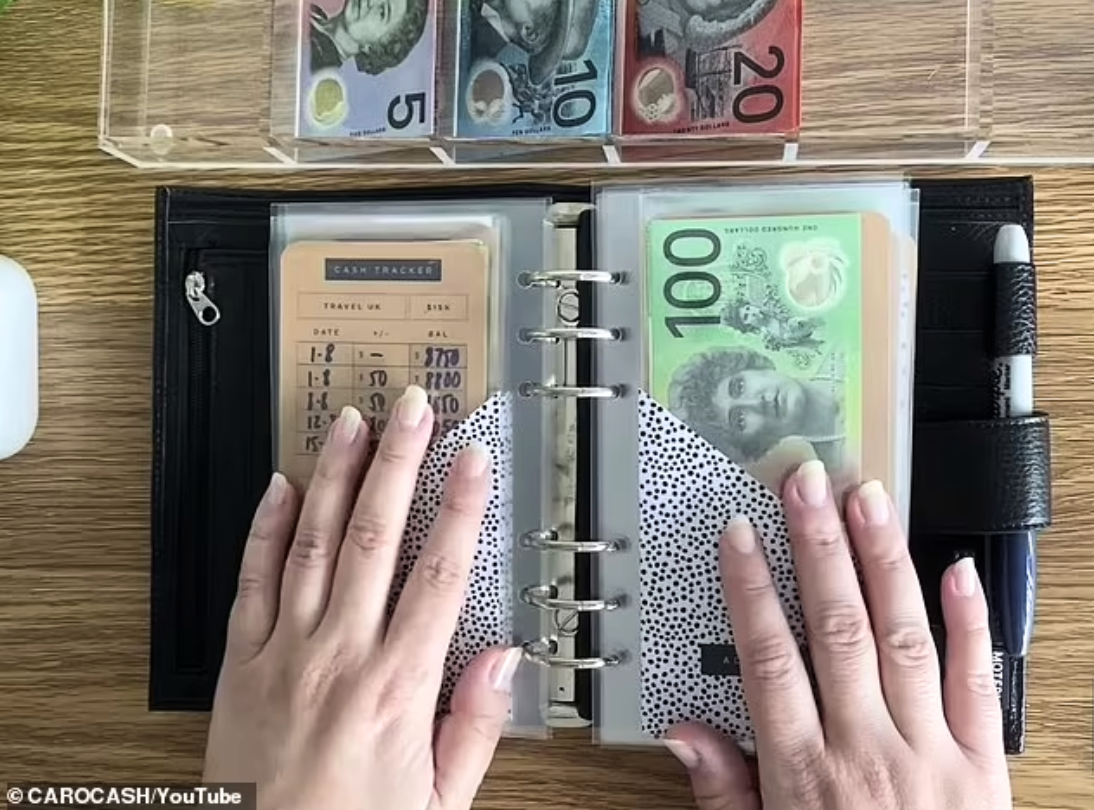
The envelope budgeting method is a cash-based budgeting system that helps you control your spending by allocating physical cash to specific categories or “envelopes” for various expenses. It’s a highly effective way to manage your finances and stay on track with your budgeting goals. However, as we’re becoming more and more a cashless society, there are ways you can still use this method via online banking and I am going to share how if you’re struggling to use cash today. Here’s how it works:

IDENTIFY YOUR SPENDING CATEGORIES:

To begin, identify the main spending categories in your budget. These categories could include groceries, dining out, entertainment, transportation, utilities, and more. Each category will have its own envelope.

DETERMINE YOUR BUDGET LIMITS:

Set a budget limit for each spending category. This is the maximum amount of cash you’ll allow yourself to spend on that category for the month. Be realistic when setting these limits to ensure they align with your overall financial goals.

CREATE PHYSICAL ENVELOPES OR USE ONLINE BANKING 

Get envelopes for each spending category. You can use actual envelopes, small pouches, or even create digital envelopes if you prefer to manage this system electronically. Label each envelope with the category name and the budgeted amount.

If you are going to use online banking, then consider using accounts like ubank or other banks that offer free transactions and multiple savings accounts that link up with a visa debit card. How this works is that the envelope category now becomes the savings account and is named as per what your paper envelope would be. Then when you need to pay for bills, you transfer the amount you need to pay into your visa debit and pay for your groceries or bills that you’ve allocated towards the envelope category. There is a video on this, so head over YouTube to see how this method is explained more clearly. Click here to WATCH THE VIDEO.

ALLOCATE CASH:

At the start of the budgeting period (usually a month), take the budgeted amount in cash for each category and place it in the respective envelope. For example, if you’ve budgeted $200 for dining out, put $200 in cash into the “Dining Out” envelope.

SPEND ONLY FROM ENVELOPES:

Throughout the month, spend only the cash from the designated envelopes for each expense category. When the cash in an envelope is depleted, that’s your signal to stop spending in that category until the next budgeting period. This physical limitation helps you avoid overspending.

RECORD YOUR TRANSACTIONS:

Keep track of your spending. Each time you spend from an envelope, make a note of the amount and the transaction in a ledger or on the envelope itself. This helps you stay accountable and provides a record of your spending. If you’re using your online banking for this, then you can clearly see and track your spending.

ROLLOVER OR ADJUST AS NEEDED:

If you have cash left in an envelope at the end of the month, you can choose to either roll it over to the next month’s budget (for that category) or use it for other financial goals, like savings or debt repayment. If you consistently have cash left over in a category, you might consider adjusting the budgeted amount for the following month.

Envelope budgeting can be particularly useful if you’re trying to curb overspending in specific categories or if you find it challenging to stick to a budget. It forces you to live within your means and prioritise your spending.

Next Step:

Choose the best budgeting method for your needs from the three options listed above.

Creating and sticking to a personal budget is an important step in effectively managing your finances. Budgeting requires discipline and commitment. Stick to your budget as closely as possible, and remember that it is a tool to help you achieve your financial goals and financial independence.

Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.

Mastering Budget and Saving Techniques

Mastering Budgeting and Saving Techniques is a program designed to empower you to understand the importance of both budgeting and saving.

In this program, you will learn the fundamental concepts of how budgeting and saving is important for your financial well being.

We will explore and work through mindset shifts to empower and equip you with the tools necessary for a stress free life.

This is a hands-on program with me guiding you on how to budget, track and look at managing your money like a pro.
Are you ready to take control of your finances and start your debt-free journey?

In this empowering 30-day course, we’ll guide you through actionable steps to help you break free from debt and achieve financial stability.

Breaking Free: Your Journey to Financial Freedom

Breaking Free: Your Journey to Financial Freedom

Hello, finance enthusiasts! Are you ready to turn the page and start a new chapter called “Financial Freedom”? If you’re between the ages of 30 and 55, you’re at a prime time in your life to make some transformative moves. Whether you’re climbing the career ladder, juggling family responsibilities, or planning for retirement, financial freedom is a goal we all share. Today, I’m here to walk you through some fun and engaging steps to achieve that sweet state of economic bliss!

STEP 1: DEFINE WHAT FINANCIAL FREEDOM MEANS TO YOU

Before we dive into the how, let’s talk about the what. Financial freedom looks different for everyone. For some, it’s about being debt-free; for others, it’s accumulating enough savings to travel the world or retire comfortably. Take a moment to really picture what financial freedom looks like for you. Is it quitting your 9 to 5 job? Is it having the resources to pursue your passions? Define it, so you can own it!

STEP 2: ASSESS YOUR CURRENT FINANCIAL SITUATION

It’s time for a little reality check (but make it fun!). Grab your favourite drink, sit down, and crunch some numbers. Look at your income, debts, savings, and expenses. Understanding where you stand financially is crucial to setting realistic goals. Use apps or spreadsheets to track your finances—seeing everything on one screen can make managing money more engaging and less daunting. I have a FREE budgeting spreadsheet that you can download, which makes it easy and quick to get a snapshot of your financial position.  Download the spreadsheet HERE. 

STEP 3: SET SMART FINANCIAL GOALS

Specific, Measurable, Achievable, Relevant, and Time-bound – these are the golden rules for goal-setting. Break your financial freedom dream into smaller, achievable milestones. Maybe you want to pay off your credit card debt in two years or save for a deposit and down payment on a home in five years. Whatever those goals may be, write them down and commit to them.

STEP 4. CREATE A BULLETPROOF BUDGET

Now, let’s craft a budget that’s as vibrant and dynamic as you are. Your budget is your blueprint to financial freedom. It should allocate funds for your necessities, savings, debts, and a little fun money too—because what’s life without a little spice? Use budgeting tools or apps to keep you on track and make adjustments as your financial situation evolves.  As mentioned earlier in this blog, you can download the spreadsheet HERE.

STEP 5: BUILD AN EMERGENCY FUND

Life loves to throw curveballs, and sometimes they hit us right in the wallet. An emergency fund acts as a financial safety net. Start by saving enough to cover at least three to six months’ worth of living expenses. This fund will protect you from unforeseen circumstances like medical emergencies, urgent home repairs, or unexpected job loss. 

STEP 6: ELIMINATE AND MANAGE DEBT

Debt can be a heavy chain holding you back from your freedom. Focus on paying off high-interest debts first, such as credit card balances or personal loans. Consider strategies like the debt snowball or avalanche methods. Remember, every payment is a step closer to your financial liberation.

Life’s unexpected financial challenges can catch us off guard. Having an emergency fund can provide a safety net to help cover these unforeseen costs without the need to go into debt or disrupt long-term financial goals.

STEP 7: INCREASE YOUR INCOME

Sometimes cutting expenses isn’t enough to achieve your financial goals quickly. Look for ways to boost your income. Could you ask for a raise, change jobs for a higher salary, or start a side hustle? Maybe now’s the time to turn your hobby into a profit-making venture!

STEP 8: INVEST IN YOUR FUTURE

Investing can be a game-changer in your journey to financial freedom. Research different investment options like stocks, bonds, mutual funds, or real estate. Consider speaking with a financial advisor first before investing to tailor an investment strategy that suits your risk tolerance and financial goals.

STEP 9: STAY EDUCATED AND ADAPT

The financial world is always evolving, and so should your strategies. Keep learning, read books, attend workshops, follow my blogs, and join my community of like-minded individuals via the Learning Hub or Monthly Coaching. The more you know, the better equipped you’ll be to make informed financial decisions.

STEP 10: CELEBRATE YOUR PROGRESS

Don’t forget to celebrate your victories, big or small. Achieving financial freedom is a journey, not a sprint. Set up little rewards for yourself as you hit milestones. This not only makes the process enjoyable but also keeps you motivated.

CONCLUSION

Remember, financial freedom isn’t about having lots of money; it’s about having choices. It’s about living your life on your terms. So, let’s raise our glasses (of budget-friendly wine, of course!) to a brighter, financially free future. 

Here’s to making smart choices, being strategic, and having fun along the way. You’ve got this!

Take Control of Your Finances Today!

Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.

Mastering Budget and Saving Techniques
Using Your Talents to Accelerate Debt Repayment

Using Your Talents to Accelerate Debt Repayment

One of the most effective ways to speed up your debt-free journey is to increase your earnings. While cutting expenses is essential, there’s only so much you can save. On the other hand, boosting your income has virtually no upper limit. And the best way to do this? By leveraging your unique skills and talents. In this post, we’ll explore creative ways to monetise what you’re already good at to generate extra income and pay down your debt faster.

1. IDENTIFY YOUR MARKETABLE SKILLS

Everyone has skills that others find valuable. These could be professional skills like writing, graphic design, or coding, or personal talents like cooking, crafting, or fitness coaching. The first step is to identify what skills you have that can be monetised.

Action Step:
Make a list of all your skills—both professional and personal. Next to each skill, brainstorm how you could offer this as a service or product to others.

2. OFFER FREELANCE OR CONSULTING SERVICES

Freelancing is a flexible way to turn your professional skills into an income stream. Whether it’s writing, graphic design, web development, or marketing. There’s a demand for almost every skill set online.

Action Step:
Create profiles on popular freelance platforms like Upwork, Fiverr, or Freelancer. Start with a competitive rate to build your portfolio and reputation. As you gain experience and positive reviews, increase your rates.

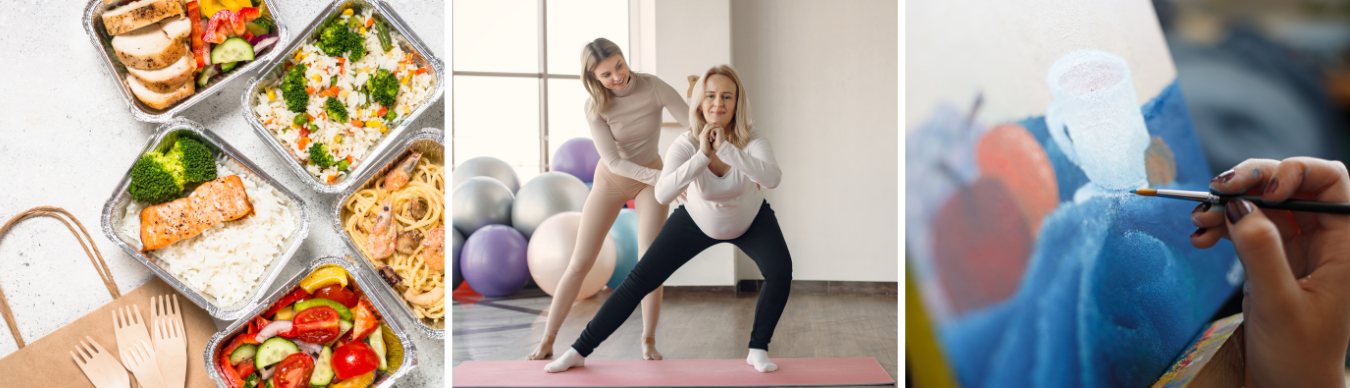
Starting a side hustle can be a great way to turn your passions into income. Offer catering services for events or meal prep for busy individuals. Host yogaclasses at local community centres or online. Create custom and commissioned artwork for clients.

3. START A SIDE-HUSTLE BASED ON YOUR PASSION

If you’re passionate about something, chances are you’re good at it—and people are willing to pay for it. This could range from tutoring, personal training, photography, or even starting a blog or YouTube channel about a niche topic you love.

Action Step:
Identify a passion you can turn into a side hustle. Research how others in the field monetize their passion, and develop a simple business plan to start.

4. TEACH WHAT YOU KNOW

If you have expertise in a particular area, consider teaching others. This could be through online courses, workshops, or even one-on-one tutoring sessions. The e-learning market is booming, and platforms like Udemy, Teachable, and Skillshare make it easier than ever to reach a global audience.

Action Step:
Outline a course or workshop you could teach based on your expertise. Create a simple curriculum and start by offering free webinars or low-cost classes to gauge interest.

5. MONETISE YOUR HOBBIES

Hobbies like photography, crafting, baking, or gardening can be turned into profitable side businesses. For instance, if you’re into photography, you could sell prints online or offer portrait sessions. If you love crafting, consider opening an Etsy shop or participating in local craft fairs.

Action Step:
Identify a hobby you could monetise. Research how others have successfully turned similar hobbies into businesses and consider starting small—like selling at a local market or online.

6. WRITE AND SELF-PUBLISH A BOOK OR AN EBOOK

If you have expertise or a story to share, consider writing a book or e-book. Platforms like Amazon Kindle Direct Publishing (KDP) make it easy to self-publish and reach a wide audience. Whether it’s a how-to guide, a cookbook, or a fiction novel, there’s a market for almost every genre.

Action Step:
Outline a book or e-book idea that leverages your knowledge or storytelling ability. Write a few chapters and seek feedback. Once ready, self-publish and promote it through social media and online communities.

7. OFFER VIRTUAL SERVICES OR COACHING

The virtual world offers endless opportunities for monetising your skills. If you’re a great communicator, consider coaching or consulting via Zoom or Skype. This could be life coaching, career coaching, language tutoring, or even virtual fitness training.

Action Step:
Choose a virtual service that aligns with your skills. Set up a simple website or social media page to promote your services. Offer a few free sessions to gather testimonials and refine your approach.

8. CREATE A MEMBERSHIP OR SUBSCRIPTION SERVICE

If you have a skill or knowledge that requires ongoing support or regular updates, consider creating a membership or subscription service. This could be a monthly subscription box for handmade goods, an exclusive online community, or a members-only blog with premium content.

Action Step:
Identify a service or product that could be offered on a subscription basis. Develop a pricing model and launch a beta version to test the market.

9. SELL DIGITAL PRODUCTS

Digital products like printables, e-books, templates, or courses have high-profit margins and low overhead costs. Once created, they can be sold repeatedly, generating passive income over time.

Action Step:
Develop a digital product related to your skill or passion. Use platforms like Etsy, or your own website to sell and promote the product.

10. PARTICIPATE IN THE GIG ECONOMY

Consider participating in the gig economy if you’re looking for flexible, quick income opportunities. Driving for Uber, delivering groceries with Instacart, or doing odd jobs with Airtasker or hipages are all options that allow you to set your schedule.

Action Step:
Sign up for a gig economy platform that aligns with your availability and interests. Use the income from these gigs specifically to pay down debt.

11. LEVERAGE YOUR SOCIAL MEDIA PRESENCE

If you have a strong social media presence or are willing to build one, you can leverage this platform to promote affiliate products, partner with brands, or even sell your products and services. Influencer marketing is a lucrative option for those who can build a dedicated following.

Action Step:
Choose a social media platform that aligns with your target audience. Start creating valuable content consistently and explore monetisation options as your following grows.

12. NETWORK AND COLLABORATE

Networking and collaborations can open up new income opportunities. Reach out to others in your field or related industries to see how you can collaborate on projects, cross-promote each other’s services, or even share clients.

Action Step:
Join professional groups or online communities related to your skill. Engage actively, offer help, and look for collaboration opportunities.

Conclusion: Stay Ahead of the Game

Leveraging your talents to create additional income streams can significantly accelerate your debt payoff journey. The key is to think creatively about how you can monetise what you already know and do well. Remember, there’s no single right way to do this—experiment with different ideas, see what works best, and scale up from there. With consistent effort and a bit of creativity, you’ll be on your way to becoming debt-free in no time.

Learn the fundamental concepts of how budgeting and saving are important to your financial well-being. Registration is now open for the course: Mastering Budget and Saving Techniques. This is a hands-on course with me guiding you on how to budget, track and look at managing your money like a pro.
Take Control of Your Finances Today!

Are you tired of living paycheck to paycheck? Do you want to make smarter financial decisions but don’t know where to start? This monthly financial coaching program is designed to help you take control of your finances and achieve your financial goals.

As your financial coach, Karen will teach you how to build financial muscle, so that you have money working to your advantage and not to your bank or financial institution’s benefit. Click here to enrol!

Are you ready to take control of your finances and start your debt-free journey?

In this empowering 30-day course, we’ll guide you through actionable steps to help you break free from debt and achieve financial stability.