Budgeting Without Deprivation: Why Your Budget Isn’t Working (Yet!)

Budgeting Without Deprivation: Why Your Budget Isn’t Working (Yet!)

Raise your hand if you’ve ever tried to stick to a budget…

…only to find yourself breaking it faster than you can say “unexpected Amazon purchase.”

Yep, I see you. And you’re not alone.

Budgets have gotten a bad rap over the years.

For many people, the word “budget” feels about as appealing as:

  • Giving up your daily coffee runs.
  • Saying “no” to dinners out with friends.
  • Counting every single penny and feeling like you’re constantly falling short.

But here’s the truth nobody talks about:

Your budget isn’t failing because you’re bad with money.

It’s likely failing because it wasn’t built to work for you in the first place. Today, I’m going to show you:

  • Why most budgets backfire (and it has nothing to do with willpower).
  • How to reframe budgeting as a freedom tool – not a punishment.
  • My favorite tips to create a budget that actually sticks (without feeling deprived!).

By the end of this post, you’ll feel empowered to take control of your money in a way that feels personal, realistic, and – dare I say it – fun. Ready? Let’s dive in.

? The Real Reason Most Budgets Fail

Here’s the million-dollar question:

Why do so many budgets start with excitement… but crash and burn within weeks?

Simple:

Most people create budgets from a place of restriction, not intention.

Think about it.

When people sit down to “get serious” about money, they often whip out a budgeting app or spreadsheet and immediately start slashing everything they love:

  • No more takeout.
  • No more fun shopping.
  • No more travel.

It’s like putting your money on a crash diet. And just like a crash diet, it’s unsustainable. You might stick with it for a week or two. Maybe even a month. But eventually, you’ll start to feel suffocated. Deprived. Frustrated.

And then? You rebel.

Suddenly, you’re splurging on things you “shouldn’t” buy, feeling guilty, and thinking, “I just suck at budgeting.”

Sound familiar?

? Why Budgeting Doesn’t Have to Feel Like Deprivation

Here’s the mindset shift that changes everything: Your budget isn’t a punishment. It’s a permission slip.

Let me say that again, louder for the people in the back: Your budget is a tool that gives you permission to spend on what truly matters to you.

Budgeting isn’t about cutting everything out of your life. It’s about:

  • Getting clear on your values.
  • Prioritising what brings you joy and security.
  • Being intentional with every dollar.

It’s the ultimate act of self-respect and self-care. Because when you create a budget that aligns with your goals, you’re telling yourself: “I trust myself with money. I’m creating a life that feels good today and tomorrow.”

    Your budget isn’t a punishment. It’s a permission slip.

    Your budget isn’t a punishment. It’s a permission slip. Your budget is a tool that gives you permission to spend on what truly matters to you.

    ✨ The 3 Most Common Budget Mistakes (And How to Fix Them!)

    Let’s get specific. Here are the biggest budgeting mistakes I see over and over and how you can fix them starting today.

    Mistake #1: You’re Budgeting for a Fantasy, Not Your Real Life

    So many people create their budget based on what they wish their life looked like, not how they actually live. You might be thinking:

    • “I’ll just cut my grocery spending in half.”
    • “I’ll stop eating out completely.”
    • “No more personal spending for the next three months!”

    But here’s the problem:

    • You still have to eat.
    • You still want to enjoy your life.
    • You’re not going to suddenly become a minimalist monk overnight.

    Solution: Budget for your real life, not your fantasy version.

    Ask yourself:

    • What are my non-negotiables? (Coffee, takeout, hobbies, etc.)
    • Where am I willing to cut back (for now)?
    • How can I adjust slowly instead of all at once?

    Mistake #2: You’re Not Building in Flexibility

    Life happens. Unexpected expenses come up. Surprise celebrations pop onto the calendar. Your car decides to remind you it needs repairs (usually at the worst possible time).

    Most budgets fail because they’re too rigid. Every dollar is assigned perfectly… until reality hits.

    Solution: Build in buffer zones.

    In your budget, always include:

    • A miscellaneous category for unexpected expenses.
    • A “fun money” allowance—even if it’s small—to spend guilt-free.
    • A savings cushion for bigger unexpected costs over time.

    This way, your budget can bend without breaking.
    Tie every budgeting choice to a goal that lights you up.

    ? How to Create a Budget You’ll Actually Stick To (Without Feeling Deprived)

    Let’s get into the practical part! Here’s my step-by-step process for creating a feel-good, flexible, empowering budget that works for real people with real lives.

    Step 1: Know Your Numbers (Without Shame!)

    You can’t improve what you don’t measure. Start by gathering:

    • Your monthly income (after taxes).
    • Fixed expenses (rent, utilities, insurance, subscriptions).
    • Variable expenses (groceries, gas, dining out, etc.).
    • Minimum debt payments.

    Remember, this isn’t about judging yourself. It’s about getting honest with where you’re at.

    Step 2: Identify Your Financial Priorities

    Ask yourself:

    • What matters most to me right now?
    • Which goals am I working toward over the next 3–6 months?

    Examples:

    • Paying off credit card debt.
    • Saving for a vacation.
    • Building an emergency fund.

    Rank them in order of importance.

    Step 3: Allocate Your Income (The Empowered Way!)

    Now it’s time to assign your dollars. Start with this simple formula:

    • Fixed Expenses – Cover your essentials first.
    • Savings & Debt Goals – Direct money toward your top priorities.
    • Variable Expenses – Budget realistically for your daily life.
    • Fun Money & Flex Funds – Yes, this is non-negotiable!

    Every dollar should have a job, but make sure some of those jobs bring you joy!

    Step 4: Automate Where You Can

    Take the mental work out of budgeting by automating:

    • Bill payments
    • Minimum debt payments
    • Savings contributions (even small ones!)

    Automation reduces decision fatigue and makes it easier to stay on track.

    Step 5: Check In Weekly (Not Just Monthly!)

    Most people only check their budget once a month… or never. That’s like driving with your eyes closed until you crash. Instead, commit to a weekly money date with yourself.

    Ask:

    • What went well this week?
    • Where did I overspend or underspend?
    • Do I need to adjust anything for the week ahead?

    This keeps you engaged and in control, without feeling overwhelmed.

    ? Yes, You Can Still Have Lattes and Takeout (Here’s How!)

    Let’s address the elephant in the room. Do you have to give up your favorite things to succeed financially? Absolutely not.

    Here’s the trick:

    • Budget for them intentionally.
    • Scale back elsewhere if needed.
    • Enjoy them guilt-free.

    Maybe that means fewer takeout nights… but keeping your Friday sushi ritual. Maybe it means making coffee at home most days… but savoring your weekend café visits.

    It’s about balance, not restriction.
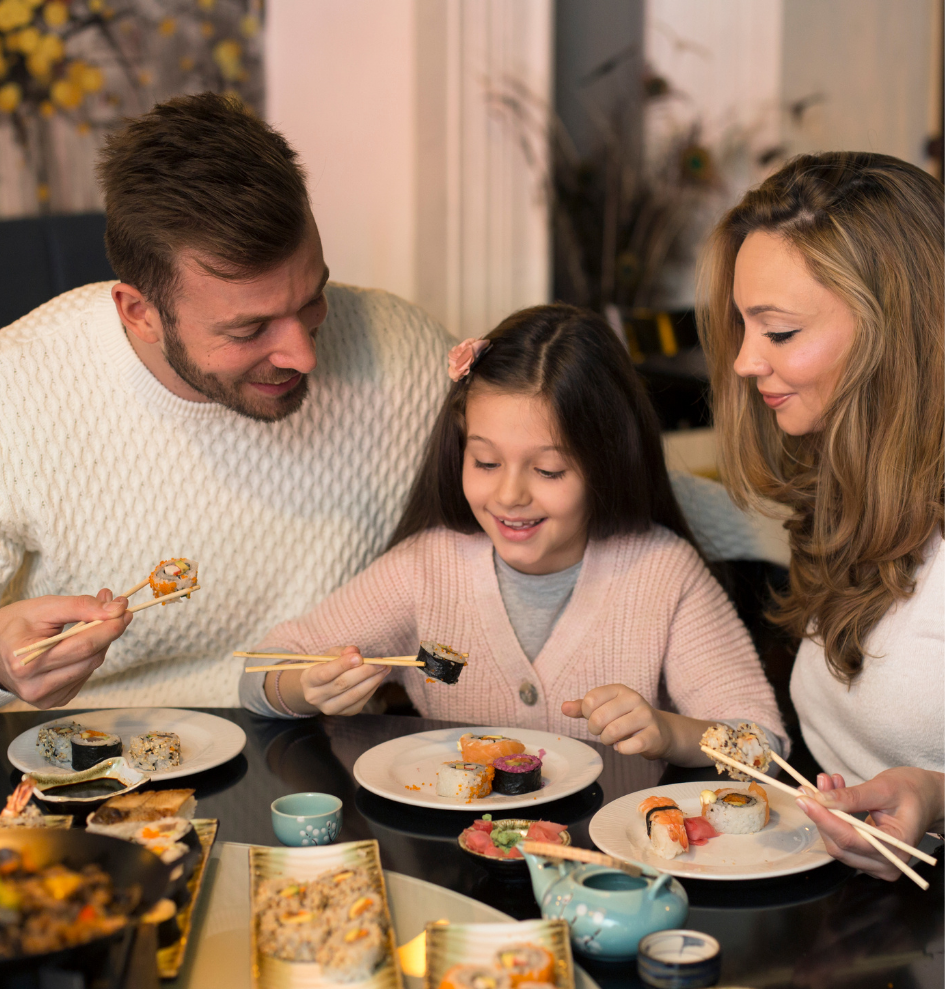
    You can still keep your Friday sushi ritual with the fam!

    If you budget intentionally, you can still keep your Friday sushi ritual with the fam without the guilt!

    It’s about balance, not restriction.

    ? How This Ties Into the Your Financial Freedom Breakthrough™ – 90 Day Money Makeover

    This is exactly why I spend a full section of my Your Financial Freedom Breakthrough™ – 90 Day Money Makeover guiding people through budgeting in a whole new way. We don’t just talk numbers – we talk values:

    • What makes you feel secure?
    • What experiences light you up?
    • How can your money fuel the life you want, both today and in the future?

    You’ll learn how to:

    • Build a flexible budget that supports your goals.
    • Ditch the guilt around spending.
    • Create a money plan that feels empowering—not restrictive.

    And the best part? You’ll have support, accountability, and expert guidance every step of the way.

    ? Ready to Take the First Step? (Mini Challenge!)

    Here’s a quick exercise to get you started today:

    The Budget Clarity Challenge:

    • Write down your top 3 financial goals for the next 90 days.
    • Review your last month of spending (no judgment!).
    • Highlight every purchase that didn’t align with your goals.

    Ask yourself:

    What can I adjust next month to better support my goals, without cutting out everything I enjoy?

    Choose one small change you’ll make this week. This simple process can open your eyes to how you’re currently spending, and show you just how much power you have to shift it.

    ? Final Thoughts: Budgeting Is About Freedom, Not Frustration

    Here’s what I want you to remember:

    Budgeting isn’t about deprivation – it’s about designing a life you love. Your money can support your dreams, your joy, and your future security – all at the same time.

    You don’t need to be “perfect” with your budget. You just need to stay consistent and flexible.

    And if you’re ready to dive deeper into this work, to finally build a money system that sticks – keep your eyes open. My Your Financial Freedom Breakthrough™ – 90 Day Money Makeover program opens for enrollment on September 10th.

    Together, we’ll build a budget that works with your life, not against it, and set you up for financial freedom that lasts.
    Your Financial Freedom Breakthrough™ - 90 Day Money Makeover
    From Chaos to Clarity: How to Create a Money Plan That Actually Works

    From Chaos to Clarity: How to Create a Money Plan That Actually Works

    Ever feel like your money is running you instead of the other way around? Like no matter how much you earn, there’s always more month than money?

    If you nodded (or sighed), you’re not alone. The good news? You don’t need a finance degree, a six-figure income, or a strict budget to take control. You just need a money plan that works for you.

    In this blog, we’ll ditch the overwhelm and walk through exactly how to create a simple, empowering money plan that gives you clarity, confidence, and real momentum.

    Let’s go from chaos to clarity – starting today.

    1. Start With Your “Why”: Anchor Your Money to What Matters

    Before we dive into numbers, let’s get clear on your why. Because unless your money plan connects to something meaningful, it won’t stick.

    Ask yourself:

    • What would feeling in control of my money allow me to do?
    • What does financial peace look like to me?
    • What am I working toward?

    Your answers might include:

    • Paying off debt to sleep better at night
    • Saving for a dream trip or home deposit
    • Creating options so you can work less or start a business

    Write your top 2 – 3 motivations down. These are your compass when the budget feels boring or things go off track.

    2. Know Your Numbers (Without the Shame Spiral)

    You can’t improve what you don’t measure. So let’s get honest, not harsh. Gather the basics:

    • Your income (all sources)
    • Your recurring bills
    • Your debt repayments
    • Your spending patterns (groceries, eating out, transport, etc.)
    • Your current savings and investments

    Pro tip: Use the last 2–3 months of bank statements to see where your money actually went. You might be surprised (hello, Uber Eats). This isn’t about judgment. It’s about clarity.

    3. Create a Simple Money Plan (The 70/20/10 Rule)

    Forget complicated budgets with 47 categories. Here’s a simple, flexible formula you can actually stick to:

    • 70% for living: rent/mortgage, groceries, transport, lifestyle
    • 20% for financial goals: savings, debt repayments, investments
    • 10% for the future: extra super, long-term wealth building

    The percentages aren’t set in stone. Adjust based on your situation. The key is having a structure that makes sure you’re not spending 100% of your income with nothing left to show for it.

    Action step: Plug your own numbers into this formula and see where you land. If you’re off track, that’s your roadmap for change.

    Create a Simple Money Plan

    4. Automate Your Money Flow (And Take the Stress Out)

    Once you know where your money should go, make it happen on autopilot.
    Set up automatic transfers:

    • To a separate savings account (nickname it for motivation: “Italy 2026” or “Debt-Free Me”)
    • To cover bills and direct debits
    • To long-term savings or investment accounts

    When you automate, you eliminate the willpower game. You’ll save without thinking and avoid last-minute money panic.

    Bonus tip: Use a separate account for discretionary spending (like a digital “cash envelope”). When it’s empty, it’s empty.

    5. Create an Emergency Buffer (For Life’s “Oh No!” Moments)

    Life is full of surprises. Your washing machine breaks, your car needs fixing, or your job suddenly changes.

    Having even $1,000 in a buffer fund means you don’t have to reach for the credit card every time life happens.

    Aim for 1 month of essential expenses first, then build to 3. But start where you are, every $50 counts. Keep it in a separate high-interest savings account you can access in a true emergency (not Friday night online shopping).

    6. Track Progress Without Obsessing

    You don’t need to check your bank app five times a day. But regular check-ins keep you engaged and help you spot problems early.

    Ideas to stay on track:

    • Weekly money date: review transactions, check balances, update goals
    • Monthly review: celebrate wins, adjust if needed

    Use a simple app or spreadsheet to track goals

    The goal isn’t perfection. It’s progress.

    7. Keep Learning and Stay Inspired

    Your relationship with money is lifelong. The more you understand it, the more confident you’ll feel. Try:

    • Reading a finance book this quarter
    • Listening to a weekly money podcast
    • Following finance educators on socials
    • Booking a session with a financial coach to personalise your plan

    There’s no shame in not knowing something – only in staying stuck.

    Clarity = Confidence = Momentum

    When your money feels chaotic, it can affect everything: your stress levels, your sleep, your relationships, and your ability to plan ahead. But creating a money plan that actually works isn’t about spreadsheets or sacrifice. It’s about:

    • Getting clear on what matters to you
    • Creating a simple, sustainable system
    • Building habits that support your goals

    And the best part? You can start today. One step. One decision. One plan.

    If you’re ready to get out of the fog and into financial clarity, let’s talk. Book your free discovery call and let’s map out your next steps – with zero jargon, zero judgment, and 100% support.

    Because you can feel good about your money. You just need a plan that fits your life.

    No more chaos. It’s your time for clarity. Let’s make it happen.

    Mastering Budgeting and Saving
    The Vault
    EOFY is Over – Now What? How to Make the Most of Your Fresh Start

    EOFY is Over – Now What? How to Make the Most of Your Fresh Start

    The receipts are in, the spreadsheets are done, and you’ve (hopefully) high-fived your tax agent. The end of financial year (EOFY) is behind us – but what now?

    For many Australians, EOFY feels like the finish line. But what if I told you it’s actually the starting line for something bigger: your financial transformation?

    This fresh start isn’t just about filing taxes. It’s about taking back control, getting intentional, and building the kind of financial life that makes you feel calm, confident, and in charge.

    Here’s exactly how to use the post-EOFY energy to fuel your financial success in the new year.

    1. Reflect, Don’t Regret: Review Your Financial Year With Curiosity

    Before you launch into new goals, pause to reflect. What worked last year? What didn’t? Where did your money actually go?

    This isn’t about blame or shame. It’s about building awareness. If you don’t know your patterns, how can you shift them?

    Look at:

    • Income vs. spending: Were you living within your means?
    • Savings progress: Did you build or drain your emergency fund?
    • Debt: Did it grow, shrink, or stay the same?
    • Investments: Did you start, stop, or ignore them?

    Pro tip: Ask yourself: “What would I love to feel differently about my money this year?”

    2. Reset Your Financial Goals (Make Them Feel Exciting!)

    Generic goals like “save more money” or “spend less” don’t motivate anyone. Your goals should feel like a reward, not a punishment.

    Examples:

    • Old: Save $5,000
    • New: Save $5,000 to take the family on a Bali holiday

    Or:

    • Old: Pay off credit card
    • New: Clear my credit card so I can sleep better at night and finally stop stressing over bills

    The more emotionally connected you are to the why, the easier it is to stay focused.

    Try this:

    • Choose 1 short-term goal (within 6 months)
    • Choose 1 long-term goal (6+ months to 3 years)
    • Attach a reason and an emotion to each

    Reset Your Financial Goals

    3. Do a Budget Reset That Reflects the Life You Want

    Forget rigid old-school budgets. Let’s talk about a spending plan that reflects your values.
    Where do you want your money to go? Think beyond bills. Think joy, freedom, peace of mind. Start by:

    • Reviewing subscriptions: Are you using them all?
    • Updating your cost of living: Groceries, fuel, and utilities have changed – so should your plan
    • Adjusting categories: Maybe you’re spending more on wellness, less on takeaway

    Bonus idea: Create a “Fun Fund” for guilt-free spending on the things you love. Yes, really.

    4. Revisit (or Create) Your Emergency Fund

    This year has already shown us how unpredictable life can be. Having a financial buffer can be the difference between stress and peace of mind.

    Even $1,000 can give you breathing room. Ideally, aim for 3 months of expenses, but start small and build momentum.

    Hot tip: Keep your emergency fund in a high-interest savings account you don’t touch unless it’s a genuine emergency.

    5. Re-assess Your Super and Insurance

    Post-EOFY is the perfect time to check in on the financial foundations you often forget about.

    • Superannuation: Are your contributions on track? Is your fund performing? Are fees eating into your future?
    • Personal insurance: Are you covered for income protection, life, or trauma? Is it still aligned with your needs?

    Even a quick 20-minute review can help you spot easy wins or avoid future issues. Need help? A financial coach (like me) or adviser can guide you through these choices in plain English.

    Superannuation

    6. Start a New Habit (Small, Consistent Wins Add Up)

    Want to save more, spend better, or build wealth? It starts with habits. Pick one new habit that supports your bigger goal. For example:

    • Transfer $50 to savings every payday
    • Spend 5 minutes a week reviewing your money
    • Read or listen to one money podcast per month
    • Tiny habits build massive momentum.

    Try this: Schedule a 15-minute “money date” with yourself every week. Make it fun: coffee, music, candle, whatever makes it feel less like a chore.

    7. Get Support: Don’t go it alone!

    If the last financial year felt overwhelming, you don’t have to repeat that story.

    Whether it’s talking to a financial coach (yep, that’s me!), joining a money challenge, or signing up for a workshop, getting support can fast-track your progress and boost your confidence.

    You’re not behind. You’re not bad with money. You just haven’t had the right tools or team yet.

    EOFY is Done. Your Financial Comeback Starts Now.

    This new financial year is more than a date change, it’s an opportunity. You can choose to:

    • Set goals that actually excite you
    • Build a money plan that fits your real life
    • Create calm, clarity, and confidence in your finances

    Ready to stop winging it and start winning it? Book your free discovery session today and let’s create a plan you can stick to, without the stress.

    Your fresh start is waiting. Let’s make it count.

    You survived EOFY. Now let’s help your money thrive.

    Free Budgeting Spreadsheet
    The Vault