The Big Picture: Why Net Position Matters More Than Budgeting

The Big Picture: Why Net Position Matters More Than Budgeting

When people think about managing their finances, budgeting is often the first thing that comes to mind. While budgeting is an essential tool, it’s only one piece of the puzzle. To truly take control of your financial life, you need to understand your net position. This bigger-picture view is the cornerstone of long-term financial success. In this blog, we’ll dive into what net position is, why it matters, and how it can transform your approach to money management.

What is Net Position?

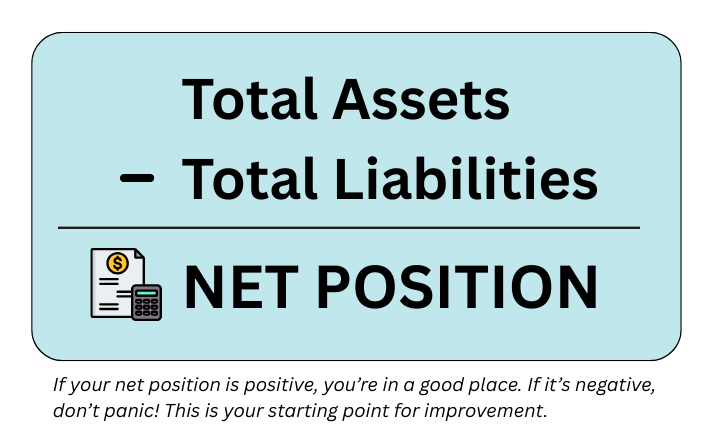
Your net position is the difference between what you own (your assets) and what you owe (your liabilities). It’s essentially your financial scorecard, giving you a snapshot of your overall financial health. Here’s a simple formula:
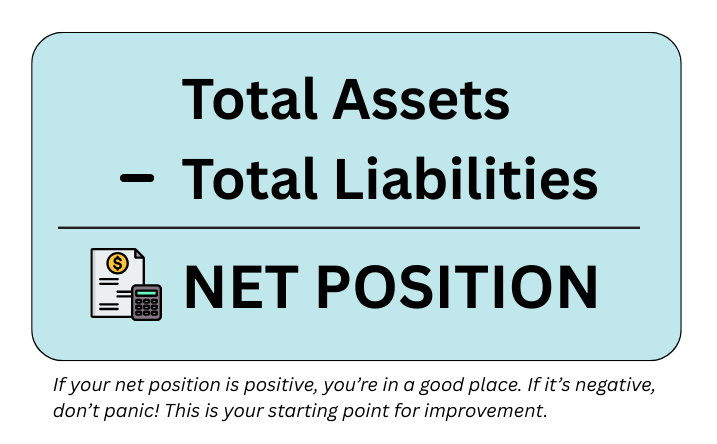
Net Position

Assets include things like your home, car, savings, and investments. Liabilities include mortgages, credit card debt, personal loans, and other financial obligations. Knowing your net position helps you understand whether you’re building wealth or accumulating debt.

Why Net Position Matters More Than Budgeting

Budgeting is about managing your monthly cash flow, how much money comes in and goes out. While this is important, it doesn’t give you a complete picture of your financial health. Here’s why focusing on your net position is a game-changer:

1. PROVIDES A HOLISTIC VIEW

      • Budgeting focuses on short-term goals, like paying bills or saving for a vacation. Net position shows your long-term financial standing, including the value of your assets and the weight of your debts.

2. HELPS SET REALISTIC GOALS

      • Understanding your net position allows you to set achievable financial goals, whether it’s buying a home, retiring early, or becoming debt-free.

3. REVEALS FINANCIAL TRENDS

      • Tracking your net position over time helps you see whether your financial health is improving or deteriorating.

4. GUIDES BETTER DECISION-MAKING

      • Knowing your net position helps you make informed decisions about spending, saving, and investing.

Common Misconceptions About Net Position

Budgeting is about managing your monthly cash flow, how much money comes in and goes out. While this is important, it doesn’t give you a complete picture of your financial health. Here’s why focusing on your net position is a game-changer:

1. “Only Wealthy People Need to Track Their Net Position”

      • False! Everyone, regardless of income level, can benefit from understanding their net position. It’s about knowing where you stand and where you’re headed.

2. “Budgeting Alone is Enough”

      • While budgeting is crucial for managing day-to-day expenses, it doesn’t address your overall financial health.

3. “It’s Too Complicated”

      • Tracking your net position can be as simple as listing your assets and liabilities in a spreadsheet or using a financial app.

Steps to Improve Your Net Position

1. ELIMINATE HIGH-INTEREST DEBT

      • Focus on paying off credit cards and personal loans first. These often carry the highest interest rates and can significantly impact your financial health.

2. INCREASE YOUR SAVINGS

      • Build an emergency fund with at least three to six months’ worth of living expenses. This provides a financial safety net and reduces the need for high-interest debt during emergencies.

3. INVEST WISELY

      • Grow your assets by investing in a diversified portfolio. Consider long-term investments like retirement accounts or real estate.

4. REDUCE LIABILITIES

      • Pay down loans and avoid taking on new debt unless it’s for a strategic purpose, like buying a home.

5. TRACK YOUR PROGRESS

      • Revisit your net position quarterly or annually to measure your progress and adjust your financial plan as needed.

How Our “Know Your Numbers” Course Can Help

Our “Know Your Numbers” course is designed to take the guesswork out of understanding your net position. Here’s what you’ll learn:

1. HOW TO CALCULATE YOUR NET POSITION 

      • Step-by-step guidance on listing your assets and liabilities.

2. TOOLS AND TEMPLATES

      • Access user-friendly calculators and spreadsheets to track your progress.

3. STRATEGIES FOR IMPROVEMENT

      • Learn actionable steps to grow your assets, reduce your liabilities, and increase your net worth.

4. REAL-LIFE EXAMPLES 

      • See how others have transformed their financial health by focusing on their net position.

Success Stories

1. JOAN’S TRANSFORMATION

Joan discovered her net position was negative due to high credit card debt. Using strategies from the course, she paid off her debt in two years and now has a positive net worth of $20,000.

2. PETER’S JOURNEY

Peter thought he was doing well because he had a high income. After calculating his net position, he realised his debt outweighed his assets. He’s since restructured his finances and is on track to achieve financial independence.
Know Your Numbers

Conclusion

Understanding your net position is the key to unlocking financial freedom. It’s not just about how much you earn or spend; it’s about the bigger picture of what you own versus what you owe. By focusing on your net position, you can make smarter financial decisions, set realistic goals, and build a secure future. Ready to take control? Join our “Know Your Numbers” course today and start your journey toward financial clarity and success.
The Vault
10 Small Changes That Can Lead to Big Wins for Your Wallet

10 Small Changes That Can Lead to Big Wins for Your Wallet

When it comes to improving your finances, it’s easy to feel like you need a big windfall or drastic lifestyle changes to make progress. But here’s the truth: small, consistent changes often lead to the biggest wins. Whether it’s trimming everyday expenses, tweaking your habits, or making smarter financial decisions, these small steps can create a ripple effect that transforms your wallet—and your life.

In this blog, we’ll explore 10 simple yet impactful changes you can make today to start seeing big financial results.

1 – Automate Your Savings

One of the easiest ways to build your savings without even thinking about it is to automate the process.

How It Helps:

      • You prioritise savings before spending.
      • It removes the temptation to skip saving.

How To Do It:
Set up a recurring transfer from your checking account to a savings account on payday. Even $10 or $20 a week adds up over time.

Write down every debt you owe, including balances, interest rates, and minimum payments.

2 – Cancel Subscriptions You Don’t Use

Streaming services, gym memberships, and subscription boxes can quietly drain your wallet if you’re not careful.

How It Helps:

      • Frees up money for other priorities.
      • Eliminates guilt over unused services.

How To Do It:
Review your bank statements for recurring charges. Cancel any subscription you haven’t used in the past month.

3 – Switch to Cash for Discretionary Spending

Using cash or visa debit card instead of credit cards for things like dining out, entertainment, or shopping helps you stay within budget.

How It Helps:

      • Makes spending feel more tangible.
      • Helps you avoid overspending.

How To Do It:
As cash is getting hard these days to use and get out, you can either – withdraw a set amount each week for discretionary spending or open a visa debit card where it’s your cash and you can see what you spend and what you have left over. When the cash or money in your visa debit card is gone, you’re done for the week.

Switch to Cash for Discretionary Spending

4 – Meal Prep to Avoid Eating Out

Eating out frequently is one of the biggest budget busters. Preparing meals at home is not only healthier but also significantly cheaper.

How It Helps:

      • Reduces dining-out expenses.
      • Saves time and stress during busy weeks.

How To Do It:
Plan and prepare your meals for the week on Sunday. Cook in batches and store portions in the fridge or freezer.

5 – Negotiate Your Bills

You’d be surprised how many service providers are willing to offer discounts or promotions if you simply ask.

How It Helps:

      • Lowers your monthly expenses.
      • Gives you more breathing room in your budget.

How To Do It:
Call your internet, phone, or insurance provider and ask if they can lower your rate. Mention competitor pricing to strengthen your case.

6 – Unsubscribe from Retail Emails

Retailers are experts at tempting you with “limited-time offers” and discounts. Avoid unnecessary spending by unsubscribing.

How It Helps:

      • Reduces impulse purchases.
      • Keeps your inbox less cluttered.

How To Do It:
Take five minutes to unsubscribe from any email lists that promote shopping. Out of sight, out of mind.

Break Goals into Bite-Sized Steps

7 – Set Mini Financial Goals

Big goals like paying off debt or saving for a house can feel overwhelming. Breaking them into smaller milestones makes them more achievable

How It Helps:

      • Keeps you motivated.
      • Allows you to celebrate small wins.

How To Do It:
If your goal is to save $5,000, start with a mini goal of $500. Reward yourself (in a budget-friendly way) when you hit each milestone.

8 – Sell Items You No Longer Need

Decluttering your home can also give your wallet a boost. From clothes to gadgets, many unused items could be turned into cash.

How It Helps:

      • Provides extra money for savings or debt repayment.
      • Clears up space in your home.

How To Do It:
List items on platforms like Facebook Marketplace, eBay, or Gumtree. Focus on selling things you haven’t used in the past year.

9 – Use Cashback and Rewards Programs

If you’re already spending money, you might as well earn something back. Cashback and rewards programs offer a way to save while you spend.

How It Helps:

      • Reduces the cost of everyday purchases.
      • Can provide free perks like gift cards or travel rewards.

How To Do It:
Take five minutes to unsubscribe from any email lists that promote shopping. Out of sight, out of mind.

    Use Cashback and Rewards Programs

    10 – Track Your Progress

    Financial wins can feel invisible if you’re not paying attention. Regularly tracking your progress helps you stay motivated and see how far you’ve come.

    How It Helps:

        • Keeps you accountable.
        • Provides encouragement to stick with your plan.

    How To Do It:
    Set aside 15 minutes each week to review your budget, check your savings, and reflect on your financial goals.

    How Small Changes Add Up To Big Wins

    Each of these changes might seem minor on its own, but together, they can create a powerful impact. For example:

      • Automating savings builds a habit that grows over time.
      • Canceling unused subscriptions frees up money to pay down debt.
      • Tracking progress keeps you on track toward your larger financial goals.

    When combined, these small actions help you feel more in control of your money and reduce financial stress.

    Why Programs Like Master Your Money Make a Difference

    If you’re looking for a structured way to implement these changes, programs like Master Your Money can guide you. By combining practical tips with personalised coaching, you’ll learn how to make sustainable financial progress and achieve your goals faster.

    Conclusion

    Improving your finances doesn’t have to involve drastic changes or sacrifices. By focusing on small, consistent actions, you can make big strides toward financial stability and freedom. Start with just one or two changes from this list and build from there.

    Remember, every step you take brings you closer to a brighter financial future. So, what small change will you make today?

    The Master Your Money Program is FOR YOU if:

    ?? You’re earning good income but still feel stuck in a cycle of stress or overspending.
    ?? You want to break free from limiting beliefs like “I’m bad with money” or “There’s never enough.”
    ?? You’re ready to build wealth without sacrificing the things you love.
    ?? You dream of financial freedom and need the tools and mindset to make it happen.

    This is more than a mindset shift—it’s a transformation that puts you on the path to lasting financial success! ?

    The 90 Day Money Makeover
    Why Most Resolutions Fail (And How to Succeed with Your Finances This Year)

    Why Most Resolutions Fail (And How to Succeed with Your Finances This Year)

    Every January, millions of people make resolutions, vowing to lose weight, save money, or finally organise their lives. Yet, by February, most of those resolutions are a distant memory. When it comes to finances, the stakes are even higher, failed resolutions can lead to continued debt, stress, and a lack of progress toward your goals. But why do so many resolutions fail? More importantly, how can you set yourself up for success, especially with your financial goals?

    This year, let’s break the cycle. Here’s why most resolutions don’t stick and how you can set realistic, actionable financial goals that actually work.

    New Year's Resolutions and Goals

    The Problem with Resolutions

    1. They’re Too Vague
    A resolution like “save more money” or “spend less” sounds great in theory, but without specifics, it’s destined to fail. What does “save more” mean? How much? By when? Without clarity, it’s easy to lose focus.

    2. No Plan, Just Hope
    Many resolutions rely on sheer willpower. While motivation can get you started, it won’t sustain you for the long haul. A solid plan is essential for turning intentions into results.

    3. All-or-Nothing Thinking
    Ever decided to “cut all unnecessary spending” and then given up after one unplanned purchase? All-or-nothing approaches set you up for failure because they don’t allow for flexibility.

    4. No Accountability
    When no one knows about your goals, it’s easy to let them slide. Having someone to cheer you on, or nudge you when you’re slipping makes a huge difference.

    Why Financial Intentions Are Different

    Financial goals often come with emotional baggage. Many of us have habits or mindsets about money that were shaped long before we started earning. Whether it’s fear of budgeting, guilt about past mistakes, or simply feeling overwhelmed, these emotions can sabotage even the best intentions.

    The good news? Financial habits are learnable. With the right mindset, tools, and support, you can rewrite your financial story.

    How to Succeed with Your Financial Goals This Year

    1. Get Specific About Your Goals
    Instead of “save more money,” try something like:

          • “Save $1,000 for an emergency fund by March 31.”
          • “Pay an extra $200 per month toward my credit card debt.”
          • “Spend no more than $400 a month on dining out.”

    Specific goals give you a clear target to aim for. Break them down into smaller, actionable steps, and you’ll feel a sense of accomplishment with every milestone.

    2. Create a 90-Day Action Plan
    While it’s tempting to set year-long goals, short-term plans are more effective. That’s why 90 days is the perfect timeframe—it’s long enough to make meaningful progress but short enough to stay motivated.
    For example:

          • Month 1: Assess your financial situation. Track all your expenses and create a realistic budget.
          • Month 2: Implement your budget and identify areas to cut back. Start small, like reducing subscription services or packing lunches for work.
          • Month 3: Focus on building momentum. Add any savings or debt reduction progress to your plan.
    While it’s tempting to set year-long goals, short-term plans are more effective.

    3. Reframe Your Money Mindset
    Your mindset plays a massive role in your financial success. If you believe “I’m just bad with money” or “I’ll never get out of debt,” those beliefs will hold you back. Instead, practice positive affirmations like:

          • “I am capable of learning new money skills.”
          • “Every small step I take brings me closer to financial freedom.”

    Even better, pair these affirmations with concrete actions. Every time you stick to your budget or save a little extra, you’re proving to yourself that change is possible.

    4. Start Small But Stay Consistent
    Big changes often fail because they’re overwhelming. Start with small, manageable habits that build over time.

          • Save $5 a day by skipping a coffee run.
          • Commit to a weekly money check-in where you review your budget and spending.
          • Set up automatic transfers to your savings account—even if it’s just $10 a week.

    These small wins add up and help build confidence and momentum.

    5. Track Your Progress
    It’s easy to lose motivation when you don’t see results. That’s why tracking is so important. Whether it’s a spreadsheet, an app, or even a notebook, record every step of your financial journey.

          • Watch your savings grow each week.
          • Celebrate when you pay off a credit card.
          • Note the changes in your spending habits.

    Seeing progress, no matter how small, reinforces your commitment to your goals.

    6. Find Your Why
    Why do you want to improve your finances? Maybe it’s to take your family on a dream vacation, eliminate the stress of living paycheck to paycheck, or finally buy a home.

    Your “why” is your motivation. Write it down, visualize it, and keep it front and center. When the going gets tough, reminding yourself of your deeper purpose will help you stay on track.

    7. Get Support
    Accountability is a game-changer. Whether it’s a friend, partner, or coach, having someone to share your goals with can make all the difference. Programs like the 90-Day Money Makeover offer a built-in support system, with resources, community, and guidance to keep you on track.

    Common Pitfalls and How to Avoid Them

    1. Expecting Perfection
    You will slip up and that’s okay. What matters is how you recover. Instead of giving up after a mistake, ask yourself: “What can I learn from this?”

    2. Overloading Yourself
    Don’t try to tackle everything at once. Focus on one or two key goals at a time. Once you’ve mastered them, move on to the next.

    3. Comparing Yourself to Others
    Your financial journey is unique. Comparing your progress to others will only discourage you. Stay focused on your own goals and celebrate your wins.

    Conclusion

    This year, break the cycle of failed resolutions and make 2025 the year you take control of your finances. By setting clear goals, creating a plan, and staying consistent, you’ll build habits that last a lifetime.

    Remember: small steps lead to big changes. Start with one goal today, and by next January, you’ll be amazed at how far you’ve come. If you’re ready to supercharge your progress, join the LEARNING HUB and get immediate access to all courses and books including ongoing financial and mindset monthly coaching now.

    Financial Resolutions

    Your financial future is in your hands — let’s make it a great one! Click the button below to join the LEARNING HUB at FINANCIAL MANAGEMENT 101. It promotes long-term financial stability, provides insights into wealth-building strategies, and equips you with the skills to adapt to economic changes.

    The 90 Day Money Makeover