From Chaos to Clarity: How to Create a Money Plan That Actually Works

From Chaos to Clarity: How to Create a Money Plan That Actually Works

Ever feel like your money is running you instead of the other way around? Like no matter how much you earn, there’s always more month than money?

If you nodded (or sighed), you’re not alone. The good news? You don’t need a finance degree, a six-figure income, or a strict budget to take control. You just need a money plan that works for you.

In this blog, we’ll ditch the overwhelm and walk through exactly how to create a simple, empowering money plan that gives you clarity, confidence, and real momentum.

Let’s go from chaos to clarity – starting today.

1. Start With Your “Why”: Anchor Your Money to What Matters

Before we dive into numbers, let’s get clear on your why. Because unless your money plan connects to something meaningful, it won’t stick.

Ask yourself:

  • What would feeling in control of my money allow me to do?
  • What does financial peace look like to me?
  • What am I working toward?

Your answers might include:

  • Paying off debt to sleep better at night
  • Saving for a dream trip or home deposit
  • Creating options so you can work less or start a business

Write your top 2 – 3 motivations down. These are your compass when the budget feels boring or things go off track.

2. Know Your Numbers (Without the Shame Spiral)

You can’t improve what you don’t measure. So let’s get honest, not harsh. Gather the basics:

  • Your income (all sources)
  • Your recurring bills
  • Your debt repayments
  • Your spending patterns (groceries, eating out, transport, etc.)
  • Your current savings and investments

Pro tip: Use the last 2–3 months of bank statements to see where your money actually went. You might be surprised (hello, Uber Eats). This isn’t about judgment. It’s about clarity.

3. Create a Simple Money Plan (The 70/20/10 Rule)

Forget complicated budgets with 47 categories. Here’s a simple, flexible formula you can actually stick to:

  • 70% for living: rent/mortgage, groceries, transport, lifestyle
  • 20% for financial goals: savings, debt repayments, investments
  • 10% for the future: extra super, long-term wealth building

The percentages aren’t set in stone. Adjust based on your situation. The key is having a structure that makes sure you’re not spending 100% of your income with nothing left to show for it.

Action step: Plug your own numbers into this formula and see where you land. If you’re off track, that’s your roadmap for change.
Create a Simple Money Plan

4. Automate Your Money Flow (And Take the Stress Out)

Once you know where your money should go, make it happen on autopilot.
Set up automatic transfers:

  • To a separate savings account (nickname it for motivation: “Italy 2026” or “Debt-Free Me”)
  • To cover bills and direct debits
  • To long-term savings or investment accounts

When you automate, you eliminate the willpower game. You’ll save without thinking and avoid last-minute money panic.

Bonus tip: Use a separate account for discretionary spending (like a digital “cash envelope”). When it’s empty, it’s empty.
5. Create an Emergency Buffer (For Life’s “Oh No!” Moments)

Life is full of surprises. Your washing machine breaks, your car needs fixing, or your job suddenly changes.

Having even $1,000 in a buffer fund means you don’t have to reach for the credit card every time life happens.

Aim for 1 month of essential expenses first, then build to 3. But start where you are, every $50 counts. Keep it in a separate high-interest savings account you can access in a true emergency (not Friday night online shopping).

6. Track Progress Without Obsessing

You don’t need to check your bank app five times a day. But regular check-ins keep you engaged and help you spot problems early.

Ideas to stay on track:

  • Weekly money date: review transactions, check balances, update goals
  • Monthly review: celebrate wins, adjust if needed

Use a simple app or spreadsheet to track goals

The goal isn’t perfection. It’s progress.

7. Keep Learning and Stay Inspired

Your relationship with money is lifelong. The more you understand it, the more confident you’ll feel. Try:

  • Reading a finance book this quarter
  • Listening to a weekly money podcast
  • Following finance educators on socials
  • Booking a session with a financial coach to personalise your plan

There’s no shame in not knowing something – only in staying stuck.

Clarity = Confidence = Momentum

When your money feels chaotic, it can affect everything: your stress levels, your sleep, your relationships, and your ability to plan ahead. But creating a money plan that actually works isn’t about spreadsheets or sacrifice. It’s about:

  • Getting clear on what matters to you
  • Creating a simple, sustainable system
  • Building habits that support your goals

And the best part? You can start today. One step. One decision. One plan.

If you’re ready to get out of the fog and into financial clarity, let’s talk. Book your free discovery call and let’s map out your next steps – with zero jargon, zero judgment, and 100% support.

Because you can feel good about your money. You just need a plan that fits your life.

No more chaos. It’s your time for clarity. Let’s make it happen.
Mastering Budgeting and Saving
The Vault
The Big Picture: Why Net Position Matters More Than Budgeting

The Big Picture: Why Net Position Matters More Than Budgeting

When people think about managing their finances, budgeting is often the first thing that comes to mind. While budgeting is an essential tool, it’s only one piece of the puzzle. To truly take control of your financial life, you need to understand your net position. This bigger-picture view is the cornerstone of long-term financial success. In this blog, we’ll dive into what net position is, why it matters, and how it can transform your approach to money management.

What is Net Position?

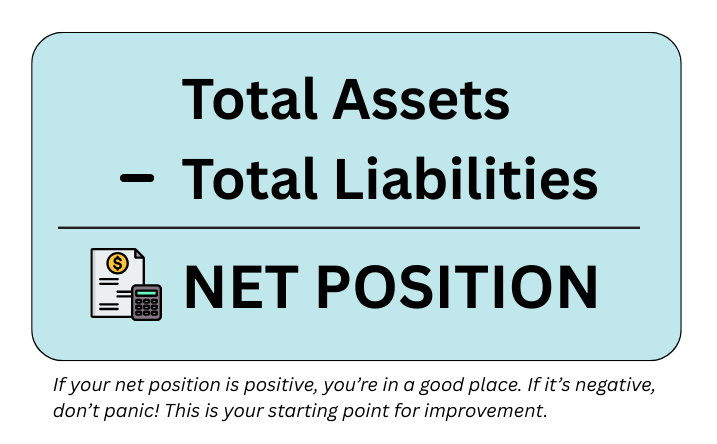
Your net position is the difference between what you own (your assets) and what you owe (your liabilities). It’s essentially your financial scorecard, giving you a snapshot of your overall financial health. Here’s a simple formula:

Net Position

Assets include things like your home, car, savings, and investments. Liabilities include mortgages, credit card debt, personal loans, and other financial obligations. Knowing your net position helps you understand whether you’re building wealth or accumulating debt.

Why Net Position Matters More Than Budgeting

Budgeting is about managing your monthly cash flow, how much money comes in and goes out. While this is important, it doesn’t give you a complete picture of your financial health. Here’s why focusing on your net position is a game-changer:

1. PROVIDES A HOLISTIC VIEW

      • Budgeting focuses on short-term goals, like paying bills or saving for a vacation. Net position shows your long-term financial standing, including the value of your assets and the weight of your debts.

2. HELPS SET REALISTIC GOALS

      • Understanding your net position allows you to set achievable financial goals, whether it’s buying a home, retiring early, or becoming debt-free.

3. REVEALS FINANCIAL TRENDS

      • Tracking your net position over time helps you see whether your financial health is improving or deteriorating.

4. GUIDES BETTER DECISION-MAKING

      • Knowing your net position helps you make informed decisions about spending, saving, and investing.

Common Misconceptions About Net Position

Budgeting is about managing your monthly cash flow, how much money comes in and goes out. While this is important, it doesn’t give you a complete picture of your financial health. Here’s why focusing on your net position is a game-changer:

1. “Only Wealthy People Need to Track Their Net Position”

      • False! Everyone, regardless of income level, can benefit from understanding their net position. It’s about knowing where you stand and where you’re headed.

2. “Budgeting Alone is Enough”

      • While budgeting is crucial for managing day-to-day expenses, it doesn’t address your overall financial health.

3. “It’s Too Complicated”

      • Tracking your net position can be as simple as listing your assets and liabilities in a spreadsheet or using a financial app.

Steps to Improve Your Net Position

1. ELIMINATE HIGH-INTEREST DEBT

      • Focus on paying off credit cards and personal loans first. These often carry the highest interest rates and can significantly impact your financial health.

2. INCREASE YOUR SAVINGS

      • Build an emergency fund with at least three to six months’ worth of living expenses. This provides a financial safety net and reduces the need for high-interest debt during emergencies.

3. INVEST WISELY

      • Grow your assets by investing in a diversified portfolio. Consider long-term investments like retirement accounts or real estate.

4. REDUCE LIABILITIES

      • Pay down loans and avoid taking on new debt unless it’s for a strategic purpose, like buying a home.

5. TRACK YOUR PROGRESS

      • Revisit your net position quarterly or annually to measure your progress and adjust your financial plan as needed.

How Our “Know Your Numbers” Course Can Help

Our “Know Your Numbers” course is designed to take the guesswork out of understanding your net position. Here’s what you’ll learn:

1. HOW TO CALCULATE YOUR NET POSITION 

      • Step-by-step guidance on listing your assets and liabilities.

2. TOOLS AND TEMPLATES

      • Access user-friendly calculators and spreadsheets to track your progress.

3. STRATEGIES FOR IMPROVEMENT

      • Learn actionable steps to grow your assets, reduce your liabilities, and increase your net worth.

4. REAL-LIFE EXAMPLES 

      • See how others have transformed their financial health by focusing on their net position.

Success Stories

1. JOAN’S TRANSFORMATION

Joan discovered her net position was negative due to high credit card debt. Using strategies from the course, she paid off her debt in two years and now has a positive net worth of $20,000.

2. PETER’S JOURNEY

Peter thought he was doing well because he had a high income. After calculating his net position, he realised his debt outweighed his assets. He’s since restructured his finances and is on track to achieve financial independence.

Know Your Numbers

Conclusion

Understanding your net position is the key to unlocking financial freedom. It’s not just about how much you earn or spend; it’s about the bigger picture of what you own versus what you owe. By focusing on your net position, you can make smarter financial decisions, set realistic goals, and build a secure future. Ready to take control? Join our “Know Your Numbers” course today and start your journey toward financial clarity and success.

The Vault